
What Is the Difference Between a Property Appraisal and a Valuation?
I get asked this almost every week, usually by someone who's just been quoted two very different figures for the same house and has no idea why. A property appraisal and a valuation sound like they should mean the same thing, and plenty of people use the words interchangeably without a second thought. They don't mean the same thing, and mixing them up can cost you money, whether you're selling, refinancing, or settling a dispute. Let's clear it up properly.
The Short Answer First
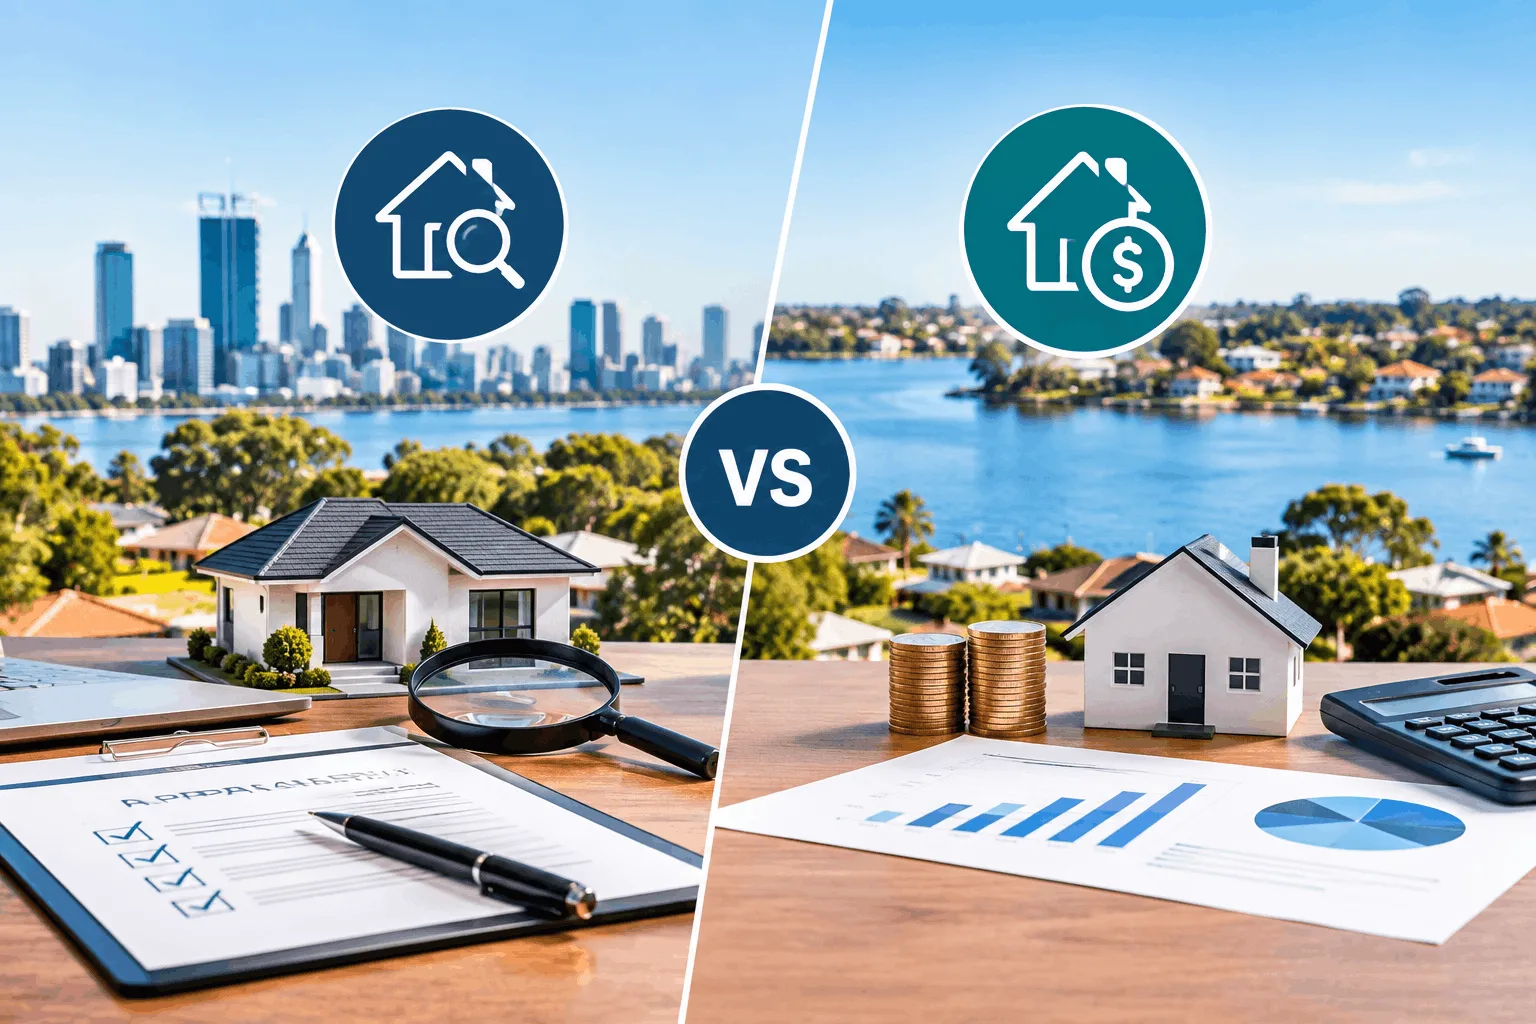
A property appraisal is an agent's estimate of what your home will likely sell for in the current market, based on comparable sales and buyer demand. A valuation is a formal, legally recognised assessment carried out by a licensed valuer, often required by a bank, court, or government body. One is a market opinion. The other is a certified figure. That's the core difference, and everything below explains why it matters.
What a Property Appraisal Actually Is
1. Who Provides an Appraisal
An appraisal comes from a real estate agent Perth homeowners have engaged to sell their property, or from an agent they're simply considering using. Any licensed agent can walk through a home and provide one. As a real estate agent Perth sellers have worked with since 2018, I offer these appraisals free of charge and without obligation, because it's part of how the sale process starts, not a paid professional service.
2. What Goes Into the Number
A solid appraisal is built on recent comparable sales in the immediate area, current listings competing for the same buyers, feedback from recent home opens, and general market momentum. It also factors in things a computer can't, like how a kitchen actually feels when you walk into it, or whether a renovation was done well or just done cheaply.
3. When You'd Use One
You'd get an appraisal when you're thinking about selling, even if that's still a year away. It's also useful if you simply want a realistic read on your equity position before making a decision about upsizing, downsizing, or investing further.
What a Valuation Actually Is
1. Who Provides a Valuation
A valuation must come from a licensed, qualified valuer, someone accredited through bodies like the Australian Property Institute. Unlike an appraisal, this isn't something any property agent Perth wide can legally provide. It's a distinct profession with its own qualifications and regulatory standards.
2. What Goes Into the Number
Valuers follow a formal, standardised methodology. They inspect the property in detail, assess land size and zoning, review title documents, and cross reference sales data through a structured, documented process. The end result is a certified report that can be relied upon in legal, financial, or taxation contexts.
3. When You'd Use One
You'll need a valuation for mortgage refinancing, for probate and deceased estate matters, during a divorce settlement, for capital gains tax purposes, or whenever a bank requires an independent figure before releasing funds. Lenders generally won't accept an agent's appraisal for these purposes, no matter how accurate it turns out to be.
Appraisal vs Valuation: Where the Real Differences Show Up
1. Cost and Accessibility
Appraisals are typically free and can usually be arranged within a day or two. Valuations come with a fee, often several hundred dollars, and require booking a licensed valuer's time.
2. Accuracy and Legal Weight
An experienced agent's appraisal can be remarkably close to a home's eventual sale price, particularly in an active suburb where recent sales data is plentiful. However, it carries no legal standing. A valuation, by contrast, is defensible in court and accepted by financial institutions precisely because it follows a certified process.
3. Turnaround Time
Appraisals happen fast because they're designed to help you make quick decisions about selling. Valuations take longer, sometimes a week or more, because of the detailed inspection and documentation involved.
Common Mistakes Sellers and Buyers Make
1. Treating an Appraisal as a Guarantee
An appraisal is a professional estimate, not a promise. Markets shift, buyer sentiment changes, and a figure given in autumn may not hold by winter. Any honest property agent Perth residents trust will tell you an appraisal is a starting point for strategy, not a fixed number carved in stone.
2. Skipping a Valuation Before Refinancing
Some homeowners assume their agent's appraisal will satisfy their bank. It won't. Lenders require an independent valuation precisely because they need a figure free from any incentive to sell.
3. Choosing Based on the Highest Number
If one appraisal comes in noticeably higher than the rest, that's not necessarily good news. Overpricing a property to win a listing is one of the fastest ways to have it sit unsold, and an inflated appraisal that isn't backed by genuine comparable sales usually reveals itself the moment the home hits the market.
Which One Do You Actually Need?
Think of it this way. An appraisal is like asking a friend who knows the neighbourhood well what your car might sell for on Facebook Marketplace this weekend. A valuation is like taking that same car to an official assessor for a certified report a bank will actually accept. Both have their place, and neither replaces the other.
If you're weighing up whether to sell, start with a free appraisal from a local real estate agent Perth families have relied on for years, someone who knows the street, the school catchments, and what buyers are actually paying right now. If you're refinancing, settling an estate, or need a legally defensible figure, book a licensed valuer instead.
Conclusion
A property appraisal and a valuation might sound like two names for the same thing, but they serve entirely different purposes. An appraisal gives you a fast, free, market informed estimate from a property agent Perth sellers can call on when they're weighing up a sale. A valuation gives you a certified, legally recognised figure for banks, courts, and government purposes. Knowing which one you actually need, before you pick up the phone, saves you time, money, and a fair bit of confusion down the track.
FAQs
1. Can I use an agent's appraisal instead of a bank valuation?
No. Banks require an independent, licensed valuation for lending purposes and won't accept a real estate agent's market appraisal as a substitute, regardless of how accurate it is.
2. Why is a valuation more expensive than an appraisal?
A valuation involves a licensed professional conducting a formal, documented inspection and assessment that carries legal weight, which naturally comes with a fee. An appraisal is a complimentary service most agents offer as part of building a relationship with a potential seller.
3. How accurate are property appraisals compared to valuations?
An experienced agent's appraisal can land very close to the eventual sale price, especially in suburbs with plenty of recent comparable sales. Valuations are typically more conservative and methodical, since they're built for legal and financial reliability rather than market strategy.
4. Do I need a valuation to sell my home?
Not usually. Most sellers only need an appraisal from a trusted property agent Perth wide to guide their pricing strategy. A valuation only becomes necessary if a specific legal or financial situation requires one.
5. How often should I get my property appraised?
If you're actively considering selling within the next twelve months, an annual appraisal is a sensible habit. It keeps you informed about your equity position and current market conditions without any cost or obligation.
0 comments
Log in to leave a comment.
Be the first to comment.