
What Happens to a HELOC When the Borrower Dies? A Guide for Homeowners and Heirs
When a homeowner dies, family members may need to address several financial and legal responsibilities, including an outstanding mortgage, property taxes, insurance, and any home equity line of credit (HELOC) secured by the property. Understanding what happens to a HELOC after the borrower’s death can help surviving family members, co-borrowers, and heirs make informed decisions about the home.
A HELOC does not automatically disappear when its borrower dies. The outstanding balance generally remains a debt that must be addressed through the applicable estate, the obligations of any surviving co-borrower, or other arrangements permitted by the loan agreement and state law. At the same time, inheriting a home does not automatically mean that the heir becomes personally responsible for every debt associated with it.
The outcome depends on several factors, including who signed the credit agreement, how the property was owned, whether another borrower remains on the account, the terms of the HELOC, and how ownership passes after death. Understanding these distinctions is essential before deciding whether to retain the property, sell it, or explore ways to resolve the outstanding balance.
Does a HELOC End When the Borrower Dies?
Generally, the death of a borrower does not automatically erase an outstanding HELOC balance. A home equity line of credit is a secured credit arrangement that allows a borrower to access funds against equity in a property. If money remains outstanding when the borrower dies, the obligation must still be addressed.
The lender's rights depend on the credit agreement, applicable law, and the circumstances surrounding the borrower's death. The account may require servicing changes, restrictions on further borrowing, repayment arrangements, or another action specified by the agreement and permitted by law.
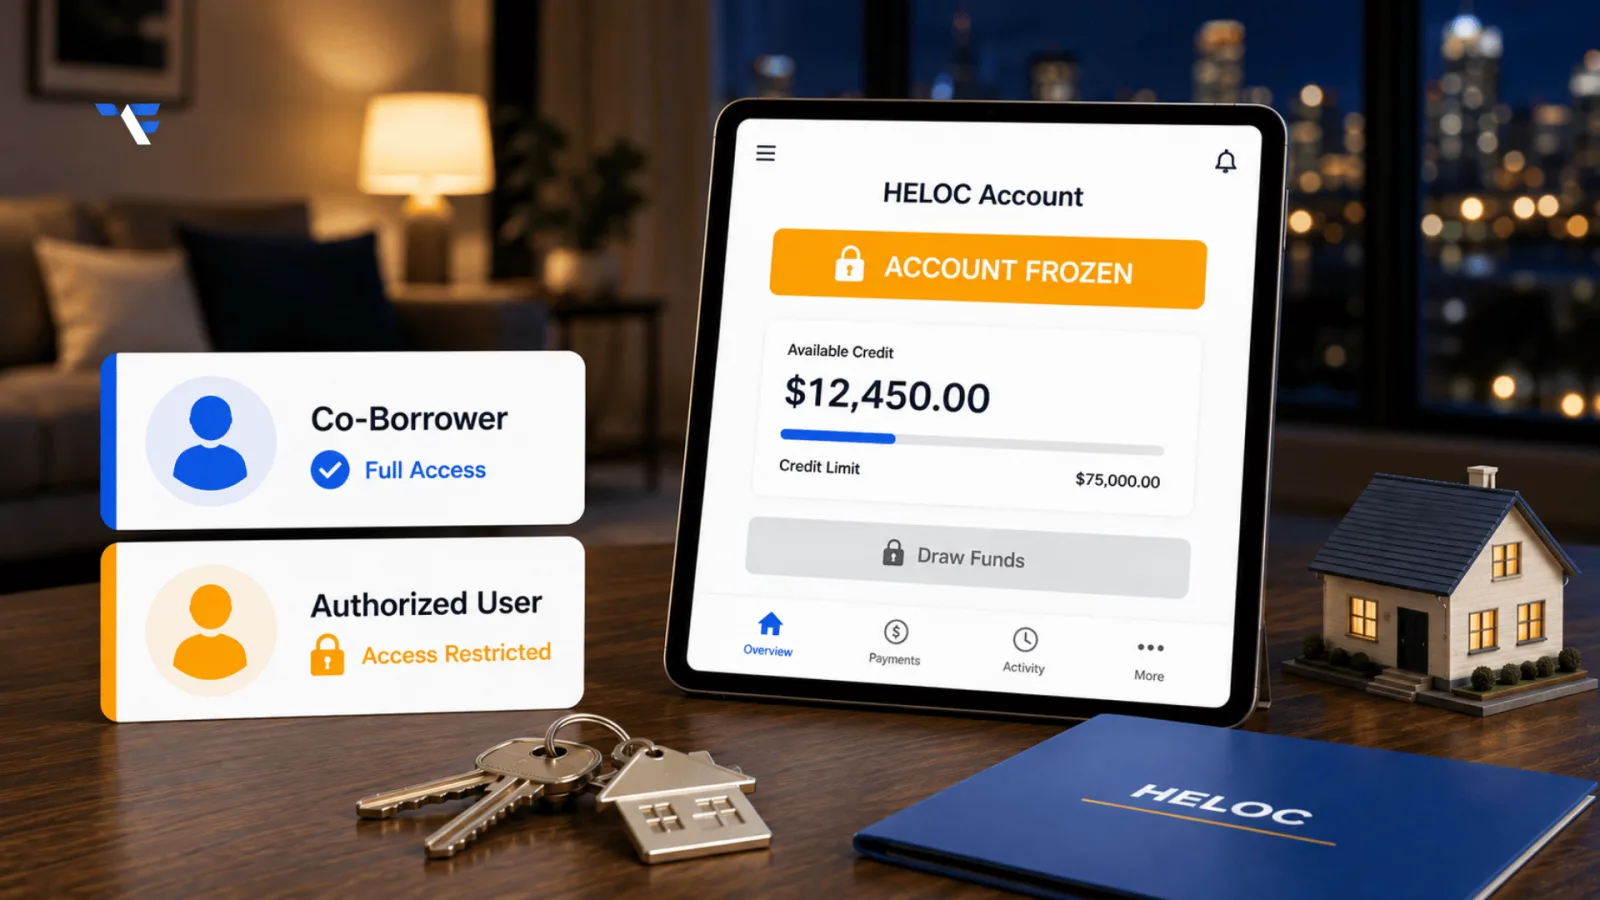
It is important to distinguish between the unused credit limit and the amount already borrowed. A HELOC may have an approved credit limit substantially higher than its current balance. The outstanding debt does not become zero merely because the borrower has died, and heirs should not assume that unused credit remains available to them.
For a general explanation of the credit arrangement, homeowners and family members can review how a HELOC works. Understanding the distinction between the credit limit, outstanding balance, and repayment obligations provides a useful starting point for evaluating the account after a death.
Who Is Responsible for the Outstanding HELOC Balance?
One of the most important questions after a borrower's death is who is legally responsible for the debt. The answer depends on the individual's role in the credit agreement and the rules governing the estate and property.
The Estate of the Deceased Borrower
If the deceased borrower had an outstanding HELOC, the debt may need to be addressed during estate administration. Depending on state law, the estate's assets and applicable creditor-priority rules determine how valid debts are handled.
An executor or personal representative may need to identify the HELOC, obtain account information, review the balance, and coordinate with the lender. The representative should also determine whether the debt is secured by the property and how it affects the estate's plans for the home.
The existence of a debt does not necessarily mean that the executor must personally pay it from their own funds. A personal representative's duties and liabilities depend on applicable law and the circumstances of the estate. Executors should obtain legal guidance before distributing estate assets or using funds to resolve disputed obligations.
A Surviving Co-Borrower
If another person signed the HELOC agreement as a co-borrower, that person's contractual responsibilities generally continue after the other borrower dies. The death of one borrower does not ordinarily cancel the obligations of the surviving borrower.
For example, if two spouses jointly obtained a HELOC, the surviving spouse may remain responsible for the outstanding balance under the credit agreement. The exact outcome depends on the signed documents and applicable law.
A co-owner of the home is not necessarily a co-borrower, however. Property ownership and contractual responsibility for a debt are different legal questions. A person should review the HELOC agreement rather than assume that being listed on the deed automatically makes them responsible for the credit line—or that being absent from the deed necessarily determines their responsibility.
An Heir Who Inherits the Home
An heir may receive ownership of a property that secures a HELOC without automatically becoming personally liable for the original borrower's debt. Whether an heir assumes personal liability depends on factors such as the loan documents, any later agreement, applicable law, and the manner in which the property is transferred.
However, the fact that an heir may not be personally liable does not necessarily mean the property is free from the HELOC. Because the credit line is secured by the home, the lender may retain rights against the collateral under the agreement and applicable law.
This distinction is critical: personal liability for a debt and the lender's rights against the property are not the same thing. An heir should not assume that inheriting the home eliminates the lien or that the heir must automatically pay the balance from personal assets.
What Happens to the Home After the Borrower's Death?
The ownership of the home is determined by the way title was held, the estate documents, applicable state inheritance law, and any relevant trust or survivorship arrangement.
For example, a property held jointly with a valid right of survivorship may pass differently from a property owned solely by the deceased person. A home held in a trust may be administered according to the trust's terms, while property owned individually may become part of probate or another estate-transfer process.
These ownership arrangements can affect who is entitled to make decisions about the property. They do not necessarily eliminate an existing HELOC or determine by themselves who is personally liable for the debt.
Before deciding what to do with the property, family members should establish who legally owns it, whether probate or another transfer process is required, and whether the HELOC remains secured against it.
Can the Heir Keep the Home if There Is an Outstanding HELOC?
In many circumstances, a surviving family member or heir may be able to retain a home that has an outstanding HELOC. Whether that is practical depends on the loan agreement, the lender's rights, the estate's circumstances, and the heir's ability to manage the property's ongoing costs and any required debt payments.
Keeping the home may involve one or more of the following steps:
• Confirming the legal ownership of the property.
• Identifying the outstanding HELOC balance and other liens.
• Determining whether a surviving co-borrower remains responsible for payments.
• Contacting the lender or servicer to explain the death and establish the appropriate communication process.
• Reviewing the repayment terms and any applicable deadlines.
• Evaluating whether the existing debt can be maintained, paid down, refinanced, or otherwise resolved.
An heir should not assume that the lender must approve a new HELOC or refinance simply because the heir has inherited the property. New financing generally involves its own eligibility requirements, and the property's equity alone may not establish that the heir can qualify.
Can the Lender Demand Immediate Repayment?
Whether a lender can require immediate repayment after a borrower's death depends on the HELOC agreement and applicable law. The death itself does not establish a universal rule that every HELOC becomes immediately payable in full.
Some credit agreements contain provisions addressing the death of a borrower, changes in ownership, default, or termination of the credit line. Those provisions must be considered alongside any applicable legal protections.
It is also important to distinguish a lender's ability to stop future advances from its ability to terminate the agreement or accelerate the entire outstanding balance. These actions can have different requirements under federal law and the contract.
Family members should request a written explanation of any deadline or demand for repayment. If the lender states that the full balance is due, the executor, surviving borrower, or heir should review the relevant agreement and seek legal advice when the basis for the demand is unclear.
What Are Successors in Interest, and Why Do They Matter?
In mortgage servicing, a successor in interest generally refers to a person who acquires an ownership interest in a property securing a mortgage loan through certain qualifying transfers. Depending on the circumstances, this may include a surviving spouse, a relative who inherits the property, or another qualifying person.
Federal mortgage-servicing rules require servicers to maintain procedures for identifying potential successors in interest and facilitating communication with them. Under applicable circumstances, a servicer must explain what documents it reasonably requires to confirm a person's identity and ownership interest.
The Consumer Financial Protection Bureau has highlighted problems families can experience when mortgage companies fail to communicate effectively after a death or divorce. The rules are intended to help eligible successors establish their status and communicate with the servicer. The CFPB's report on mortgage servicing after death or divorce explains why these situations can be difficult for homeowners and their families.
However, legal protections relating to mortgage servicing should not be interpreted as automatically transferring the original borrower's personal debt to an heir—or as eliminating the debt. The legal status of the successor, the type of credit agreement, and the applicable regulations all matter.
What Documents Might the Lender Request?
When a family member contacts the lender after a borrower's death, the servicer may need documentation to verify the death and establish who is authorized to discuss the account or has an ownership interest in the property.
Depending on the circumstances and state law, documents may include:
• A certified or otherwise acceptable copy of the death certificate.
• A will or relevant trust documents.
• Letters testamentary, letters of administration, or another document establishing the personal representative's authority.
• A recorded deed or other evidence of property ownership.
• A court order or other documentation establishing the transfer of ownership.
• Identification and information connecting the request to the relevant HELOC account.
Not every case requires every document on this list. Federal servicing rules generally contemplate reasonable documentation requirements that reflect the jurisdiction, the circumstances, and the information already available to the servicer.
Family members should ask the lender for a written list of the specific documents required and how to submit them securely. They should keep copies of all correspondence and records of communication.
Can an Heir Continue Making Payments?
Making payments on an outstanding HELOC may help prevent the account from becoming delinquent while the family determines what to do with the property. However, the appropriate person to make payments and the legal effect of those payments depend on the circumstances.
A surviving co-borrower generally needs to continue meeting their contractual obligations. An executor may also need to manage estate debts and property expenses as part of estate administration. An heir who is not personally liable should obtain advice before making payments from personal funds, particularly if the ownership of the home or responsibility for the debt remains disputed.
Anyone considering payments should confirm the current balance, payment amount, payment instructions, and any applicable deadlines directly with the servicer. They should also ask how payments will be credited and whether any other action is required to keep the account in good standing.
Making a payment should not be assumed to transfer ownership, establish personal liability, modify the contract, or resolve a dispute about the debt. Those questions may require separate legal analysis.
What if the Family Wants to Sell the Home?
Selling the property may be one way to resolve an outstanding HELOC, particularly when the family does not intend to retain the home or when the estate needs to distribute its assets.
Because the HELOC is secured by the property, the lender's lien generally needs to be addressed as part of the sale. The closing process typically involves obtaining a payoff statement, confirming the amount required to satisfy the debt, and arranging for the lien to be released according to the lender's procedures.
The amount remaining after the sale depends on the sale price, the HELOC payoff, any first mortgage, other liens, transaction costs, and applicable estate obligations.
If the sale proceeds are insufficient to satisfy all secured debts and costs, the family should not assume the sale can proceed without further arrangements. The lender, estate representative, closing professionals, and legal advisers may need to determine the available options.
Before listing the home, confirm who has authority to sell it and whether the estate or ownership-transfer process permits the transaction.
Can the HELOC Be Refinanced After the Borrower's Death?
Refinancing may be an option in some circumstances, but it is not automatic. A surviving co-borrower or eligible property owner may need to qualify for new financing under the prospective lender's requirements.
The lender will generally consider factors relevant to the new application, which may include income, credit history, existing obligations, property value, and the amount of equity available. The new financing must also address the existing HELOC and any other liens that affect the property.
Some heirs may not have sufficient income or credit to qualify for refinancing, even if the property has substantial equity. Others may decide that selling the property is more appropriate than taking on a new debt obligation.
Before pursuing a refinance, the family should establish who owns the home, who is liable for the existing debt, whether the existing lender has imposed any deadlines, and whether the proposed transaction is legally and financially feasible.
What if the HELOC Has No Outstanding Balance?
A HELOC with a zero balance raises different questions from one with money already borrowed. If no balance is outstanding, there may be no principal debt to repay at that moment, but the account and the lien may still need to be addressed.
The credit agreement may contain provisions about the death of a borrower, account termination, future advances, and changes in ownership. The lender may also have requirements for closing the account and releasing the lien, if applicable.
Family members should not assume that an unused line automatically remains open for an heir to draw from. A person who did not sign the original agreement generally cannot assume the right to borrow under it simply by inheriting the property.
Contact the lender to confirm the balance, status of the account, whether further draws are permitted, and the process for closing the account or releasing the lien where appropriate.
Common Mistakes Families Should Avoid
Managing a home and an outstanding HELOC after a death can be complicated. Avoiding a few common mistakes can help families protect their interests while they establish the facts.
Assuming the Debt Disappears
The death of the borrower generally does not erase an outstanding secured debt. Families should obtain current account information and determine how the obligation must be addressed.
Assuming Every Heir Is Personally Liable
Inheriting a property does not automatically make a person personally responsible for every debt incurred by the deceased. Personal liability and the lender's rights against the property should be evaluated separately.
Ignoring Lender Communications
Notices about missed payments, account status, or required documentation should not be ignored. Promptly contacting the servicer can help clarify deadlines and identify what information is needed.
Transferring or Selling the Property Without Reviewing the Liens
Ownership transfers and property sales can involve legal requirements and existing lien obligations. Before signing documents or distributing proceeds, confirm the property's legal status and the steps needed to address secured debts.
Using Personal Funds Without Understanding the Consequences
A family member who is not a borrower should be careful before paying an estate debt from personal funds. Legal advice can help clarify the person's rights, obligations, and the potential effect of the payment.
Practical Steps to Take After a HELOC Borrower Dies
Although each situation is different, the following sequence can help a family organize the process.
• Locate the HELOC agreement. Identify the borrower or borrowers, account terms, outstanding balance, and any relevant provisions about death, default, or ownership transfers.
• Determine who owns the property. Review the deed, will, trust documents, and applicable inheritance rules.
• Contact the lender or servicer. Notify the appropriate party of the death and ask how to establish authorized communication.
• Request a current account statement. Confirm the outstanding balance, payment requirements, and any stated deadlines.
• Gather the required documents. Ask for the lender's specific requirements rather than assuming that a single document will be sufficient.
• Keep track of ongoing expenses. Property taxes, insurance, maintenance, and other housing expenses may continue while the estate is being administered.
• Evaluate the available options. Depending on the circumstances, the family may consider maintaining the property, paying off the HELOC, refinancing, or selling.
• Seek qualified advice. Consult an estate attorney or other qualified professional when personal liability, inheritance rights, or the lender's legal rights are unclear.
For homeowners and families reviewing the wider financial implications of secured borrowing, home equity guidance can also provide general context for understanding how equity-related obligations interact with property ownership and long-term financial decisions.
Frequently Asked Questions
Does a HELOC automatically become due when the borrower dies?
Not necessarily. The outcome depends on the credit agreement, applicable law, and circumstances surrounding the death. Families should review the agreement and obtain a written explanation from the lender before assuming that the entire balance is immediately payable.
Does an heir have to pay a deceased parent's HELOC?
Not automatically from personal funds. The debt may need to be addressed through the estate, and the property may remain subject to the HELOC lien. Personal liability depends on the loan documents, applicable law, and whether the heir has assumed an obligation or is otherwise liable.
Can a surviving spouse keep a home with an outstanding HELOC?
In some circumstances, yes. The outcome depends on property ownership, the HELOC agreement, whether the spouse is a co-borrower, and applicable law. The spouse should contact the servicer and establish their legal status before making decisions about the property.
Can the lender foreclose after the borrower dies?
The borrower's death does not by itself answer whether foreclosure is permitted. If the secured debt is in default or another legally sufficient basis exists, the lender may have enforcement rights subject to the contract and applicable law. Families should seek prompt legal advice if they receive a foreclosure notice.
Can an heir use the deceased borrower's unused HELOC credit?
Heirs should not assume that unused credit remains available to them. The right to draw on a HELOC depends on the credit agreement and lender's applicable procedures. Contact the lender to confirm the account's status and whether any further advances are permitted.
Conclusion
When a HELOC borrower dies, the outstanding balance generally does not disappear, but the death also does not automatically make every heir personally responsible for the debt. The outcome depends on the credit agreement, surviving borrowers, property ownership, estate administration, and applicable law.
Families should begin by identifying the borrower or borrowers, confirming the property's ownership, obtaining current HELOC information, and communicating with the lender or servicer. They should also distinguish between personal responsibility for the debt and the lender's rights against the property securing it.
Depending on the circumstances, the family may be able to retain the property, arrange repayment, refinance, or sell the home. Because inheritance rules and creditor rights vary, qualified legal advice is particularly important when ownership, liability, or repayment deadlines are disputed.
Taking these steps early can help surviving family members understand their options, manage the estate responsibly, and make decisions based on the actual legal and financial position rather than assumptions about what happens to a HELOC after death.
0 comments
Log in to leave a comment.
Be the first to comment.