
Workplace Safety Risk Management: How Protective Equipment and Insurance Work Together
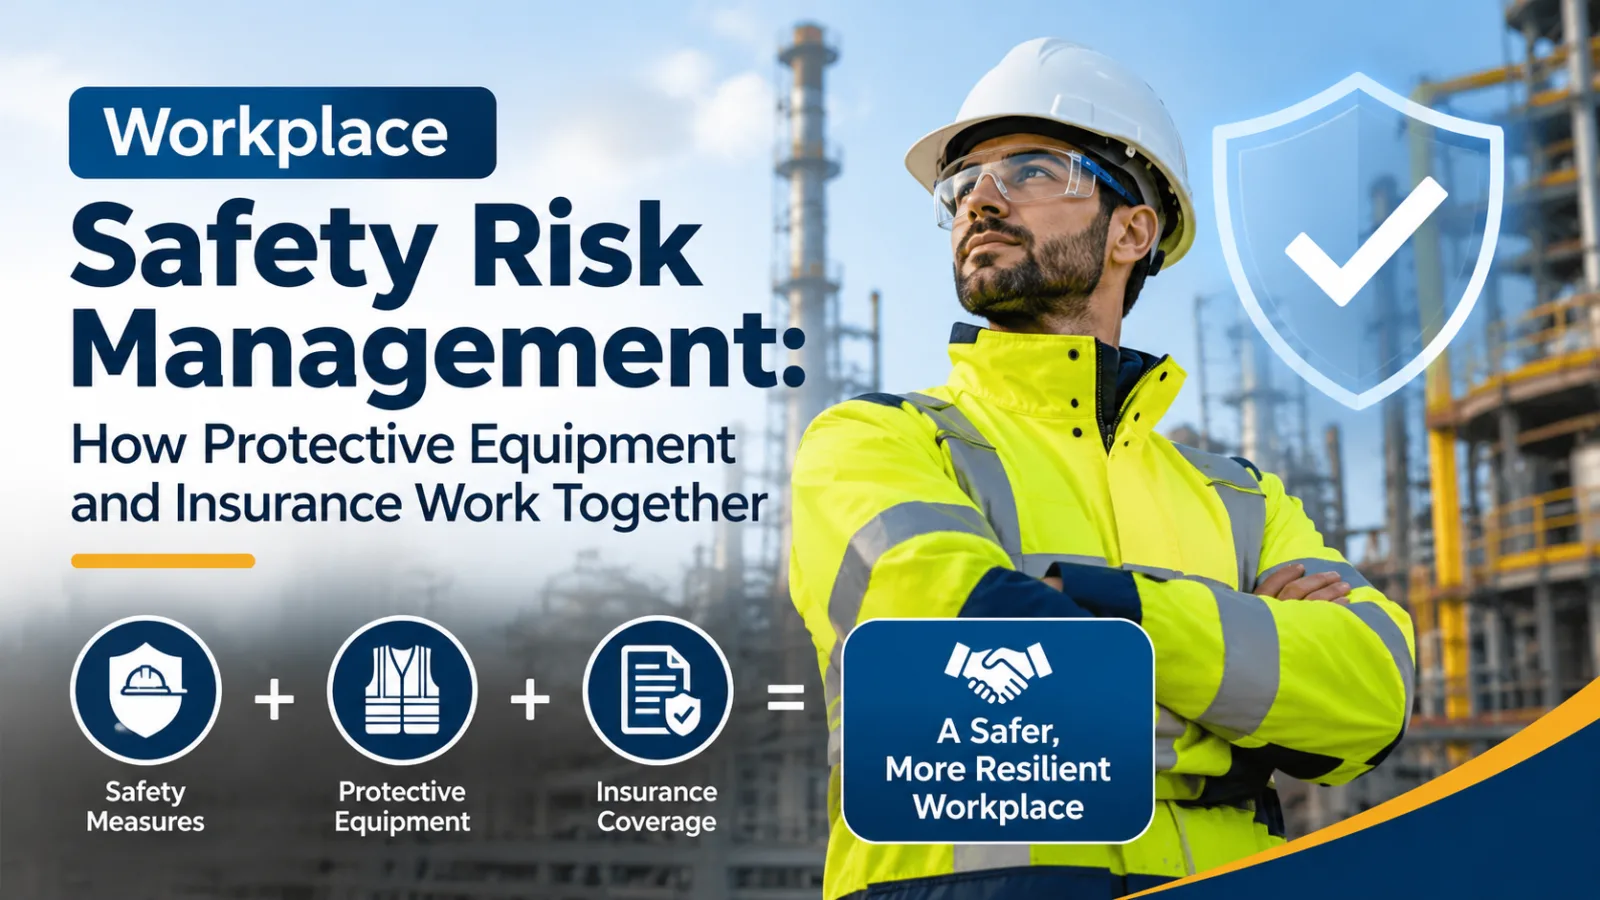
Workplace safety is an essential part of running a successful business, particularly in industries where employees face physical hazards every day. Manufacturing facilities, construction sites, oil and gas operations, and chemical plants all involve risks that can affect employee health, business continuity, and financial stability. Effective workplace safety risk management helps organizations identify potential dangers, reduce workplace incidents, and create safer working environments.
While safety training and operational procedures are important, businesses must also consider protective equipment, insurance coverage, and proper risk assessment. Combining these elements creates a more comprehensive approach to workplace protection.
Understanding Workplace Safety Risk Management
Workplace safety risk management is the process of identifying workplace hazards, evaluating their potential impact, and implementing measures to control or minimize risks. It involves more than responding to accidents after they happen. Businesses need to develop preventive strategies that address potential problems before they result in injuries or financial losses.
Common workplace hazards include:
Fire and electrical risks in industrial facilities.
Chemical exposure in manufacturing and processing plants.
Slips, trips, and falls in warehouses and construction areas.
Moving machinery and heavy equipment.
Poor visibility in roadwork, transportation, and outdoor operations.
Inadequate protective clothing and personal protective equipment.
Identifying these risks allows employers to establish appropriate safety procedures and allocate resources where they are most needed.
Why Personal Protective Equipment Matters
Personal protective equipment (PPE) plays a significant role in reducing employee exposure to workplace hazards. Depending on the working environment, PPE may include safety helmets, gloves, protective footwear, eye protection, respiratory equipment, and specialized workwear.
In high-risk industrial environments, protective clothing is particularly important. Employees working around heat, flames, electrical equipment, or moving vehicles require garments designed for their specific working conditions.
For example, flame-resistant clothing helps reduce the severity of injuries associated with accidental flame exposure, while high-visibility garments improve worker visibility in low-light conditions and areas with moving vehicles.
Businesses should select PPE based on workplace hazard assessments rather than choosing equipment solely on price or appearance. The equipment must meet applicable safety standards and be suitable for the tasks employees perform.
The Importance of High-Visibility and Flame-Resistant Clothing
Some industrial environments present multiple hazards simultaneously. Workers at oil and gas facilities, construction projects, utility sites, and transportation operations may need protection against both fire-related hazards and poor visibility.
High-visibility flame-resistant clothing combines two important protective features. Its reflective elements and fluorescent materials help workers remain visible, while its flame-resistant properties provide protection against specific thermal hazards.
However, employers should understand that not every high-visibility garment provides flame resistance, and not every flame-resistant garment meets high-visibility requirements. Both properties should be verified separately through appropriate certifications and product documentation.
Organizations sourcing specialized protective garments should evaluate fabric performance, reflective material quality, garment construction, comfort, and compliance requirements.
Businesses looking for suitable protective apparel can explore this guide to choosing a high visibility flame resistant clothing supplier to understand important considerations when selecting industrial safety workwear.
How Insurance Supports Workplace Risk Management
Even organizations with strong safety programs cannot eliminate every workplace risk. Unexpected incidents, equipment failures, employee injuries, and property damage can still occur. This is where appropriate insurance coverage becomes an important part of business risk management.
Commercial insurance policies help businesses manage the financial consequences of covered incidents. Depending on the organization and its operations, relevant coverage may include:
Workers' Compensation Insurance: Helps cover eligible employee medical expenses and wage replacement arising from work-related injuries or illnesses, subject to policy terms and applicable laws.
General Liability Insurance: Provides protection against certain third-party bodily injury and property damage claims.
Commercial Property Insurance: Helps businesses manage covered losses involving buildings, machinery, inventory, and other business property.
Business Interruption Insurance: Can help cover certain income losses and continuing operating expenses when a covered event disrupts business operations.
Insurance requirements vary by industry, location, and business structure. Organizations should work with qualified insurance professionals to determine which policies and coverage limits are appropriate.
The Role of Risk Assessment in Insurance Operations
Risk assessment connects workplace safety practices with insurance decisions. Insurers need reliable information about an organization's operations, workplace hazards, safety procedures, and potential exposure to determine appropriate underwriting approaches.
A structured risk assessment generally involves several steps:
Identify potential hazards: Review workplace activities, equipment, materials, and operating conditions.
Evaluate exposure: Determine how frequently employees may encounter hazards and the possible severity of resulting incidents.
Review existing controls: Examine safety training, protective equipment, maintenance schedules, and emergency procedures.
Determine risk levels: Assess the likelihood and potential consequences of different incidents.
Recommend improvements: Identify practical measures that can reduce exposure and strengthen workplace safety.
Monitor performance: Regularly review incidents, claims, and corrective actions to identify areas requiring improvement.
Accurate documentation makes this process more effective. It also helps insurers and businesses maintain consistent records for underwriting, compliance, and future risk reviews.
How Insurance Technology Improves Claims and Risk Management
Technology is transforming how insurance companies manage underwriting, claims processing, and operational risk. Digital workflows, automation, and structured data validation help insurance teams handle information more efficiently.
For example, when a workplace incident results in an insurance claim, the claims team may need to review incident reports, medical documents, policy information, supporting evidence, and coverage conditions.
Organized digital processes can help teams:
Register claims and track their progress.
Verify policy details and supporting documents.
Identify missing or inconsistent information.
Apply standardized review procedures.
Maintain accurate records for audits.
Monitor turnaround times and processing quality.
Technology does not replace professional judgment. Instead, it supports insurance specialists by reducing repetitive administrative work and helping them focus on accurate case evaluation.
Techsurance supports insurers, managing general agents (MGAs), and third-party administrators (TPAs) through insurance-focused services, including underwriting support, claims processing, risk assessment, and policy administration. Its structured workflows and quality checks help insurance businesses manage operational requirements more efficiently.
Building a Stronger Workplace Safety Strategy
An effective workplace safety program requires continuous attention rather than a one-time assessment. Businesses should regularly review their procedures, equipment, and employee training to ensure that safety measures remain relevant as operations change.
Here are some practical steps organizations can follow:
Conduct Regular Workplace Inspections: Inspect machinery, electrical systems, storage areas, and employee workspaces to identify potential hazards.
Provide Employee Training: Workers should understand workplace risks, emergency procedures, and the correct use of protective equipment.
Choose Appropriate Safety Clothing: Select garments according to specific hazards, industry standards, and working conditions.
Maintain PPE Properly: Inspect protective equipment regularly and replace damaged or worn items according to manufacturer recommendations.
Review Insurance Coverage: Ensure that insurance policies reflect current business operations, employee exposure, and potential financial risks.
Maintain Accurate Documentation: Record workplace incidents, safety inspections, employee training, and corrective actions to support ongoing risk management.
Conclusion
Workplace safety and insurance risk management are closely connected. Protective equipment helps reduce employee exposure to hazards, while insurance provides financial protection against certain unexpected losses. Risk assessments, proper documentation, and technology-supported insurance processes further strengthen this approach.
Businesses that combine preventive safety measures with appropriate insurance planning can improve operational resilience and create more secure working environments. With the support of specialized protective clothing manufacturers such as Armstrong Products and insurance operations partners such as Techsurance, organizations can take a more structured approach to workplace protection and risk management.
0 comments
Log in to leave a comment.
Be the first to comment.