
Why High-Risk Merchant Service Providers Are Essential for Businesses With High Chargeback Rates
high risk merchant account providers
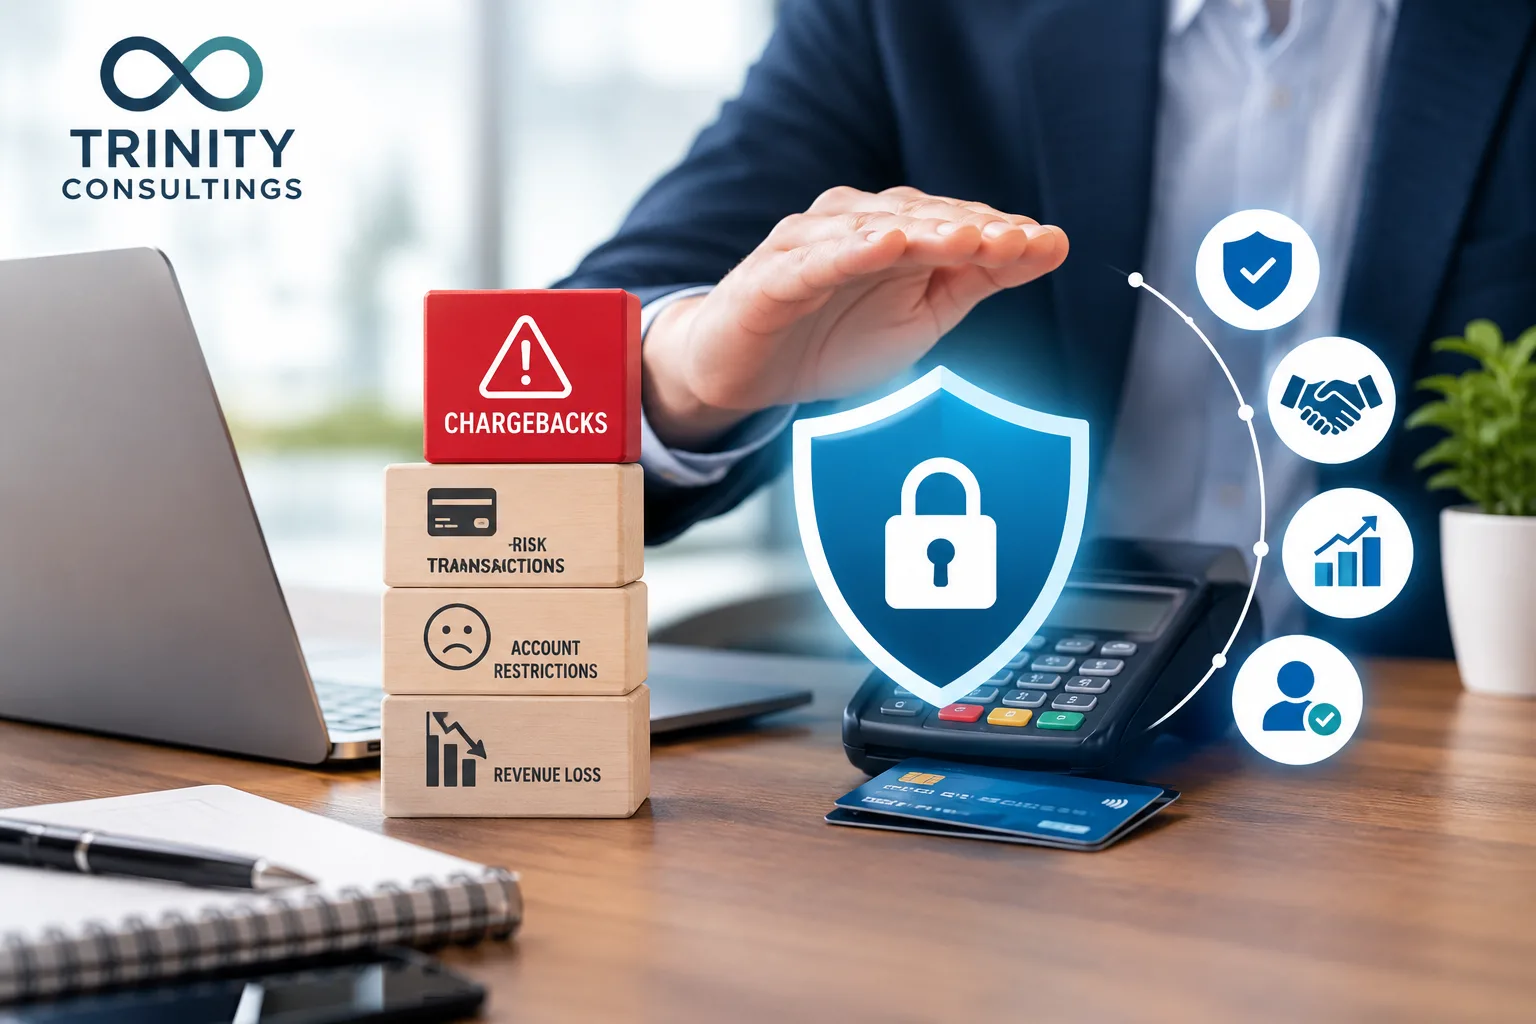
Businesses with frequent chargebacks often face payment processing challenges that traditional merchant account providers may struggle to accommodate. A high chargeback rate can lead to higher processing fees, account restrictions, delayed settlements, or account termination. For businesses that rely on online transactions, these issues can interrupt revenue and make daily operations difficult.
This is where high risk merchant account providers become important. They work with businesses that face elevated payment risks, offering specialized processing arrangements designed to accommodate their transaction patterns while helping merchants manage disputes and maintain reliable payment operations.
Why High Chargeback Rates Create Payment Processing Problems
A chargeback occurs when a customer disputes a transaction through their card issuer. The issuer reviews the dispute, and the transaction may be reversed if the claim is upheld. Although chargebacks can result from genuine fraud, they can also arise from billing confusion, delayed deliveries, subscription misunderstandings, or dissatisfied customers.
When disputes become frequent, payment processors may view the business as a greater financial risk. This can affect the company's ability to secure or maintain a merchant account.
Common causes of high chargeback rates include:
Fraudulent transactions: Stolen card details or unauthorized purchases can generate disputes.
Unclear billing descriptors: Customers may not recognize a charge on their statements.
Subscription confusion: Recurring payments can lead to disputes when cancellation terms are unclear.
Fulfillment problems: Late deliveries, missing orders, or inconsistent service can prompt customers to request chargebacks.
Poor customer support: Customers who cannot resolve issues directly may turn to their banks.
Identifying the main cause is essential because choosing a payment provider alone will not eliminate the underlying problem.
How High-Risk Merchant Account Providers Support Businesses
High-risk merchant account providers specialize in businesses that may not meet the standard risk criteria used by conventional processors. Depending on their underwriting policies, they may consider merchants with elevated dispute rates, unusual transaction patterns, or business models associated with increased financial exposure.
Their support may include the following:
Access to merchant accounts designed for eligible high-risk businesses.
Payment processing arrangements that reflect the merchant's risk profile.
Fraud detection and transaction monitoring tools.
Dispute alerts and chargeback management features.
Guidance on processing limits, reserves, and settlement terms.
Approval is not guaranteed, and merchants may face higher fees, reserve requirements, or additional documentation. However, a suitable provider can offer a practical option for businesses that struggle to secure traditional processing services.
Key Benefits of High-Risk Credit Card Processing
High risk credit card processing allows eligible businesses to accept card payments under terms designed around their risk profile. The value depends on the provider's features, the merchant's transaction history, and how effectively the business manages disputes.
1. Access to Specialized Merchant Accounts
A business experiencing repeated chargebacks may find it difficult to obtain approval through a traditional provider. A specialized provider can assess the company's industry, processing history, average transaction value, refund practices, and dispute patterns to determine whether it qualifies for a high risk merchant account.
Merchants can prepare for the application process by gathering:
Business registration and ownership documents.
Recent processing statements, if available.
Chargeback and refund history.
Product or service descriptions.
Website terms, privacy policies, and refund policies.
Expected monthly processing volume and average transaction value.
Providing accurate information helps the provider evaluate the business and identify suitable account terms.
2. Better Fraud Prevention Opportunities
Some high-risk payment processing arrangements include tools that help identify suspicious transactions before payment is completed or an order is fulfilled.
Useful features may include:
Address verification and card security code checks.
3-D Secure authentication where supported.
Automated transaction screening.
Unusual purchase pattern detection.
Manual review options for suspicious orders.
For example, an online retailer receiving multiple high-value orders from unusual locations may use additional verification before shipping. This can help limit fraudulent transactions, although aggressive screening may also decline legitimate purchases.
3. Support for Managing Chargeback Exposure
Some providers offer dispute alerts that notify merchants about eligible transactions before a dispute becomes a formal chargeback. This can give a business an opportunity to issue a refund or resolve the customer's concern when appropriate.
Merchants should also:
Respond promptly to customer complaints.
Keep order confirmations and delivery records.
Maintain evidence of customer authorization.
Submit relevant documentation when challenging invalid disputes.
Review recurring dispute reasons and correct the underlying issues.
These steps can strengthen chargeback management, although they cannot guarantee that every dispute will be prevented or won.
What to Compare Before Choosing a Provider
Not every provider handles high chargeback rates in the same way. Before opening an account, evaluate the complete agreement rather than focusing only on transaction fees.
Important factors to compare include:
Processing fees: Review transaction rates, monthly charges, setup fees, and chargeback fees.
Reserve requirements: Ask whether funds will be withheld, how reserves are calculated, and when they are released.
Settlement schedules: Confirm expected payout timelines and the conditions that may delay payments.
Fraud prevention features: Determine which security and monitoring tools are included.
Industry restrictions: Confirm that the provider accepts your particular products, services, and business model.
Processing limits: Understand any daily, monthly, or per-transaction restrictions.
Customer support: Check how account reviews, payment issues, and disputes are handled.
A provider that approves an account but imposes unsuitable reserve terms or restrictive processing limits may still create cash-flow problems. Always review the merchant agreement carefully.
Practical Ways to Reduce Chargebacks After Approval
Securing a high risk merchant account is only one part of the solution. Businesses must also address the factors that cause disputes.
Start by reviewing chargeback records to identify recurring patterns, such as particular products, transaction channels, delivery delays, or subscription complaints.
Practical measures include:
Improve billing transparency: Use recognizable billing descriptors and explain recurring charges clearly.
Simplify refunds and cancellations: Make policies easy to find and follow.
Improve order fulfillment: Provide realistic delivery estimates and tracking information.
Strengthen transaction security: Apply suitable verification and fraud screening.
Keep accurate records: Retain receipts, customer communications, and delivery confirmations.
Monitor dispute trends: Investigate sudden increases and take corrective action early.
Train customer support staff: Help employees resolve billing concerns before they escalate.
Regular monitoring is essential because the appropriate dispute thresholds and potential consequences depend on the payment provider, card network, and merchant's circumstances.
Build a More Sustainable Payment Processing Strategy
High chargeback rates can make payment acceptance more complicated, but they do not automatically mean a business must stop accepting card payments. The right provider can offer specialized processing arrangements, while effective fraud controls and customer service practices help address the reasons disputes occur.
Before making a decision, businesses should compare providers based on their actual risk profile, contract terms, reserve policies, processing limits, and dispute management tools. The goal is to establish a payment arrangement that supports day-to-day operations while encouraging better transaction practices.
Looking for guidance on high-risk payment processing? Visit Trinity Consultings to explore relevant payment processing information and identify important questions to ask when evaluating options for your business.
0 comments
Log in to leave a comment.
Be the first to comment.