
What Is the Process of Converting Real-World Assets Into Digital Tokens?
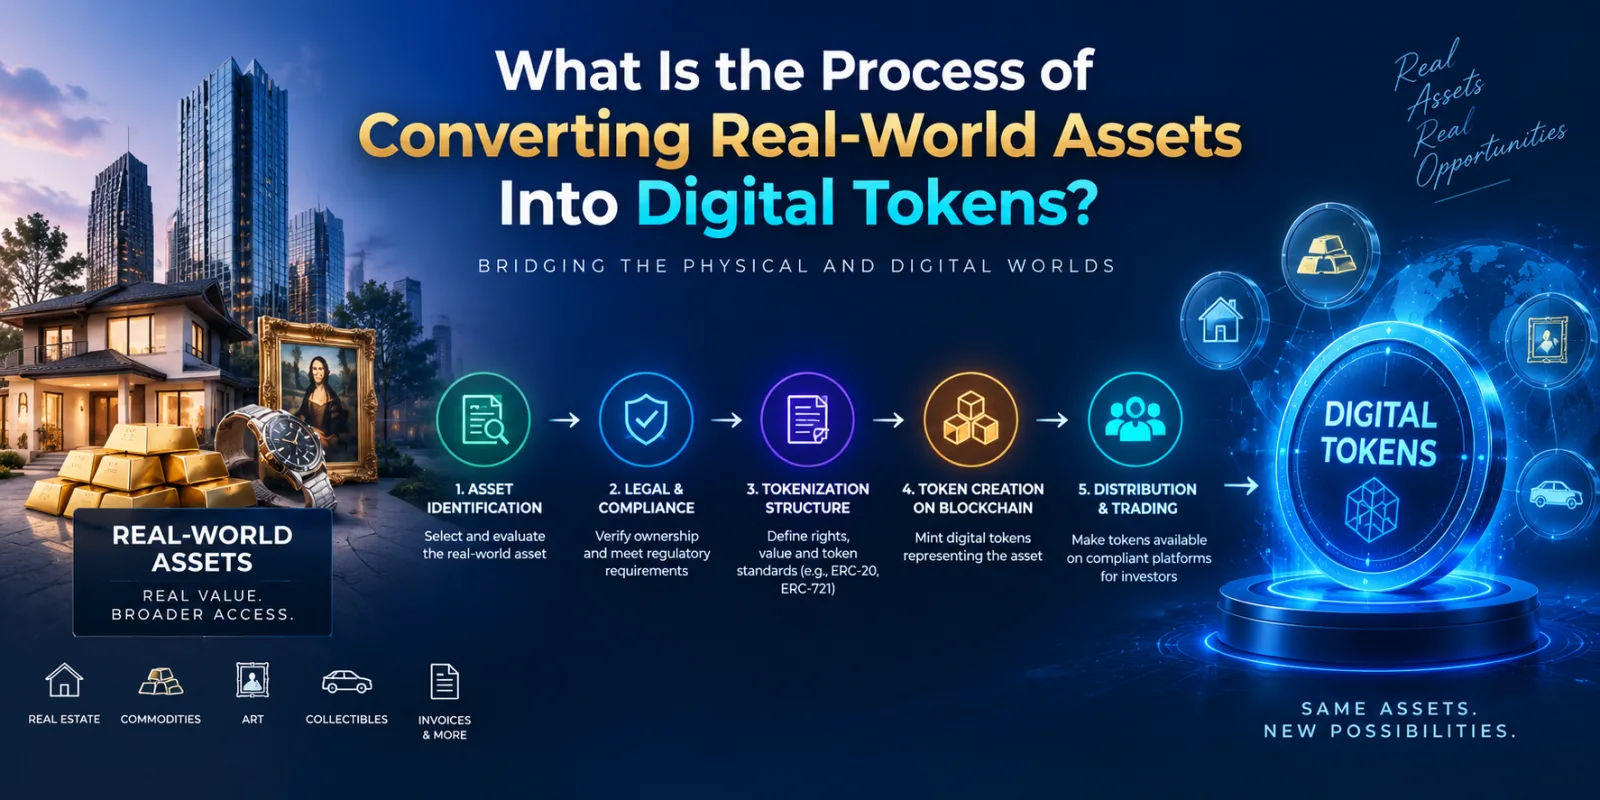
Real-world asset tokenization is changing how physical and traditional financial assets can be owned, transferred, financed, and managed. At its simplest, tokenization means creating a digital representation of an asset or a legal claim on an asset and recording that representation on a blockchain or another distributed ledger. The underlying asset can be real estate, bonds, commodities, private equity, artwork, infrastructure, investment funds, or other assets with identifiable ownership rights.
The important point, however, is that tokenization is not simply the process of creating a cryptocurrency and attaching an asset's name to it. A successful tokenization model must connect the digital token to enforceable rights in the real world. That requires asset verification, legal structuring, valuation, custody, smart-contract development, investor compliance, issuance, and ongoing administration.
The Bank for International Settlements describes tokenization as the process of recording claims on real or financial assets on a programmable platform. It highlights the possibility of integrating information, rules, and transaction logic into the same digital environment.
As institutional adoption develops, tokenization is moving beyond experimentation. For example, BlackRock's USD Institutional Digital Liquidity Fund, known as BUIDL and tokenized by Securitize, surpassed $1 billion in assets under management in March 2025. The fund subsequently expanded across additional blockchain networks, demonstrating how tokenized financial products can become part of broader digital-market infrastructure.
What Does Real-World Asset Tokenization Actually Mean?
Before examining the process, it is important to distinguish the asset from its token.
Suppose a commercial property is valued at $10 million. Instead of relying exclusively on traditional ownership records and investment structures, a legally structured entity could issue 10 million digital tokens representing defined economic or ownership interests. An investor purchasing 10,000 tokens would therefore obtain the rights specified in the legal documents governing those tokens.
The blockchain does not magically transfer ownership of the physical building. Instead, the token must be legally connected to the underlying asset or to an entity that owns or controls the asset. Depending on the structure, the token may represent direct ownership, shares in a special-purpose vehicle, a beneficial interest, debt, revenue rights, or another contractual claim.
This distinction is crucial. In January 2026, the U.S. Securities and Exchange Commission stated that a tokenized security is still a security when it falls within the relevant securities definition, even though ownership records are maintained partly or entirely through a crypto network.
Therefore, tokenization should be viewed as a combination of legal structuring, financial engineering, asset administration, and blockchain technology, rather than simply a technical exercise.
Step 1: Select and Assess the Real-World Asset
The first stage is identifying an asset that is suitable for tokenization.
Not every asset is equally practical. A suitable asset should have clearly identifiable ownership, reliable documentation, measurable value, and a defined legal framework. Real estate is particularly interesting because individual properties are expensive and traditionally illiquid, making fractional investment potentially valuable.
Other possible assets include:
- Commercial and residential real estate
- Government and corporate bonds
- Private equity interests
- Commodities
- Infrastructure projects
- Art and collectibles
- Investment funds
- Intellectual-property-related rights
- Equipment and other productive assets
Due diligence is performed before tokens are created. For property, this may involve examining title records, mortgages, liens, leases, tax obligations, insurance, property condition, and financial statements.
This stage protects the tokenization platform from creating a digital representation of an asset whose ownership or value is uncertain. The blockchain can provide an immutable transaction record, but it cannot independently verify whether the physical asset actually exists or whether the issuer legally owns it.
That is why the quality of off-chain verification is just as important as the quality of blockchain infrastructure.
Step 2: Establish the Legal and Ownership Structure
Legal structuring is arguably the most important part of the tokenization process.
The issuer must determine what the token represents and what rights the token holder receives. A common approach is to place an asset into a special-purpose vehicle (SPV) and issue tokens representing shares or beneficial interests associated with that entity.
For example, a property worth $5 million could be held by an SPV. The SPV could issue a defined number of compliant digital securities representing economic interests in the entity. Investors then purchase tokens according to the applicable offering rules.
The legal framework should establish matters such as:
- Ownership rights
- Voting rights
- Revenue or rental-income rights
- Redemption mechanisms
- Transfer restrictions
- Investor eligibility
- Custody arrangements
- Dispute resolution
- Tax responsibilities
- Compliance requirements
The exact structure varies considerably by jurisdiction and asset class. The SEC has emphasized that tokenization does not remove existing securities-law obligations. It has also noted that tokenized securities can be structured in different ways, with potentially different rights for token holders.
Consequently, legal counsel and compliance specialists should be involved before the technical issuance begins.
Step 3: Verify and Value the Asset
After the legal structure is established, the asset needs to be independently verified and valued.
For real estate, valuation can involve professional appraisals, comparable-property analysis, rental income, occupancy rates, operating expenses, location, development potential, and existing liabilities. For bonds or funds, valuation may rely on market prices, underlying securities, credit characteristics, and audited financial information.
The valuation process determines how many tokens should be issued and what each token represents.
Imagine an office building valued at $20 million. If the structure creates 20 million tokens, each token could initially correspond to $1 of economic value, subject to the legal and financial terms of the offering. The token price, however, should not be assumed to remain fixed because the value of the underlying asset can change.
This is one reason transparent reporting and independent asset verification remain essential after issuance.
Step 4: Design the Token Model
The next stage is deciding how the digital token will function.
Token design goes beyond choosing a blockchain and creating a token contract. Developers and financial specialists need to define the token's supply, transferability, investor restrictions, rights, lifecycle, and interaction with other systems.
A token may be:
- Fungible, where every unit represents an equivalent interest.
- Non-fungible, where each token represents a unique asset or position.
- Fractionalized, allowing investors to hold smaller economic interests.
- Permissioned, restricting transfers to verified participants.
- Programmable, allowing rules to be automatically enforced through smart contracts.
For regulated assets, permissioned transfer mechanisms can be particularly important. Smart contracts can prevent transfers to unauthorized wallets, enforce holding restrictions, record ownership changes, and automate certain compliance processes.
The SEC's 2026 statement specifically recognizes models in which distributed-ledger records can function as the master record of ownership, provided the relevant legal requirements are satisfied.
Step 5: Choose the Blockchain Infrastructure
Once the token model is established, the project team selects an appropriate blockchain network.
The choice should be based on technical and business requirements rather than popularity alone. Important considerations include transaction costs, throughput, security, ecosystem maturity, interoperability, smart-contract capabilities, wallet support, privacy requirements, and regulatory needs.
A tokenization platform may use a public blockchain, private blockchain, or permissioned network depending on the asset and target investors.
For institutional products, interoperability can also become important. BUIDL, for instance, expanded beyond Ethereum to additional networks including Solana and others, illustrating how tokenized assets can eventually operate across multiple blockchain environments.
The blockchain is essentially the digital infrastructure, but it should be treated as one component of a broader tokenization ecosystem.
Step 6: Develop and Audit Smart Contracts
Smart contracts provide the programmable rules behind the token.
A tokenization smart contract can manage issuance, transfers, ownership records, compliance restrictions, distributions, redemptions, and other lifecycle events. For example, a real estate token could be programmed so that only verified wallets can receive it.
Smart contracts are particularly valuable because they can automate processes that traditionally require several intermediaries. The BIS has highlighted how tokenization can combine asset information with rules governing transfers and enable programmable transaction processes, including delivery-versus-payment mechanisms.
However, automation also creates technical risk. A coding error could result in unauthorized transfers, incorrect distributions, or loss of funds. Therefore, smart contracts should undergo comprehensive security audits before deployment.
Testing should cover normal transactions as well as edge cases, failed transactions, administrative permissions, upgrade mechanisms, access controls, and potential attack vectors.
Step 7: Connect the Blockchain With Real-World Data
A tokenized asset cannot operate entirely inside the blockchain because much of the information needed to determine its value and status exists off-chain.
This is where oracles, data providers, custodians, property managers, financial institutions, valuation firms, and other external systems can become important.
For example, a tokenized rental property may need verified information about rental income, occupancy, expenses, property valuation, or ownership status. Reliable data feeds can communicate relevant information to blockchain applications.
This creates one of tokenization's central challenges: the blockchain can make digital records highly transparent and tamper-resistant, but it cannot independently guarantee that external information is truthful.
Strong governance and independent verification therefore remain essential.
Step 8: Mint and Issue the Tokens
After legal, financial, technical, and compliance requirements have been completed, the tokens can be minted.
Minting creates the digital assets according to the predefined token model. The issuer then distributes them through an approved platform, marketplace, investment portal, or other channel.
Investor onboarding commonly includes identity verification, know-your-customer procedures, anti-money-laundering screening, eligibility checks, and acceptance of relevant legal agreements.
For regulated tokenized securities, transfer restrictions can be embedded into the infrastructure so that transactions occur only between eligible participants.
The objective is not simply to make an asset tradable. The objective is to create a compliant digital market in which ownership and transfer rules are consistently enforced.
Step 9: Enable Trading, Settlement, and Asset Management
Tokenization becomes significantly more valuable when tokens can participate in an efficient secondary market.
Once legally permitted, tokenized assets can potentially be transferred between eligible investors without relying on the same sequence of manual processes used in conventional markets. Smart contracts can automate certain settlement activities, while blockchain records can provide a shared view of ownership.
The BIS has identified faster settlement, reduced reconciliation requirements, and programmable transactions as important potential advantages of tokenization.
However, tokenization does not automatically create liquidity. There must be sufficient buyers and sellers, suitable trading infrastructure, clear regulations, reliable valuation mechanisms, and appropriate market-making or redemption arrangements.
Research published by the BIS on tokenized real estate found evidence that tokenization can improve liquidity under certain conditions, but also noted that buyback mechanisms associated with increased liquidity can introduce additional insolvency risks.
This demonstrates why tokenization should not be marketed as a guaranteed solution to illiquidity.
A Real-World Example: BlackRock's BUIDL
BlackRock's BUIDL provides a useful example of how institutional tokenization can work.
Launched in March 2024 and tokenized by Securitize, BUIDL is a tokenized fund that provides eligible investors with exposure to U.S. dollar-denominated assets through blockchain-based fund shares. Securitize announced in March 2025 that the fund had exceeded $1 billion in assets under management.
The example demonstrates an important characteristic of institutional tokenization: the blockchain component is integrated with established financial structures rather than replacing them entirely.
The tokenized representation can provide new capabilities such as near-real-time transfers and integration with blockchain-based financial applications, while the underlying fund structure, compliance processes, asset management, and legal framework continue to matter.
Key Benefits of Converting Real-World Assets Into Tokens
The potential benefits extend beyond fractional ownership.
Fractional access: Expensive assets can potentially be divided into smaller investment units, lowering the capital required to obtain exposure.
Greater transparency: Blockchain-based records can provide a shared and auditable history of transactions and ownership.
Programmability: Smart contracts can automate distributions, transfers, compliance rules, and settlement processes.
Operational efficiency: Tokenization can reduce manual reconciliation and connect multiple transaction functions within a programmable environment.
Broader market access: Depending on regulation and infrastructure, tokenized assets can potentially reach investors across geographical boundaries.
Collateral utility: Tokenized assets may eventually be used more efficiently as collateral within digital financial markets.
The BIS and other financial institutions emphasize these potential benefits while also warning that many advantages depend on regulatory, technological, governance, and market infrastructure developing alongside tokenization.
Major Challenges to Consider
The most difficult part of tokenization is often not blockchain development. It is creating a reliable connection between the token and the legal, financial, and physical reality it represents.
Regulatory uncertainty remains a major consideration because tokenized assets can fall under securities, property, financial-services, tax, and other laws. Different jurisdictions can impose very different requirements.
There are also custody risks, smart-contract vulnerabilities, oracle and data-quality risks, valuation challenges, cybersecurity concerns, investor-protection requirements, and liquidity limitations.
Another major issue is interoperability. If tokenized assets exist on isolated blockchain networks, their usefulness can be restricted. Institutional adoption therefore increasingly depends on infrastructure that can connect different networks and traditional financial systems.
The BIS has characterized tokenization as a continuum in which some applications are relatively straightforward while others involve significantly greater legal and governance challenges.
The Future of Real-World Asset Tokenization
Real-world asset tokenization is gradually evolving from a conceptual blockchain application into a broader financial-market infrastructure.
The most promising future is unlikely to involve simply putting every physical asset on a blockchain. Instead, successful tokenization will combine legally enforceable ownership structures, reliable asset data, compliant investor onboarding, secure smart contracts, efficient settlement, and accessible secondary markets.
Real estate is particularly relevant because tokenization can address some of the traditional barriers associated with high investment minimums and illiquidity. At the same time, financial assets such as funds, bonds, and private-market instruments may benefit from programmable settlement and improved operational efficiency.
As institutional adoption grows, the distinction between traditional finance and blockchain-based finance may become less pronounced. Tokenization could ultimately become another layer of financial infrastructure rather than a separate category of investment technology.
Conclusion
Converting real-world assets into digital tokens is a multi-stage process that combines asset due diligence, legal structuring, valuation, token design, blockchain selection, smart-contract development, compliance, issuance, and ongoing asset management. The technology provides powerful capabilities for fractionalization, transparency, programmability, and potentially more efficient settlement, but the success of a tokenized asset ultimately depends on whether its digital representation is securely and legally connected to the underlying asset. Businesses planning to enter this market therefore need experienced blockchain developers, smart-contract specialists, compliance expertise, and carefully designed tokenization infrastructure. For organizations looking to build such solutions, Blockchain App Factory provides best services for real-world asset tokenization, including [Property tokenization development services] and [Real estate asset tokenization services], with a focus on building secure, scalable, and business-oriented tokenization platforms.
FAQs
1. What Is Real-World Asset Tokenization?
Real-world asset tokenization is the process of creating blockchain-based digital tokens that represent ownership, economic rights, or another legally defined claim associated with a physical or traditional financial asset.
2. Can Any Real-World Asset Be Tokenized?
Technically, many asset types can be represented digitally, but practical tokenization depends on ownership rights, legal enforceability, valuation, regulation, custody, and market demand.
3. How Does Real Estate Tokenization Work?
Real estate can be placed under an appropriate legal structure, such as an SPV, after which digital tokens can represent defined ownership or economic interests. Smart contracts can manage issuance and eligible transfers.
4. Does Tokenization Make an Asset Automatically Liquid?
No. Tokenization can make transfers more efficient and enable fractional ownership, but meaningful liquidity requires buyers, sellers, compliant marketplaces, reliable valuations, and suitable redemption or trading mechanisms.
5. Why Are Smart Contracts Important in RWA Tokenization?
Smart contracts can automate token issuance, transfers, compliance restrictions, distributions, and other transactions while maintaining blockchain-based records. They should be thoroughly audited before deployment because coding vulnerabilities can create significant financial risks.
0 comments
Log in to leave a comment.
Be the first to comment.