
Understanding Single Property Valuation and When You Need One
Not every valuation job involves a whole portfolio or a lawsuit. Sometimes someone just needs one property looked at properly, for one specific reason.
That one number can carry a lot of weight, more than people expect going in. It might decide how much insurance overage a home needs. It might settle how an estate gets split between siblings who don't agree on much else. Or it might tell a buyer whether the asking price makes sense before they sign anything.
The stakes shift depending on the situation. So does what matters most in getting to that number. Knowing how this assessment works helps property owners figure out what to expect once the process starts.
What Counts as a Single Asset
Think of it as one asset getting its own standalone look. A house, an office building, a strip of retail space, a raw piece of land, doesn't matter. The goal is a single, current opinion of value for that one property, nothing bundled in with anything else.
Portfolio valuation is a different animal entirely. That's for institutional clients juggling a stack of properties at once. This isn't that.
Common Reasons People Request One
Purpose
Insurance coverage decisions
Estate planning or settlement
Pre-purchase due diligence
Refinancing
Partnership buyouts
Tax appeal support
Typical Client
Homeowners and business owners
Individuals and families
Buyers and investors
Homeowners and property owners
Co-owners of a shared asset
Property owners contesting assessments
Why someone needs the valuation usually decides which methodology carries the most weight in the final report.
From Inspection to Final Report
The path from first phone call to finished report usually breaks down into a few clear stages:
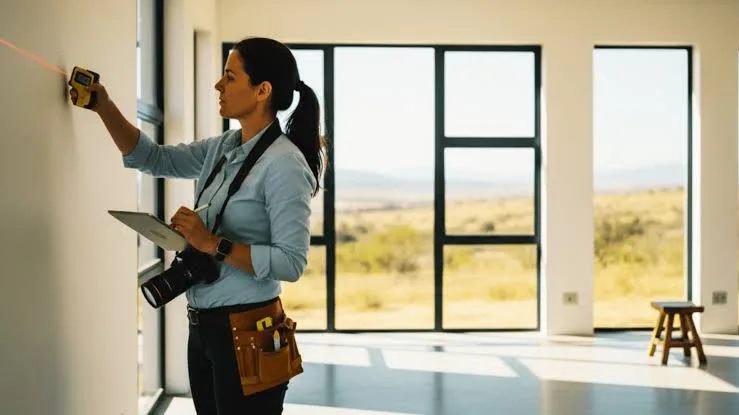
Walk the property. Condition, square footage, layout, whatever makes the place stand out gets documented on the spot.
Pull comparable sales. Recent transactions, current listings, and anything shifting in that property type or location get reviewed.
Analyze the findings. The appraiser weighs everything gathered against market conditions specific to that asset.
Write the report. Not just the number, but the reasoning behind it, laid out clearly enough to follow.
A report built that way holds up whether it's headed to an insurer, a lender, or just sitting in someone's files.
Homes, Offices, Land, and Everything Between
Plenty of asset types fall under this umbrella. A short list:
Single-family homes and condos
Multi-family buildings
Office and retail spaces
Industrial properties
Land and subdivision parcels
Special purpose properties, such as religious or medical facilities
Each one needs a different eye. Comparables that work for a rowhome don't work for a warehouse, and someone with experience across categories knows the difference.
Signs of a Report Worth Trusting
Good research is the whole ballgame here. A handful of traits separate a solid report from a weak one:
Comparables that are recent, not pulled from stale data
Adjustments spelled out clearly, not buried in jargon
No financial stake in how the final number lands
Documentation detailed enough to survive review
A methodology that matches accepted appraisal standards
Skip any of these and the report looks more like a guess than an opinion.
Finding a Firm That Specializes in Single Assets
Anyone searching for single property valuation in Columbia usually wants a practice built around this focused, one-asset work. That means serving private owners, lenders, developers, institutional clients, and attorneys who need one dependable number for one specific property.
The range matters too. Single properties, insurance valuation, mixed-use buildings, offices, retail, industrial, multifamily, hospitality, land, residential, special purpose. A firm covering that much ground brings an appraiser who actually knows the asset type in front of them.
Typical Turnaround Times
Depends on the property and why the valuation's needed. A basic residential job might wrap in a week. A special purpose property or a big commercial asset usually takes longer; there's more digging involved.
Got a deadline, a closing date, a court filing? Say so upfront. A good appraiser can work around it without cutting corners on accuracy.
Scheduling an Inspection
Anyone needing one property assessed- for insurance, a sale, an estate, a refinance- can reach out to a qualified local firm and get an inspection scheduled. Solid research behind the report is what makes it something a client can actually stand behind later.
0 comments
Log in to leave a comment.
Be the first to comment.