
The Indian Marketplace Stack Is Diverging From the Western One
AI-led commerce enablement
Global commerce software assumes a market shaped like the US: one dominant marketplace, consolidated retail media and planning on a weekly rhythm. India looks less like that every year. Brands and vendors that miss the difference will build for the wrong market.
For much of the last decade, Indian ecommerce followed a familiar pattern. Two large horizontal marketplaces, a set of vertical specialists, and a playbook borrowed largely from Amazon's home market. Tools built for US sellers worked well enough with some localization.
That is no longer true. The Indian stack has taken on its own shape, and the differences are structural rather than cosmetic.
Five Ways India Now Differs
1. Quick Commerce Is a Core Channel, Not an Experiment
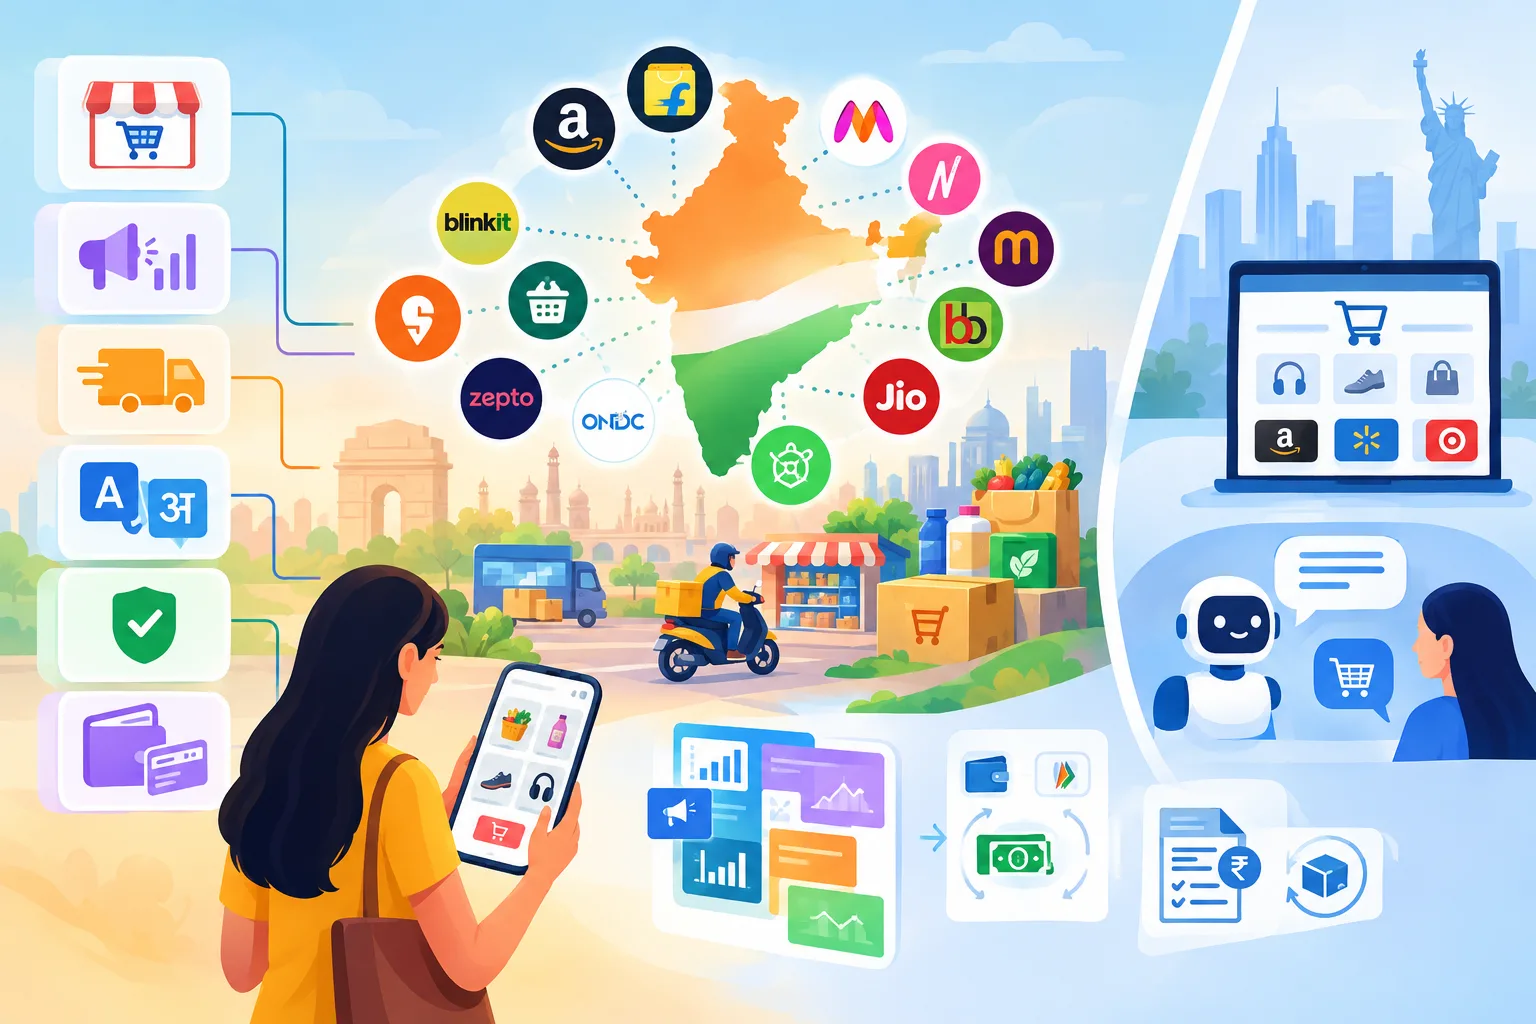
In the US and much of Europe, rapid delivery has mostly remained a niche or a feature of existing grocers. In India's large cities, dedicated quick commerce platforms such as Blinkit, Swiggy Instamart and Zepto, joined by rapid services from Flipkart and Amazon, have become central to how households buy groceries, personal care and a widening range of other categories. That brings dark store inventory, daily replenishment and hyperlocal demand into every brand's planning.
2. The Marketplace Map Is Fragmented
A US brand can reach most online shoppers through a small number of retailers. An Indian brand in beauty, food, or home may need to manage Amazon, Flipkart, Myntra, Nykaa, Meesho, BigBasket, JioMart, several quick commerce platforms, and its own D2C site. Each has different catalog rules, fee structures, ad systems, and reporting. ONDC adds an open network layer with its own logic on top.
3. Retail Media Is Spread Thin
Western retail media has consolidated around a few large networks. In India, nearly every marketplace and quick commerce platform runs its own ad business. Budgets are split across many consoles, each with its own formats, attribution windows and data access. Simply comparing performance across them is a problem in itself.
4. Language and Value Shape the Shopper Base
Much of the growth in online shoppers is coming from smaller cities and from people who prefer to browse in Indian languages. Value-focused platforms have built large businesses around price-sensitive buyers. Content, pricing and pack architecture have to work across very different shopper segments at the same time.
5. Compliance and Settlement Are Complex
Tax collected and deducted at source by marketplaces, a mix of payment modes that still includes cash on delivery in many segments, high return rates in categories such as fashion, and platform-specific settlement cycles all make reconciliation a larger share of the work than in markets with simpler flows.
The West Is Diverging Too, on a Different Path
The biggest shift in Western commerce is the rise of AI shopping assistants and the protocols behind them. OpenAI and Stripe's Agentic Commerce Protocol and Google's Universal Commerce Protocol are moving discovery and checkout into conversational interfaces. That tooling is being built around a relatively consolidated set of large retailers and a big independent D2C ecosystem.
India will feel that shift as well. But it will land on top of a stack that is already more fragmented, faster-moving, and more operationally intensive than the one it was designed for.
What This Means for Brands
If you run ecommerce for a brand in India, three implications follow.
Normalize before you analyze. Any intelligence layer has to translate data from many platforms into one model of price, availability, rank, ad performance, and settlements. Without that, every cross-platform decision is guesswork.
Plan at the channel grain. Quick commerce needs daily, dark store-level thinking. Marketplaces need SKU by region. D2C needs customer-level. One cadence does not fit all.
Automate the operational load. Fragmentation multiplies routine work: listings, price checks, bid changes, claims. This is where AI agents trained on commerce data earn their keep, because the volume is too high for manual teams to handle well.
What This Means for Vendors
For software companies, the lesson is to stop treating India as a localization project. Tools designed around a single dominant marketplace and a weekly cycle will struggle here. The winners will be built for fragmentation from the start, with deep coverage of Indian platforms and an operating model that assumes decisions happen daily.
Firms building AI-led commerce enablement for brands in India have learned this the hard way, because the same brand can face six different sets of rules before lunch.
A Market That Sets Its Own Standard
India's ecommerce stack was once a follower. Now it's an early example of what happens when channels multiply, delivery windows shrink, and retail media fragments. Some of what brands learn here will travel. For now, the lesson is simple: build for the market you are actually selling in.
0 comments
Log in to leave a comment.
Be the first to comment.