
The Beginner’s Guide to Multifamily Bridge Loans
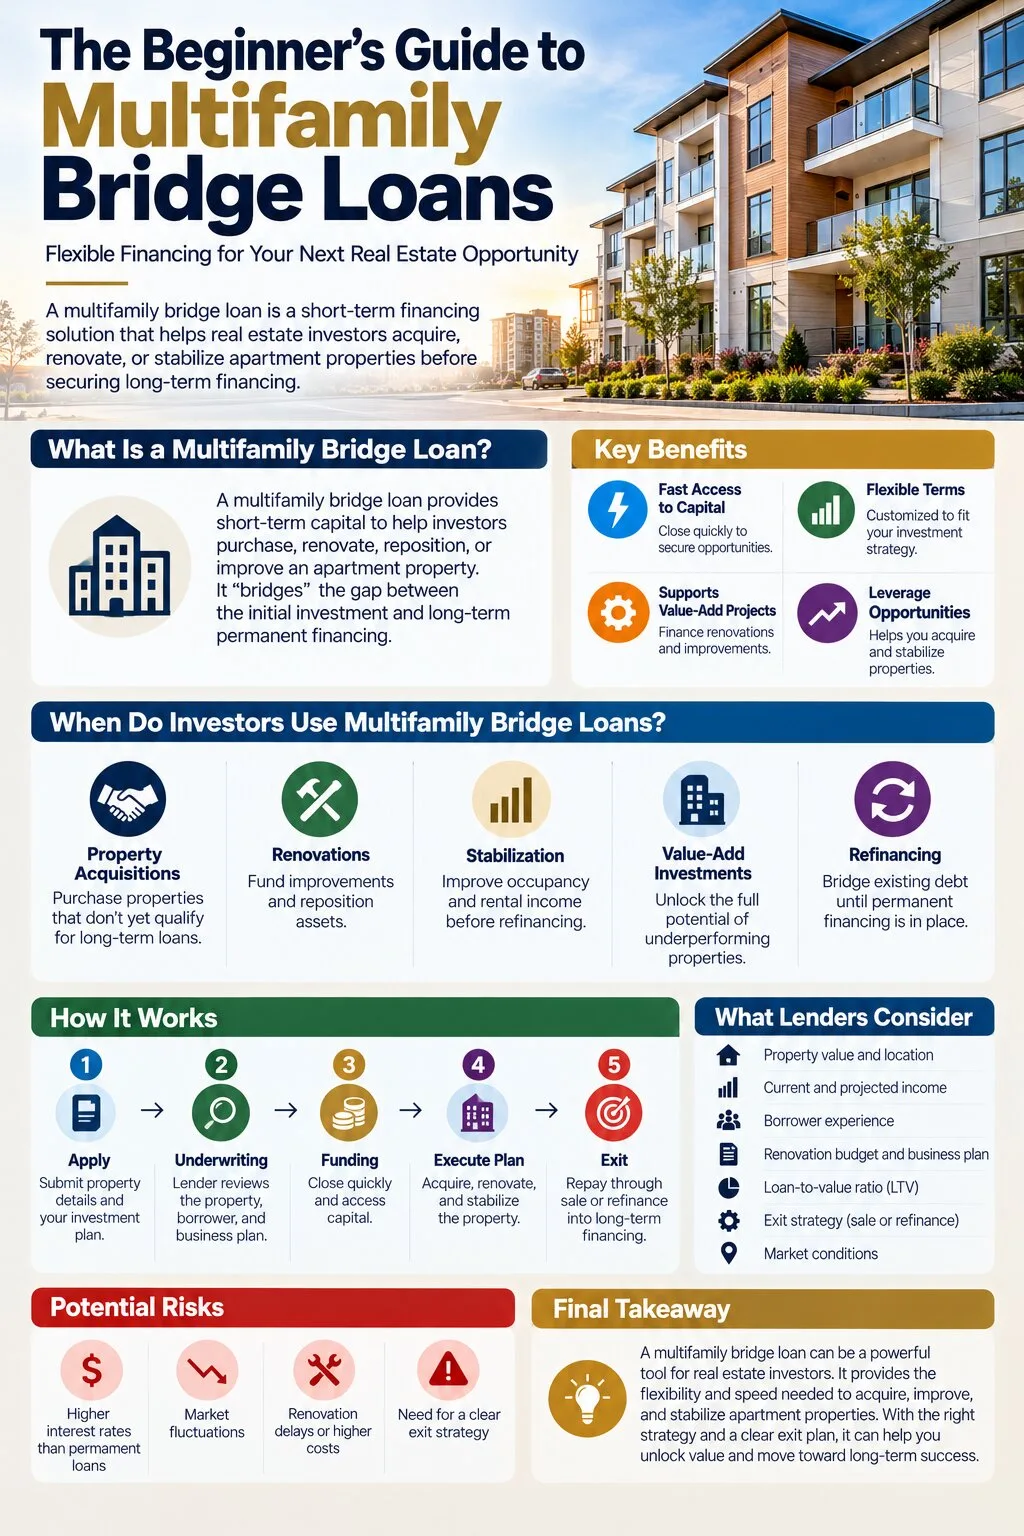
Buying or repositioning an apartment property often requires financing before the property reaches its full potential. A building may need renovations, improved occupancy, better management, or time to stabilize its income before it qualifies for long-term financing.
This is where a multifamily bridge loan can become useful. It provides short-term financing during a transitional period, giving an investor time to improve the property or prepare for permanent financing.
For some borrowers, asset based lending can also be part of the financing strategy because the property and its value may play an important role in evaluating the transaction.
What Is a Multifamily Bridge Loan?
A multifamily bridge loan is short-term financing used for an apartment building or other multifamily property that is going through a transition.
The Office of the Comptroller of the Currency describes bridge loans as short-term financing that can help newly constructed or acquired commercial properties reach stabilization. This can give a property time to complete lease-up and establish income before moving to permanent financing.
For example, an investor might purchase an apartment building with:
Below-market rents
Vacant units
Deferred maintenance
An unfinished renovation plan
Operational issues
A need for improved occupancy
The investor may use bridge financing to acquire and improve the property, then refinance with longer-term financing once the property reaches the desired level of stability.
How Does a Multifamily Bridge Loan Work?
The basic structure is relatively straightforward.
Purchase or refinance property → Obtain bridge financing → Complete improvements or stabilization → Increase property performance → Refinance or sell
The exact structure depends on the lender, property, borrower, business plan, and expected exit strategy.
Bridge financing is generally temporary. The borrower needs a clear plan for repaying the loan, commonly through a sale or refinancing with permanent debt.
Why Would an Investor Use a Bridge Loan?
Investors may consider bridge financing when traditional long-term financing doesn't fit the property's current condition.
For example, imagine an apartment building with 40 units. The property has potential, but several units are vacant and require renovation. Its current income may not support the permanent loan amount the investor ultimately wants.
A bridge loan may provide financing while the investor:
Acquires the property.
Renovates vacant units.
Improves occupancy.
Addresses deferred maintenance.
Improves property operations.
Stabilizes rental income.
Refinance into longer-term financing.
The strategy depends on whether the projected improvements are realistic and whether the property can support the planned exit.
What Is Asset Based Lending?
Asset based lending generally refers to financing where the value and quality of assets play an important role in the lending decision.
In commercial real estate, the property itself can be an important part of the collateral and underwriting process. However, asset-based financing doesn't mean the borrower's financial position is irrelevant. Lenders may still evaluate the property's income, value, debt structure, repayment plan, experience, liquidity, and other factors.
For multifamily investors, this approach can be relevant when the property's current performance doesn't fully reflect its potential.
Marques Commercial Capital describes its multifamily financing approach as asset-based, with consideration given to the property's value and revenue-generating potential.
Multifamily Bridge Loans vs. Traditional Financing
Traditional permanent financing is generally designed for stabilized properties with established income and predictable operating performance.
A bridge loan serves a different purpose.
The right option depends on the property's condition and the investor's business plan.
What Can a Multifamily Bridge Loan Be Used For?
Depending on the lender and loan structure, bridge financing may be used for several transitional situations.
Property Acquisition
An investor may need financing to purchase an apartment property before making improvements.
Renovations
Funds may support planned improvements that are expected to increase occupancy, rents, property value, or operating performance.
Lease-Up
A newly acquired or renovated property may need time to reach its target occupancy.
Repositioning
An investor may purchase an underperforming property with a plan to improve management, renovate units, or change the property's operating strategy.
Refinancing
Bridge financing may also be considered when an existing loan needs to be replaced while the property is being repositioned.
What Do Lenders Look At?
A lender evaluating a multifamily bridge transaction may review several factors.
Property Value
The current and expected value of the property are important considerations.
Net Operating Income
The property's income and expenses help determine its current financial performance and ability to support debt.
Business Plan
The lender may want to understand exactly how the borrower plans to improve the property.
Borrower Experience
Experience with similar multifamily projects can be relevant, particularly when the business plan involves significant renovations or repositioning.
Loan-to-Value
Lenders may compare the proposed loan amount with the property's value.
Exit Strategy
A bridge loan should have a realistic repayment plan. The borrower may expect to refinance into permanent financing or sell the property after stabilization.
The OCC emphasizes that commercial real estate underwriting should consider the source and timing of repayment and should support income and value assumptions with appropriate analysis.
What Is an Exit Strategy?
An exit strategy explains how the borrower expects to repay the bridge loan.
Common strategies include:
Refinance:
The investor improves and stabilizes the property, then replaces the bridge loan with permanent financing.
Sale:
The investor completes the business plan and sells the property, using sale proceeds to repay the loan.
Long-term hold:
The investor may refinance once the property produces sufficient income for a longer-term loan.
A strong exit strategy should account for realistic property values, rents, occupancy, expenses, market conditions, and financing availability.
What Are the Risks?
Bridge loans can be useful, but they aren't risk-free.
Short Loan Term
The borrower has a limited period to execute the business plan and repay or refinance the loan.
Interest Costs
Short-term financing can carry higher costs than some permanent financing options.
Property Performance
If occupancy or income doesn't improve as expected, refinancing may become more difficult.
Construction Delays
Renovation delays can extend the stabilization period and increase project costs.
Market Conditions
Changes in property values, interest rates, rents, or lending standards can affect the exit strategy.
These risks make realistic underwriting and planning important. Commercial real estate lending involves evaluating repayment capacity, collateral, market conditions, and other credit factors.
When Does a Bridge Loan Make Sense?
A multifamily bridge loan may make sense when the property has a clear value-add or stabilization opportunity and the investor has a realistic plan for reaching the next financing stage.
For example:
Current property: 60-unit apartment building with 15 vacant units
Plan: Renovate vacant units and improve property operations
Bridge period: Complete renovations and lease-up
Target: Stabilize occupancy and income
Exit: Refinance into permanent financing
This is only an example. Actual loan terms, qualification requirements, costs, and timelines vary by transaction.
Questions to Ask Before Choosing a Bridge Loan
Before accepting financing, investors should understand:
What is the total loan amount?
What is the interest rate?
What fees apply?
How long is the loan term?
Are extension options available?
What are the prepayment terms?
What improvements can be financed?
What are the lender's underwriting requirements?
What happens if stabilization takes longer than expected?
What is the planned exit strategy?
What assumptions support the projected property value and income?
Getting clear answers can help investors compare financing options more effectively.
How Asset Based Lending Can Fit Into the Strategy
For investors considering asset based lending, the property's value and income potential can be central parts of the financing discussion.
This can be relevant for properties where the current financial performance doesn't tell the entire story. An investor may have a clear plan to renovate units, improve operations, increase occupancy, or reposition the property.
However, asset-based financing isn't a guarantee of approval. Lenders still assess risk and may consider the property, borrower, loan structure, repayment plan, and other transaction-specific factors.
Final Thoughts
A multifamily bridge loan can provide short-term financing for an apartment property that needs time to stabilize, renovate, improve occupancy, or transition toward permanent financing.
The key is having a clear business plan and realistic exit strategy. Investors should understand the property's current performance, projected improvements, financing costs, and risks before moving forward.
For borrowers exploring asset based lending, the property's value and revenue potential may be important parts of the financing analysis. The right structure ultimately depends on the property, borrower, investment strategy, and lender requirements.
Frequently Asked Questions
What is a multifamily bridge loan?
It is short-term financing for a multifamily property that is going through a transition, such as acquisition, renovation, lease-up, or stabilization.
How long does a bridge loan last?
Terms vary by lender and transaction. The OCC notes that commercial bridge loans are often written for periods of up to three years, although individual loan structures can differ.
Can bridge financing be used for renovations?
It can be, depending on the loan structure and lender. Renovation and repositioning are common reasons investors consider transitional financing.
What is asset based lending in commercial real estate?
Asset based lending places significant emphasis on the value and quality of the underlying asset. For real estate transactions, property value and income potential can be important parts of the analysis.
What is the typical exit strategy for a bridge loan?
Common exits include refinancing into permanent financing or selling the property after stabilization.
Is a multifamily bridge loan right for every investor?
No. Bridge financing can carry higher costs and requires a realistic plan for improving or stabilizing the property and repaying the loan.
What should investors prepare before applying?
Investors should generally be prepared to explain the property, purchase or refinance terms, current financial performance, renovation or stabilization plan, borrower experience, requested financing, and proposed exit strategy.
0 comments
Log in to leave a comment.
Be the first to comment.