
The 50/30/20 Budget Rule: Does It Actually Work in 2026?
A practical guide to managing your salary, covering everyday expenses and saving money without following an unrealistic budget.

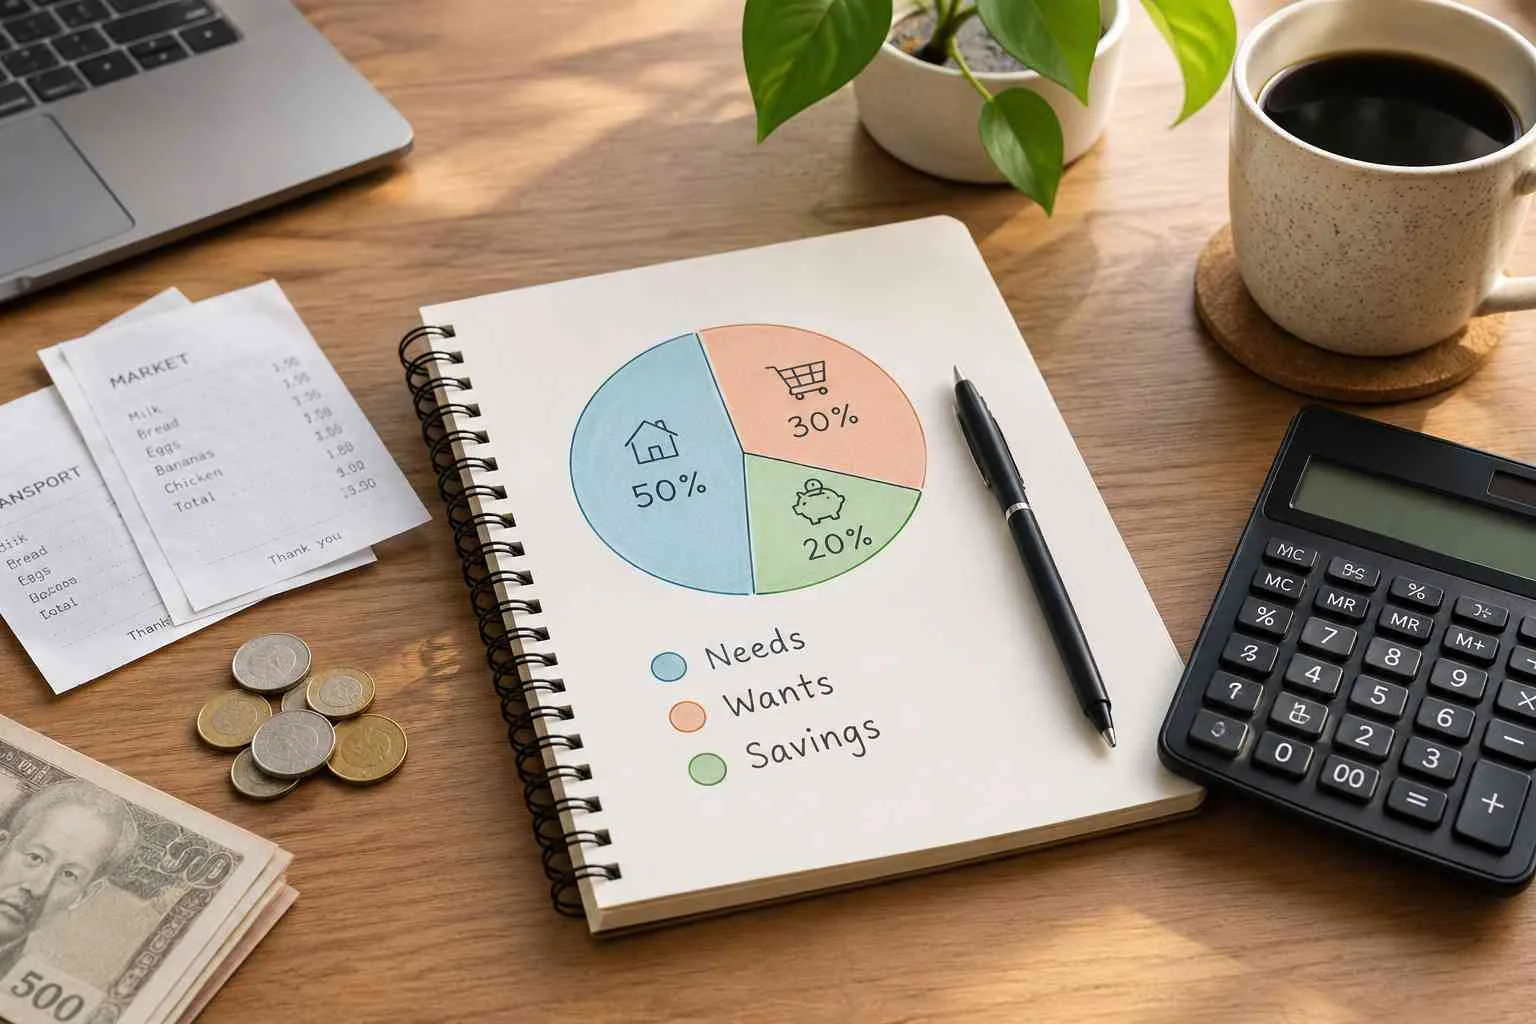
You receive your salary, pay rent, clear a few bills, order food a couple of times, and perhaps buy something you had been putting off. A few weeks later, you check your bank balance and wonder where the money went.
The frustrating part is that you might not have made any particularly expensive purchases. The money simply went toward dozens of ordinary expenses that were easy to overlook individually.
This is where the 50/30/20 budgeting rule can help. It gives you a simple way to divide your income between essential expenses, personal spending and financial goals. But there is a catch: the rule assumes your essential expenses fit within half your income, which is not realistic for everyone.
So, rather than treating it as another financial rule you must follow perfectly, let's see how it works with actual numbers, where it falls short and how you can adapt it to your circumstances.
What Is the 50/30/20 Budgeting Rule?
The 50/30/20 rule divides your after-tax income into three categories:
50% for needs: Expenses you need to cover, such as rent, groceries, electricity, basic transport and essential bills.
30% for wants: Non-essential spending, including dining out, entertainment, shopping and subscriptions.
20% for savings and debt repayment: Money set aside for future goals, emergency savings and paying down debt.
The Consumer Financial Protection Bureau (CFPB) describes this as one possible spending guideline, while acknowledging that people may need to develop a rule that suits their own financial circumstances.
The important detail is that the percentages apply to your take-home income, not your salary package before taxes and other deductions.
For example, if you receive ₹50,000 in your bank account each month, your suggested allocation would look like this:
Budget categoryPercentageMonthly amountNeeds50%₹25,000Wants30%₹15,000Savings and debt repayment20%₹10,000Total100%₹50,000These are calculated targets, not figures you are expected to achieve regardless of your rent, family responsibilities or existing debt.
Let's Put the Rule to Work With a Realistic Example
Imagine someone earning ₹50,000 a month after deductions and living in a city where rent and daily expenses take up a substantial part of their salary.
Their first attempt at following the rule might look something like this:
Monthly expenseAmountRent and maintenance₹15,000Groceries and meals at home₹6,000Electricity, internet and phone₹2,000Transport₹3,000Essential medical and household expenses₹2,000Total needs₹28,000Their essential expenses already amount to ₹28,000, or 56% of their take-home income. The suggested limit was ₹25,000.
That ₹3,000 difference matters. If this person tries to force their expenses into the 50% category without changing their housing or transport situation, they might end up cutting necessary spending instead of making a sustainable financial plan.
Now suppose they spend another ₹10,000 on eating out, entertainment, shopping and subscriptions, and put ₹8,000 toward savings.
Their monthly allocation becomes:
CategoryActual amountShare of incomeNeeds₹28,00056%Wants₹10,00020%Savings₹8,00016%Unallocated balance₹4,0008%Total₹50,000100%Notice something interesting: this person is spending less than the suggested 30% on wants, yet they still have not reached the 20% savings target.
That does not automatically mean they are managing money badly. It means they have a decision to make about the remaining ₹4,000 and whether they can increase their savings without compromising essential needs.
They could put some of that balance toward savings, retain some for irregular expenses, or use it to repay expensive debt. The right choice depends on their circumstances.
This is why I would use the 50/30/20 rule as a starting point rather than a test of financial discipline.
The salary and expenses above are an illustrative example, not a report of an actual person's finances.
How to Calculate Your Own 50/30/20 Budget
You do not need an elaborate spreadsheet to get started. Follow these steps using your take-home income and actual expenses.
Step 1: Start With Your Monthly Take-Home Pay
Use the amount that reaches your bank account after deductions. If your income changes from month to month, consider using a conservative estimate based on your recent earnings rather than budgeting around your best month.
For someone receiving ₹60,000 per month:
Needs target: ₹60,000 × 0.50 = ₹30,000
Wants target: ₹60,000 × 0.30 = ₹18,000
Savings target: ₹60,000 × 0.20 = ₹12,000
You can check these allocations using TheCalcu's free Budget Calculator. Enter your monthly income and expenses to see your total spending, monthly balance and savings rate.
Step 2: Review What You Actually Spend
Look at your bank statements, UPI transactions, card bills and recurring payments for at least one complete month. If possible, compare several months so that annual or occasional expenses do not distort your picture.
Separate essentials from discretionary purchases. A grocery shop is usually a need, but a premium snack or an impulse purchase within that same bill may be a want. Some expenses, such as a mobile plan or a vehicle, can contain both essential and optional elements.
The purpose is not to classify every rupee perfectly. It is to understand which expenses are fixed, which can change and which tend to catch you by surprise.
Step 3: Calculate Your Actual Percentages
Suppose your monthly needs total ₹32,000 and your take-home income is ₹60,000.
Your needs percentage is:
(₹32,000 ÷ ₹60,000) × 100 = 53.33%
You can use TheCalcu's percentage and math calculators to check your figures and compare different allocations.
Repeat the calculation for wants and savings. Once you know your actual percentages, you can decide what needs attention instead of guessing where your money is going.
Step 4: Make One Adjustment at a Time
If subscriptions, takeaway meals or impulse purchases are taking up more of your budget than you expected, start with a manageable adjustment. You do not have to eliminate every enjoyable expense to make progress.
If rent, essential bills and EMIs already consume most of your income, the solution may require a different approach: reviewing fixed costs when practical, adjusting short-term savings targets or finding ways to increase income.
A budget is useful only if you can maintain it beyond the first week.
Where the 50/30/20 Rule Falls Short
The rule is easy to remember, but its simplicity is also its biggest limitation.
1. Housing costs can make the 50% target unrealistic. If rent, maintenance and basic utilities already consume a large part of your take-home pay, there may be little room to reduce essential expenses immediately.
2. It does not account for everyone's responsibilities. Someone supporting parents, raising children or paying education and medical expenses may need a different allocation from someone living independently with few fixed commitments.
3. Irregular expenses can disrupt a monthly plan. Insurance premiums, repairs, travel to see family and annual fees may not arrive every month, but they still need funding. Consider setting aside a monthly amount for predictable upcoming costs.
4. Debt needs more than a percentage target. A person carrying expensive outstanding debt may need to prioritize repayments differently from someone with no debt and an established emergency fund.
5. Savings are not the same as leftover money. If you regularly finish the month with a balance but never deliberately allocate it, it can disappear into unplanned purchases. Give that money a purpose, whether it is emergency savings, debt repayment or a future expense.
These limitations do not make the rule useless. They simply explain why following the percentages exactly should not become more important than paying your bills and meeting your real financial obligations.
What If You Cannot Follow the 50/30/20 Rule?
Start with the numbers you have rather than the numbers you wish you had.
If your needs account for 60% of your income, your wants for 25% and your savings for 10%, the remaining 5% may be available for irregular costs or additional financial goals. That allocation is not a perfect 50/30/20 split, but it gives you a clear picture of your current situation.
You could gradually reduce discretionary spending, increase savings when your income rises, or revisit expensive fixed commitments when an opportunity arises. If your budget is already stretched, a small, consistent amount saved may be more practical than setting an ambitious target you cannot maintain.
It can also help to separate emergency savings from money intended for planned purchases. That way, an annual insurance bill or an unexpected repair does not automatically derail your longer-term savings plan.
If you are working toward a specific financial target, TheCalcu's Savings Goal Calculator can help estimate how much you may need to set aside each month based on your target, current savings, timeframe and assumed return. Remember that projected investment returns are estimates, not guarantees.
How to Make Your Budget Work Month After Month
The most useful budget is one you actually revisit.
Choose a regular day each month to review your income, essential expenses, discretionary spending and savings. Check whether an unusual expense affected your results, and adjust the next month's plan accordingly.
You can also automate a savings transfer after payday if your cash flow allows it, while keeping enough accessible money for bills and upcoming commitments.
Most importantly, avoid judging a month in isolation. An expensive month caused by a necessary repair does not mean your budgeting system has failed. The point is to recognize the expense, plan for what comes next and avoid repeating preventable surprises.
Final Thoughts: Is the 50/30/20 Rule Worth Following in 2026?
Yes, if you use it as a guide rather than a rigid financial rule.
Its real value is that it encourages you to distinguish between essential spending, lifestyle choices and future financial goals. But the ideal percentages will differ according to your income, location, obligations and priorities.
Start by calculating your actual spending. Find the category putting the most pressure on your budget, make a realistic adjustment and review the result next month. You do not need a perfect allocation to become more intentional with your money.
If you want to see where your salary goes before deciding what to change, start with TheCalcu Budget Calculator. It gives you a straightforward way to compare income, expenses and savings without building a spreadsheet from scratch.
Frequently Asked Questions
Is the 50/30/20 rule realistic for someone on a low salary?
Not always. Essential costs may consume more than 50% of a lower income, particularly when housing and transport are expensive. Use the rule to understand your spending, then create an allocation that covers your necessities first.
Should I use my gross salary or take-home salary?
Use your take-home pay after taxes and other payroll deductions. This is the amount available for your monthly budget.
Does the 20% savings category include debt repayment?
The traditional framework groups savings and debt repayment together. In practice, decide how much should go toward emergency savings, planned goals and outstanding debt based on your financial situation and the cost of borrowing.
What should I do if my expenses exceed my income?
First identify the size of the shortfall and separate essential costs from adjustable spending. Prioritize housing, food, utilities and other necessary obligations, then review discretionary expenses and available support or income options. Avoid taking on additional high-cost debt simply to preserve a target percentage.
How often should I review my budget?
Review it monthly and whenever your income, housing costs or major financial responsibilities change. A short, regular review is usually more useful than creating an elaborate budget and never checking it again.
Sources and further reading
0 comments
Log in to leave a comment.
Be the first to comment.