
Real Estate Tokenization: Could Secondary Markets Become More Important Than Primary Token Issuance in 2027?
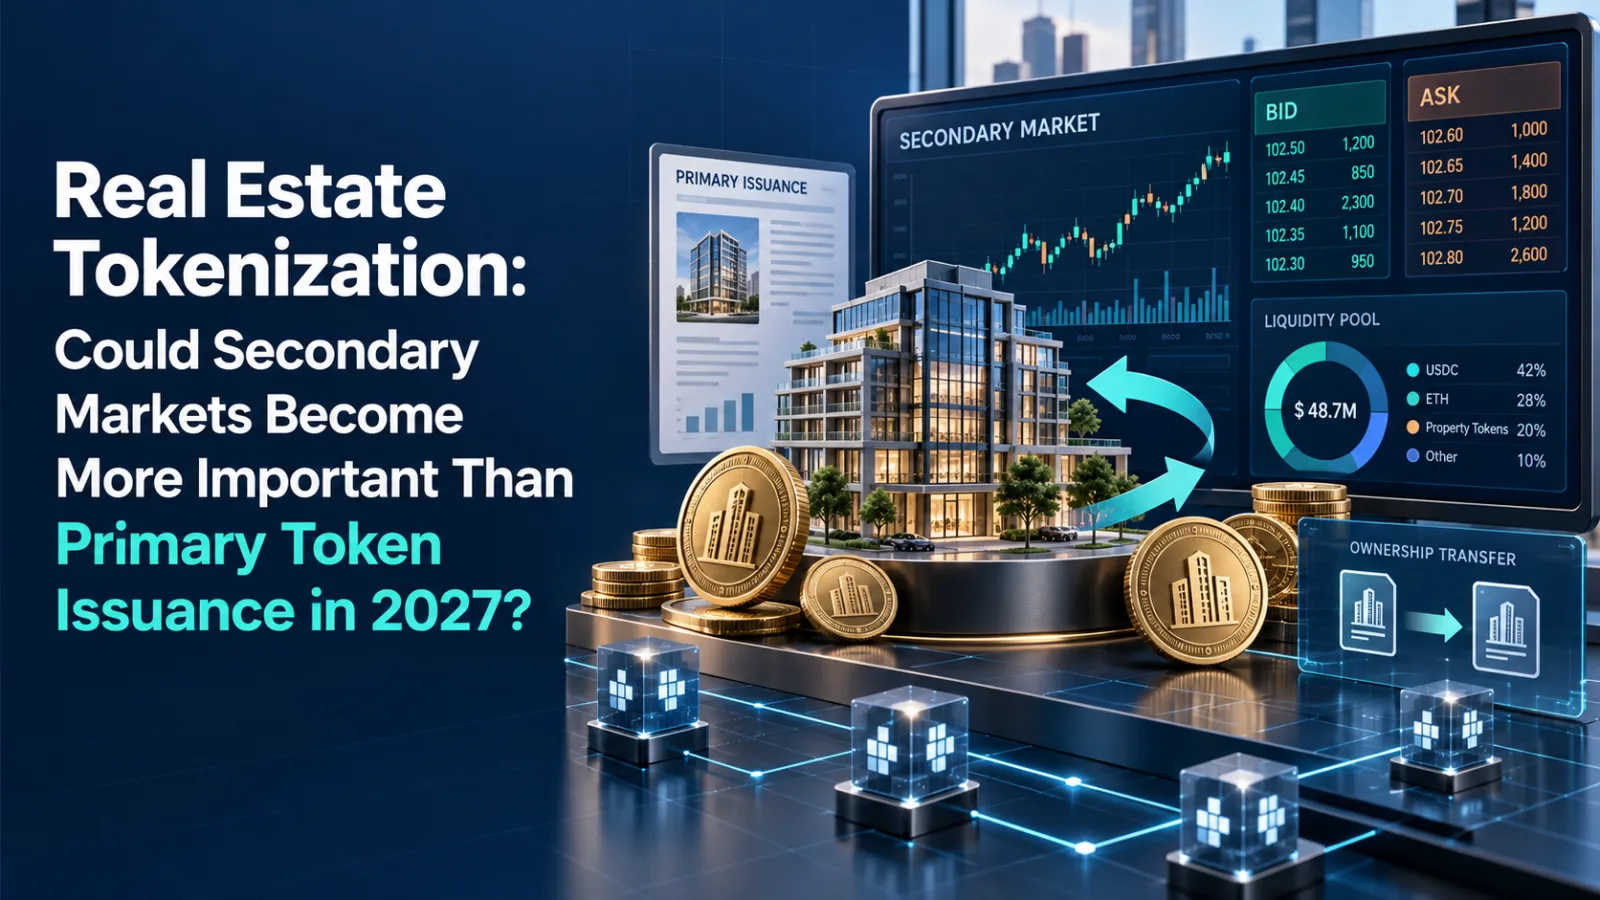
Real estate tokenization has gained attention as property owners, investment firms, developers, and financial platforms examine ways to represent property interests through blockchain-based tokens. Much of the discussion has focused on the primary market, where an asset is selected, structured, divided into digital units, and offered to investors. However, the next stage of the market could place greater attention on what happens after those tokens have been issued.
In 2027, secondary markets may receive more attention as investors look for ways to trade, transfer, or exit tokenized property positions. Primary issuance remains important because it brings assets onto a digital marketplace, but a token market cannot rely only on new property offerings. Investors may also want access to previously issued assets, price information, transfer mechanisms, and opportunities to manage their holdings.
This raises an important question: could secondary market activity become more important than primary token issuance in the next phase of real estate tokenization?
Why Primary Issuance Has Received Most of the Attention
Primary issuance is generally the starting point for a tokenized property project. A property may be placed within a legal structure, investor rights are defined, tokens are issued, and investors purchase those tokens through a designated platform. This process creates the initial market for the property.
For a real estate tokenization company, primary issuance can involve property assessment, legal structuring, token design, smart contract development, investor onboarding, payment processing, and reporting. Each stage affects how investors interact with the asset.
The primary market also provides a way for property owners and developers to seek capital from a wider investor base. Instead of relying entirely on conventional financing routes, a project may use digital ownership or economic-interest tokens to represent participation in a property or property-related structure.
Yet primary issuance has a natural limitation. Once an offering is completed, the platform needs another property or project to create fresh transaction activity. This makes secondary market infrastructure increasingly relevant if tokenized real estate is expected to support continuing investor activity.
What Could Make Secondary Markets More Relevant in 2027?
A secondary market allows investors to transact after the original issuance. Depending on the legal structure and applicable regulations, token holders may be able to sell their interests to eligible buyers instead of waiting for a property sale, refinancing event, maturity date, or other exit event.
For tokenized real estate, this could change how investors view digital property interests. The initial purchase is only one part of the investment journey. Investors may also want information about current valuations, transaction history, distributions, holding periods, and possible buyers.
If more tokenized properties enter the market, the number of previously issued tokens could grow significantly. At that point, investors may spend as much time looking at existing tokenized assets as they do at new offerings.
This does not mean secondary markets will necessarily replace primary issuance. Instead, the two markets could become increasingly connected. Primary issuance introduces new properties, while secondary activity gives existing tokens another phase of market life.
Method 1: Creating More Opportunities for Investor Exit
One of the main reasons secondary markets could gain importance is investor exit.
Traditional property investments can involve long holding periods. Selling an entire property is often a complicated process involving negotiations, documentation, financing arrangements, due diligence, and legal procedures. Tokenization can divide an economic interest into smaller digital units, which may create a different route for investors to transfer their positions.
A secondary market could provide a venue where eligible investors can list and purchase previously issued property tokens. The exact process would depend on the legal and regulatory framework governing the asset and marketplace.
For investors, the availability of an exit mechanism may influence how they evaluate a tokenized property. A property offering may receive greater attention when investors understand how their position could potentially be transferred later.
Method 2: Developing Better Market Data
Secondary markets could also increase the importance of pricing and transaction data.
During a primary offering, the issuer generally sets an initial price based on the asset structure, valuation, expected returns, fees, and other factors. Once trading begins, market participants may generate additional information through actual transactions.
Over time, transaction prices can provide indications of how investors value a particular tokenized property interest. Platforms could display historical transactions, current listings, distribution records, valuation updates, and other relevant information.
For a real estate asset tokenization company, developing reliable market data systems could therefore become an important area of platform development. Investors may want to compare properties based on location, asset type, income characteristics, occupancy, valuation, token price, and previous transaction activity.
Method 3: Connecting Primary and Secondary Market Infrastructure
The distinction between primary issuance and secondary trading may become less rigid in 2027.
A real estate tokenization platform development project could include functions for both issuing new tokens and supporting eligible transfers of existing tokens. This creates a more continuous marketplace rather than a platform that focuses only on initial fundraising.
For example, an investor could purchase tokens during an initial property offering and later return to the same platform to monitor distributions or seek a transfer opportunity. Another investor could enter the property through a secondary transaction rather than participating in the original offering.
This type of structure may increase the usefulness of the platform over the entire investment lifecycle.
Method 4: Improving Investor Onboarding and Compliance
Secondary markets also introduce additional compliance considerations.
A token transfer is not necessarily as simple as moving a cryptocurrency between wallets. Real estate interests can be subject to securities laws, ownership restrictions, geographic limitations, investor eligibility requirements, tax rules, and transfer conditions.
A real estate tokenization development company working on a secondary market may therefore need identity verification, investor eligibility checks, wallet screening, transaction monitoring, transfer restrictions, and appropriate recordkeeping.
Smart contracts can support some of these processes, but legal rules still determine what transactions are permitted. The platform must reflect the applicable framework instead of treating token transfers as unrestricted blockchain transactions.
Method 5: Increasing the Use of Digital Property Markets
Another possible development is the growth of specialized digital property marketplaces.
A marketplace focused on tokenized real estate could bring together residential projects, commercial properties, hotels, warehouses, development projects, rental assets, and other property interests. Investors could then compare available primary offerings with previously issued tokens.
This may create different market behaviors. Some investors may prefer newly issued projects because of their expected development or income profile. Others may prefer existing tokens because they can review historical performance and previous transaction activity.
The presence of both options could make marketplace design increasingly important for real estate tokenization platform development.
Could Secondary Markets Affect Real Estate Token Development?
Real estate token development has often focused on token standards, smart contracts, wallets, payment systems, investor dashboards, and issuance mechanisms. In 2027, developers may need to think more about what happens after the token reaches investors.
A token may need transfer restrictions, ownership records, compliance rules, distribution logic, and links to relevant property information. The smart contract may also need functions that support permitted transfers between verified participants.
This changes the development conversation. Instead of asking only how to issue a property token, businesses may also ask how that token will behave throughout its market life.
For a real estate tokenization platform development company, this could mean designing infrastructure around issuance, custody, transfers, investor communication, transaction records, and marketplace activity.
What Could Encourage More Secondary Trading?
Several conditions could contribute to secondary market growth.
First, a larger number of tokenized properties would provide more assets for investors to compare and trade. A marketplace with only a handful of assets may have limited activity, while a larger collection could attract more participants.
Second, investors may become more familiar with tokenized property structures. As the market matures, participants could become more comfortable evaluating digital ownership records, distributions, property valuations, and transfer conditions.
Third, regulatory frameworks will have an important role. Secondary trading requires clarity around who can trade, what can be traded, where transactions can occur, and how ownership is recorded.
Fourth, reliable property information matters. Investors need sufficient information to assess the assets behind tokens. Better reporting could support more informed market participation.
The Role of Real Estate Tokenization Companies
A real estate tokenization company may increasingly need to consider the entire lifecycle of a property token instead of focusing only on the initial offering.
This includes property selection, legal structuring, token creation, investor onboarding, distribution management, reporting, custody, transfer controls, and secondary market functions. Each component can affect the investor experience.
Businesses researching Top real estate tokenization companies or Best real estate tokenization companies should therefore look beyond the ability to issue tokens. They may also examine whether a provider has experience with marketplace infrastructure, smart contracts, compliance systems, investor dashboards, asset management, and post-issuance functionality.
The market may gradually move from an issuance-centered model toward a broader digital property ecosystem.
What Could Happen to Primary Issuance in 2027?
Primary issuance is unlikely to lose its relevance simply because secondary markets receive more attention.
New assets still need to enter the market. Developers need funding, property owners may seek new forms of capital, and investment firms may continue creating property-backed products. Without new issuance, secondary marketplaces would eventually have fewer new assets to introduce.
The relationship may instead become cyclical. New properties enter through primary offerings. Investors acquire tokens. Those tokens remain within investor portfolios. Some holders later seek to sell or transfer their positions. New buyers enter through secondary transactions. At the same time, fresh properties continue entering through primary issuance.
This creates a market in which issuance and secondary activity support different stages of the investment process.
Challenges That Secondary Markets May Face
Despite the potential, secondary markets also face significant challenges.
Liquidity cannot be created simply by placing tokens on a marketplace. Buyers and sellers need to exist at suitable prices and times. A tokenized property may still experience limited trading if there is little investor demand.
Property valuation can also be complicated. Real estate does not trade continuously like many financial assets. Property conditions, rental income, occupancy, interest rates, local markets, and broader economic factors can affect valuation.
Regulation presents another challenge. A platform handling tokenized property interests may need to follow securities, financial services, property, tax, and data requirements depending on its jurisdiction and structure.
Technology is another consideration. Wallet management, smart contracts, identity systems, payment processing, investor records, and marketplace functions must work together while maintaining appropriate controls.
How Businesses Could Prepare for 2027
Businesses considering real estate tokenization development may benefit from thinking beyond the initial token sale.
A project plan could include the expected investor journey from initial purchase through holding, distributions, reporting, transfer, and potential exit. This can help determine which platform functions are needed from the beginning.
Property owners and developers may also need to consider whether their chosen legal structure supports permitted transfers. Investor eligibility, geographical restrictions, holding requirements, and resale conditions should be addressed before marketplace functions are introduced.
Technology teams can then design smart contracts and platform components around these requirements. This approach can reduce the need to rethink the entire system when secondary trading becomes a priority.
The Potential Market Shift in 2027
The most notable change may not be a simple movement from primary issuance to secondary trading. Instead, 2027 could bring greater attention to the complete lifecycle of tokenized real estate.
Primary issuance answers the question of how an asset enters a digital market. Secondary markets address what investors can do after they own the asset. Both functions are connected.
If tokenized property markets expand, secondary transactions could become a major measure of marketplace activity. Investors may increasingly judge platforms by the range of available assets, transaction opportunities, market information, investor services, and post-issuance support.
For businesses, this means real estate tokenization may become less about creating a token and more about developing a functioning digital market around property interests.
Conclusion
Real estate tokenization in 2027 could enter a phase where secondary markets receive significantly more attention alongside primary issuance. New property offerings will remain necessary because they introduce fresh assets and investment opportunities, but the long-term usefulness of tokenized real estate may depend heavily on what investors can do after purchasing their tokens. Secondary marketplaces could support transfers, provide additional market information, create new entry and exit routes, and encourage continued activity around previously issued property interests. At the same time, liquidity, regulation, property valuation, investor eligibility, and technology remain important considerations. Businesses planning real estate tokenization development may therefore need to consider both issuance and post-issuance activity when designing their platforms. Blockchain App Factory provides Real estate tokenization development services.
FAQs
1. What Is Secondary Market Activity in Real Estate Tokenization?
Secondary market activity refers to transactions involving previously issued real estate tokens. Instead of purchasing directly from the original issuer, an eligible investor may acquire tokens from another holder through a permitted marketplace or transfer mechanism.
2. Why Could Secondary Markets Become More Important in 2027?
As more tokenized properties enter the market, investors may have greater interest in trading existing tokens rather than focusing only on new offerings. Secondary markets could also provide additional options for investors seeking to transfer their positions.
3. Will Secondary Markets Replace Primary Real Estate Token Issuance?
Not necessarily. Primary issuance introduces new assets into the market, while secondary markets provide opportunities for transactions involving existing assets. Both can serve different stages of the tokenized property lifecycle.
4. What Does a Real Estate Tokenization Company Do?
A real estate tokenization company may provide services covering property token structuring, smart contract development, investor onboarding, token issuance, compliance functions, marketplace systems, reporting, and related platform services.
5. What Is Real Estate Token Development?
Real estate token development involves creating digital tokens that represent defined rights or interests connected to a property or property-related legal structure. The exact rights depend on the project's legal and financial arrangement.
6. What Features Could a Secondary Real Estate Token Marketplace Include?
Potential features may include investor verification, asset listings, token transfer functions, transaction records, portfolio management, pricing information, compliance checks, payment processing, reporting, and smart contract-based transfer restrictions.
7. Why Is Liquidity Important for Tokenized Real Estate?
Liquidity refers to the ability to buy or sell an asset without excessive difficulty or major price disruption. For tokenized real estate, secondary markets may provide additional opportunities for investors to transfer their positions, although liquidity is not guaranteed.
8. How Can a Real Estate Tokenization Platform Development Company Support Secondary Markets?
A real estate tokenization platform development company can create marketplace infrastructure, investor interfaces, smart contracts, compliance functions, asset records, transfer mechanisms, and reporting systems based on the project's legal and business requirements.
9. What Should Businesses Consider Before Launching a Tokenized Property Marketplace?
Businesses should examine legal structure, investor eligibility, property rights, token design, compliance requirements, transfer restrictions, custody arrangements, valuation methods, payment systems, cybersecurity, reporting, and the expected secondary market model.
10. Are Secondary Markets Suitable for Every Tokenized Property?
No. The suitability of secondary trading depends on the property's legal structure, applicable regulations, investor restrictions, token design, marketplace rules, and available demand. A tokenized asset does not automatically have a liquid secondary market.
0 comments
Log in to leave a comment.
Be the first to comment.