
Prepaid Wallet License in India: Requirements, Process and RBI Regulations
Learn how to obtain a prepaid wallet license in India, including RBI eligibility, capital requirements, application process, compliance and documentation.
Digital payments have become an essential part of India's business environment. From online shopping and utility payments to travel bookings and corporate expense management, prepaid wallets provide customers with a convenient way to make digital transactions without repeatedly entering their bank details.
For businesses planning to enter this sector, obtaining a prepaid wallet license is an important regulatory consideration. The Reserve Bank of India (RBI) regulates prepaid payment instruments (PPIs), which allow users to store money and use the available balance for permitted transactions.
However, launching a digital wallet is not simply a matter of developing an application and integrating a payment gateway. Businesses intending to issue and operate regulated prepaid payment instruments must understand the applicable RBI authorisation framework, eligibility conditions, capital requirements, KYC obligations and ongoing compliance responsibilities.
This guide explains the process of obtaining a prepaid wallet license in India and the key considerations businesses should address before entering the digital payments industry.
1. What Is a Prepaid Wallet License?
A prepaid wallet license refers to the regulatory authorisation required for eligible entities to issue and operate certain prepaid payment instruments in India.
A prepaid payment instrument is a payment facility in which money is loaded in advance and subsequently used for purchases, services, financial transactions or other permitted purposes.
For example, a customer may add money to a digital wallet and use the balance to:
Pay for goods and services.
Make eligible online purchases.
Pay utility bills.
Make payments to permitted merchants.
Access other services allowed under the applicable PPI category.
The RBI regulates these instruments under the Master Directions on Prepaid Payment Instruments, 2021, issued under the Payment and Settlement Systems Act, 2007.
Businesses should understand that a prepaid wallet license is not a separate universal licence for every wallet-related activity. The regulatory requirements depend on the type of instrument, its intended use and the entity issuing it.
2. Types of Prepaid Payment Instruments in India
Before applying for RBI authorisation, a business must identify the category of prepaid payment instrument that matches its proposed business model.
A. Closed System PPIs
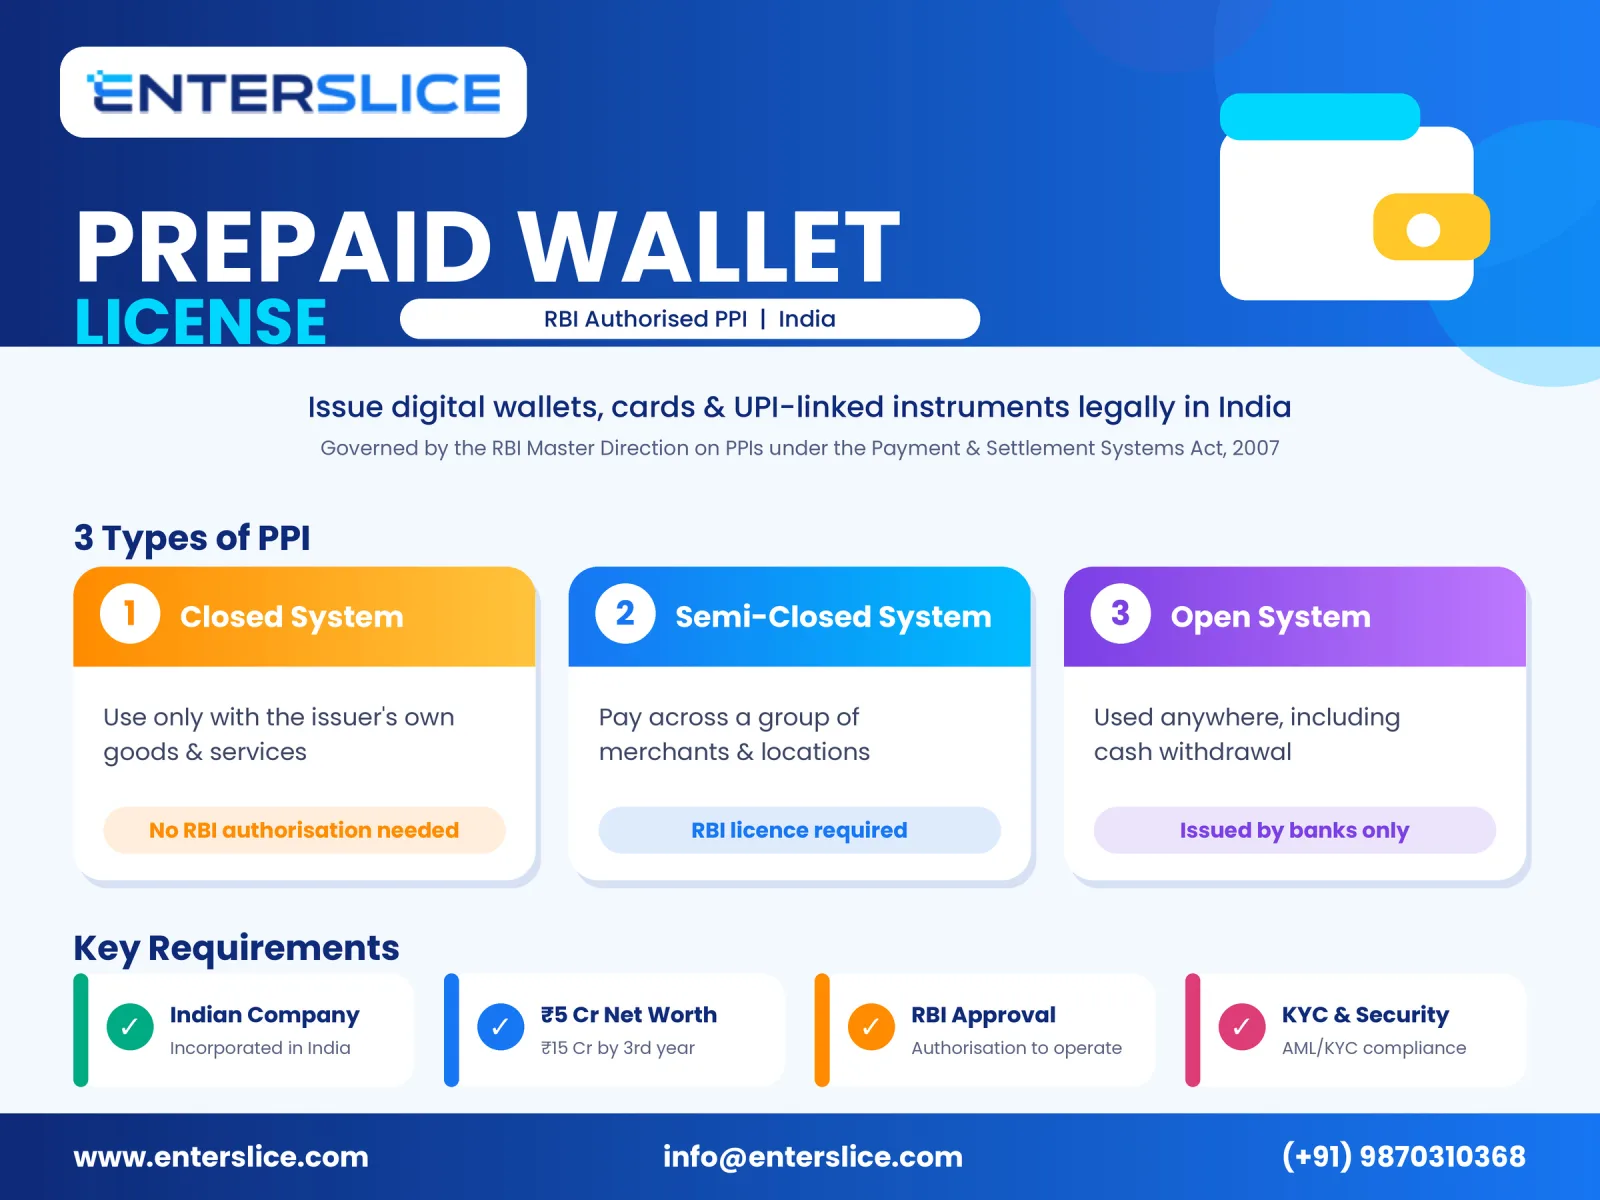
Closed-system instruments are issued by an entity for purchasing goods and services exclusively from that entity.
For example, a retail business may offer a prepaid balance that customers can use only to purchase products from its own stores or platform.
These instruments cannot be used for third-party payments or cash withdrawals. They do not require RBI authorisation under the PPI framework.
B. Small PPIs
Small PPIs are subject to prescribed limits and restrictions. They are issued against minimum customer details and can be used for permitted purchases in accordance with RBI requirements.
These instruments have restrictions relating to loading, outstanding balance and usage. They cannot be treated as equivalent to unrestricted digital wallets.
C. Full-KYC PPIs
Full-KYC PPIs are issued after completing the prescribed customer identification process.
They offer broader functionality than minimum-detail instruments, subject to applicable regulatory conditions. Depending on the permitted features, they may support purchases, fund transfers and other authorised transactions.
D. Special-Purpose PPIs
Certain PPIs are designed for specific purposes rather than general payments. Examples include:
Gift PPIs.
Transit PPIs.
PPIs issued to foreign nationals and NRIs visiting India.
Other specifically permitted categories.
Selecting the correct category is important because the applicable eligibility, operational and compliance requirements may differ.
3. Eligibility Criteria for Obtaining a Prepaid Wallet License
Businesses planning to become non-bank PPI issuers must satisfy the eligibility requirements prescribed by the RBI.
The major conditions include:
A. Company Incorporation in India
The applicant must be a company incorporated in India under the Companies Act, 2013 (or the applicable corresponding provisions of the earlier Companies Act).
A proprietorship or partnership firm cannot directly apply as a non-bank PPI issuer under this framework.
B. Minimum Net Worth
The RBI prescribes the following capital requirements for non-bank PPI applicants:
The applicable net-worth requirement must be maintained on an ongoing basis. A certificate from a Chartered Accountant or statutory auditor, as prescribed by the RBI, is required to establish compliance.
C. Object Clause in the MOA
The company's Memorandum of Association (MOA) must cover the proposed activity of issuing prepaid payment instruments.
If the existing MOA does not include the relevant business activity, the company should consider making the necessary corporate amendments before applying.
D. Fit and Proper Management
The promoters and directors must satisfy the RBI's fit-and-proper requirements. Their integrity, financial soundness, reputation and regulatory history may be examined.
E. Regulatory and Foreign Investment Compliance
Entities regulated by another financial sector regulator may need to obtain a No Objection Certificate (NOC) before approaching the RBI.
Companies having foreign investment must also comply with the applicable FDI policy and sectoral conditions.
These eligibility requirements should be evaluated before submitting the application because an incomplete or ineligible application may be returned without a refund of the application fee.
4. Step-by-Step Process to Obtain a Prepaid Wallet License in India
The RBI authorisation process involves regulatory scrutiny, financial assessment and technical evaluation. Businesses should prepare their documentation and operational framework before applying.
Step 1: Incorporate the Company
The first step is to establish an eligible company in India. The proposed business activities should be appropriately reflected in its constitutional documents.
The founders should also define the wallet's business model, intended customer base, transaction flow and proposed PPI category.
Step 2: Assess Capital and Financial Eligibility
The applicant must evaluate its net worth and financial position against the applicable RBI requirements.
A Chartered Accountant or statutory auditor should review the company's financial statements and prepare the required net-worth certificate.
Step 3: Prepare the Business and Compliance Framework
The applicant should prepare a comprehensive business plan covering:
Proposed wallet products and services.
Customer onboarding and KYC procedures.
Transaction processing and settlement arrangements.
Merchant acceptance arrangements.
Technology infrastructure and security controls.
Customer grievance redressal mechanisms.
Risk management and fraud prevention policies.
A clearly documented operational model helps demonstrate that the proposed payment system can function securely and efficiently.
Step 4: Submit the Application to RBI
Eligible non-bank entities must submit an application in Form A under Regulation 3(2) of the Payment and Settlement Systems Regulations, 2008, along with the prescribed application fee.
The application is submitted to the Department of Payment and Settlement Systems (DPSS), Central Office, RBI, Mumbai.
The directors must also provide the prescribed declarations and undertakings. RBI initially examines the applicant's eligibility, completeness of the application and fit-and-proper status.
Step 5: Obtain In-Principle Approval
After examining the application, the RBI may grant in-principle approval if the applicant satisfies the applicable conditions.
This approval is valid for six months. During this period, the applicant must complete the required technical and operational preparations.
Step 6: Complete the System Audit
The applicant must arrange a satisfactory System Audit Report (SAR) and submit it to the RBI within the prescribed six-month period.
The report must be accompanied by the required net-worth certificate.
A one-time extension of up to six months may be requested in advance with valid reasons. Approval of an extension is at the RBI's discretion.
Step 7: Obtain Final Authorisation
After receiving a satisfactory System Audit Report, the required financial certification and completing due diligence, the RBI may issue the final Certificate of Authorisation (CoA).
The business must commence operations within six months of receiving final authorisation, subject to the applicable RBI provisions.
Important: In-principle approval is not permission to start issuing regulated PPIs. Businesses must obtain the final authorisation before commencing the regulated activity.
Reserve Bank of India+1
5. Documents Required for a Prepaid Wallet License
Preparing the documentation in advance can make the RBI application process more organised.
The documents generally include:
The exact documentation depends on the proposed business model and RBI's requirements. Additional information or clarifications may be requested during regulatory scrutiny.
6. Important RBI Compliance Requirements for Wallet Operators
Obtaining a prepaid wallet license is only the beginning of regulatory compliance. Authorised PPI issuers must maintain appropriate systems and processes throughout their operations.
The following areas deserve particular attention.
A. KYC and AML Compliance
Wallet operators must follow applicable Know Your Customer (KYC), Anti-Money Laundering (AML) and Combating Financing of Terrorism (CFT) requirements.
Customer identification, verification, monitoring and record maintenance must be aligned with the relevant RBI directions.
A notable regulatory update came on November 28, 2025, when RBI replaced references to its earlier KYC Master Direction in relevant payment-system instructions with the Reserve Bank of India (Commercial Banks – Know Your Customer) Directions, 2025. PPI issuers should account for this change when updating their compliance frameworks.
Reserve Bank of India
B. Security of Digital Transactions
Wallet operators must maintain suitable technology and security controls to protect customer information and transaction data.
These controls should address unauthorised access, fraud monitoring, system vulnerabilities, data protection and business continuity.
C. Escrow Account Requirements
Non-bank PPI issuers must comply with the RBI-prescribed escrow account framework.
Customer funds received against outstanding PPIs must be safeguarded in accordance with the applicable directions. Businesses should establish appropriate banking arrangements and reconciliation processes.
D. Interoperability
Applicable PPI issuers must comply with RBI's interoperability framework.
Interoperability allows eligible payment instruments to interact with other payment systems, improving the convenience of digital transactions.
E. Customer Grievance Redressal
Wallet operators must establish an effective customer complaint-handling mechanism.
Customers should have access to clear information about failed transactions, unauthorised transactions, refunds, dispute resolution and escalation procedures.
F. Reporting and Audits
PPI issuers must maintain appropriate transaction records, submit applicable regulatory reports and undertake prescribed audits.
They should also monitor changes in RBI directions to ensure that their systems and policies remain compliant.
7. Business Opportunities in the Digital Wallet Industry
A prepaid wallet business can serve different customer segments depending on its product design and regulatory permissions.
Some potential business opportunities include:
E-commerce and Retail: Businesses can develop wallet solutions that facilitate payments across eligible merchant networks and improve the customer purchasing experience.
Corporate Expense Management: Companies can explore prepaid instruments for managing permitted employee expenses, reimbursements and business-related payments.
Travel and Transportation: Transit-focused PPIs can support payments across permitted public transport systems, including metro and bus networks.
Digital Financial Services: Eligible wallet operators can develop payment-related services and integrations within the scope of their authorisation.
Customer Loyalty and Rewards: Businesses can explore gift and other permitted purpose-specific prepaid instruments to strengthen customer engagement.
The commercial opportunity depends on the permitted PPI category, customer requirements, partnerships and the issuer's ability to maintain regulatory compliance.
8. Common Challenges in Obtaining RBI Wallet Authorisation
Despite the growing demand for digital payments, entering the prepaid wallet industry involves several regulatory and operational challenges.
Some common difficulties include:
Capital requirements: Maintaining the prescribed net worth can be challenging for early-stage startups.
Regulatory documentation: Preparing complete applications, financial records and management declarations requires careful attention.
Technology readiness: Businesses need secure and reliable infrastructure capable of handling payment transactions.
Compliance management: KYC, AML, transaction monitoring and reporting require ongoing investment.
Audit requirements: Meeting RBI's system audit expectations within the prescribed timeline can require substantial technical preparation.
A practical approach is to assess regulatory eligibility before investing heavily in application development or marketing.
9. Why Professional Assistance Matters for PPI Authorisation
Obtaining RBI authorisation requires more than submitting an application. The applicant must demonstrate financial eligibility, sound management, technical preparedness and the ability to comply with payment-system regulations.
Professional assistance can help businesses with:
Evaluating eligibility for non-bank PPI authorisation.
Reviewing company structure and MOA provisions.
Assessing net-worth requirements.
Preparing the business plan and regulatory documentation.
Developing KYC, AML and risk management policies.
Coordinating system audit requirements.
Supporting application preparation and regulatory correspondence.
Working with experienced regulatory consultants can help identify documentation gaps and compliance issues before they become obstacles during the authorisation process.
10. Conclusion
The prepaid wallet industry offers opportunities for Indian startups, technology companies and established businesses looking to enter digital payments. However, operating a regulated wallet business requires proper planning, adequate financial resources and compliance with RBI's PPI framework.
A business should first identify its proposed wallet category, assess its eligibility, understand the applicable capital requirements and prepare its technology and compliance infrastructure.
With appropriate regulatory preparation and professional guidance, businesses can approach the prepaid wallet authorisation process with greater clarity and confidence.
Looking to Obtain a Prepaid Wallet License in India?
Enterslice assists businesses with regulatory advisory, company compliance, documentation and licensing-related support. If you are planning to launch a digital wallet business, connect with Enterslice to understand the applicable RBI requirements and prepare your authorisation strategy.
Most popular services :
Mortgage Guarantee Company Registration
Virtual cfo
Regulatory Compliance and Advisory Services
Legal due diligence
Transmission of Shares
Frequently Asked Questions (FAQs)
1. Is a Prepaid Wallet License Mandatory in India?
RBI authorisation is required for entities issuing and operating regulated PPIs, subject to the applicable framework. Closed-system PPIs used exclusively for purchasing goods and services from the issuing entity do not require RBI authorisation.
2. What Is the Minimum Net Worth Required for a Prepaid Wallet License?
A non-bank applicant must have a minimum positive net worth of ₹5 crore when applying. It must achieve a minimum positive net worth of ₹15 crore by the end of the third financial year after receiving final authorisation and maintain the applicable requirement thereafter.
3. Who Can Apply for a Prepaid Payment Instrument License?
A company incorporated in India under the Companies Act, 1956 or 2013 can apply as a non-bank PPI issuer, subject to the applicable eligibility, financial, management and regulatory requirements.
4. How Long Does It Take to Obtain a Prepaid Wallet License?
There is no guaranteed standard processing period. The timeline depends on application completeness, RBI scrutiny, technical readiness and audit compliance. The in-principle approval stage provides six months to submit a satisfactory System Audit Report.
5. What Is the Difference Between a Prepaid Wallet and a Payment Gateway?
A prepaid wallet stores a monetary balance that customers can use for permitted transactions. A payment gateway facilitates the secure transmission of payment information between customers, merchants and payment participants. Their regulatory requirements and business activities are different.
6. Can a Startup Launch a Digital Wallet Business in India?
Yes, an eligible startup incorporated as a company can apply for non-bank PPI authorisation if it meets the prescribed RBI conditions, including net-worth, governance, technical and operational requirements.
7. Can a Company Operate a Prepaid Wallet Without RBI Approval?
An entity cannot operate a regulated PPI payment system without the required RBI approval or authorisation. However, closed-system instruments that meet the specific RBI definition are exempt from this authorisation requirement.
0 comments
Log in to leave a comment.
Be the first to comment.