
One in Three UK Adults Now Use Open Banking. What Does That Mean for Banks?
When open banking launched in the UK in January 2018, the country's nine largest banks had to start sharing account data and payment access with authorised third parties through APIs. For the first few years, most of the activity came from budgeting apps and lenders reading transaction histories. It was useful, but it hardly looked like a change in how people bank.
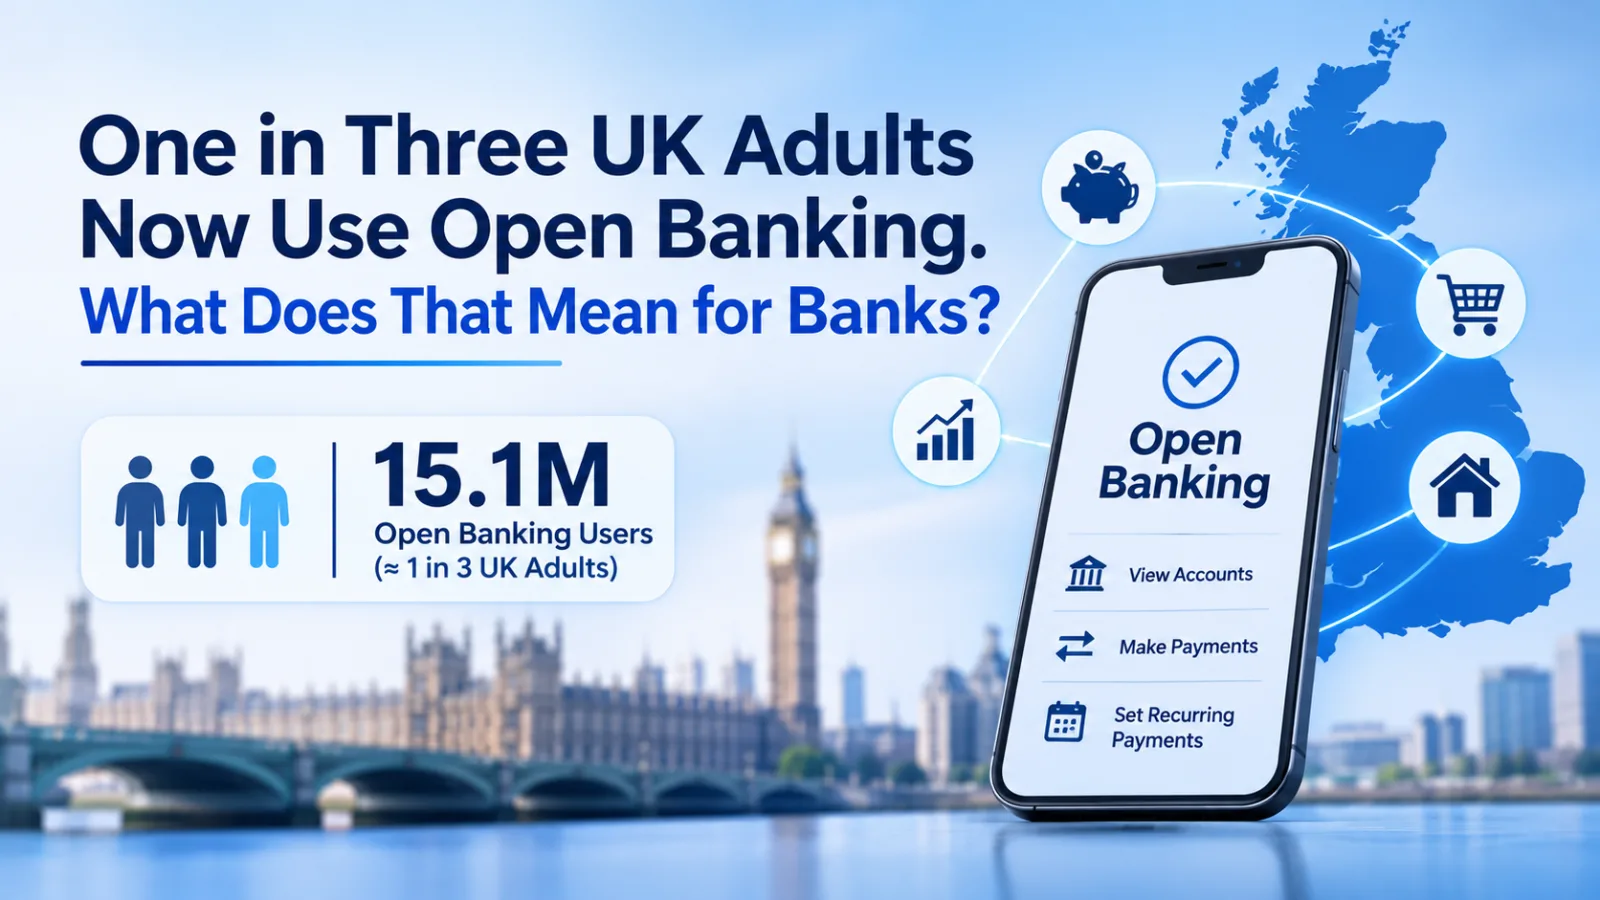
That picture has shifted. In July 2025, Open Banking Limited counted 15.1 million users, which it described as nearly one in three UK adults and a 34% rise in a single year. By July 2026, the ecosystem had passed one billion open banking payments and 100 billion API calls since launch.
Open Banking Limited counts users as connections to the brands that report them, not as unique individuals. So the true number of people is probably somewhat lower. Even so, the direction is hard to argue with.
From Reading Data to Moving Money
The more telling change is in what people use open banking for. In 2021, account information services made up 75% of users. By mid-2025, payment initiation users had become the majority, at 55%. In June 2026 alone, there were 40.16 million open banking payments, and variable recurring payments were growing month on month.
Variable recurring payments let a person give a provider permission to take payments within agreed limits, without approving each one. Today they are mostly used for moving money between a person's own accounts. Many in the industry expect them to compete with direct debits and stored card payments over time, though how quickly that happens is still an open question.
What this means is that money is increasingly leaving bank accounts on instructions that never pass through the bank's own app. A person might pay a utility bill, top up an investment account or move savings around without opening their banking app at all.
And yet the bank is still responsible for that account. It still carries much of the fraud risk, still handles the complaint when something goes wrong, and still has to answer the question "where did my money go?"
What Banks Need to Get Right
So how should a bank respond when it is no longer the only front door to its own accounts? A few areas stand out.
API performance now counts as service quality. In June 2026, the average provider response time for payment requests was 349 milliseconds. A bank whose APIs are slow or unreliable will see payments fail in someone else's app, and the person paying will usually blame the bank. The load is only growing, too. June 2026 saw 2.81 billion API calls, the highest monthly figure on record.
Consent needs to be visible. People should be able to see, in one place, which third parties can access their account and cancel that access easily.
Fraud monitoring has to cover account-to-account payments as closely as card payments, since open banking transactions move fast and leave little time to step in.
Banks can also use open banking themselves. Showing a person's accounts from other providers inside the bank's own app is one obvious example, and it gives the bank a fuller picture of that person's finances.
Good digital banking solutions treat all of this as one connected experience rather than a compliance project bolted on beside the app. The APIs, the consent screens, the fraud rules and the app itself have to work as a single system.
The Front Door Has Moved
Truth be told, most people using open banking don't know they are using it. They just know that paying a bill or linking an account was easy. For banks, the work is to make sure that holds up every time, including when the payment starts in an app they didn't build.
Author - Shefali Vasave
Shefali manages content marketing at Opus Technologies, a domain-native engineering partner for banks, payment providers, and fintechs, and writes on the various aspects of financial institutions navigating change in a real-time, digital-first world.
0 comments
Log in to leave a comment.
Be the first to comment.