
Loan Against Mutual Funds Online: What You Need to Know Before Applying
Learn how a loan against mutual funds online works, including eligibility, digital application steps, pledge process, costs, repayment and FAQs.
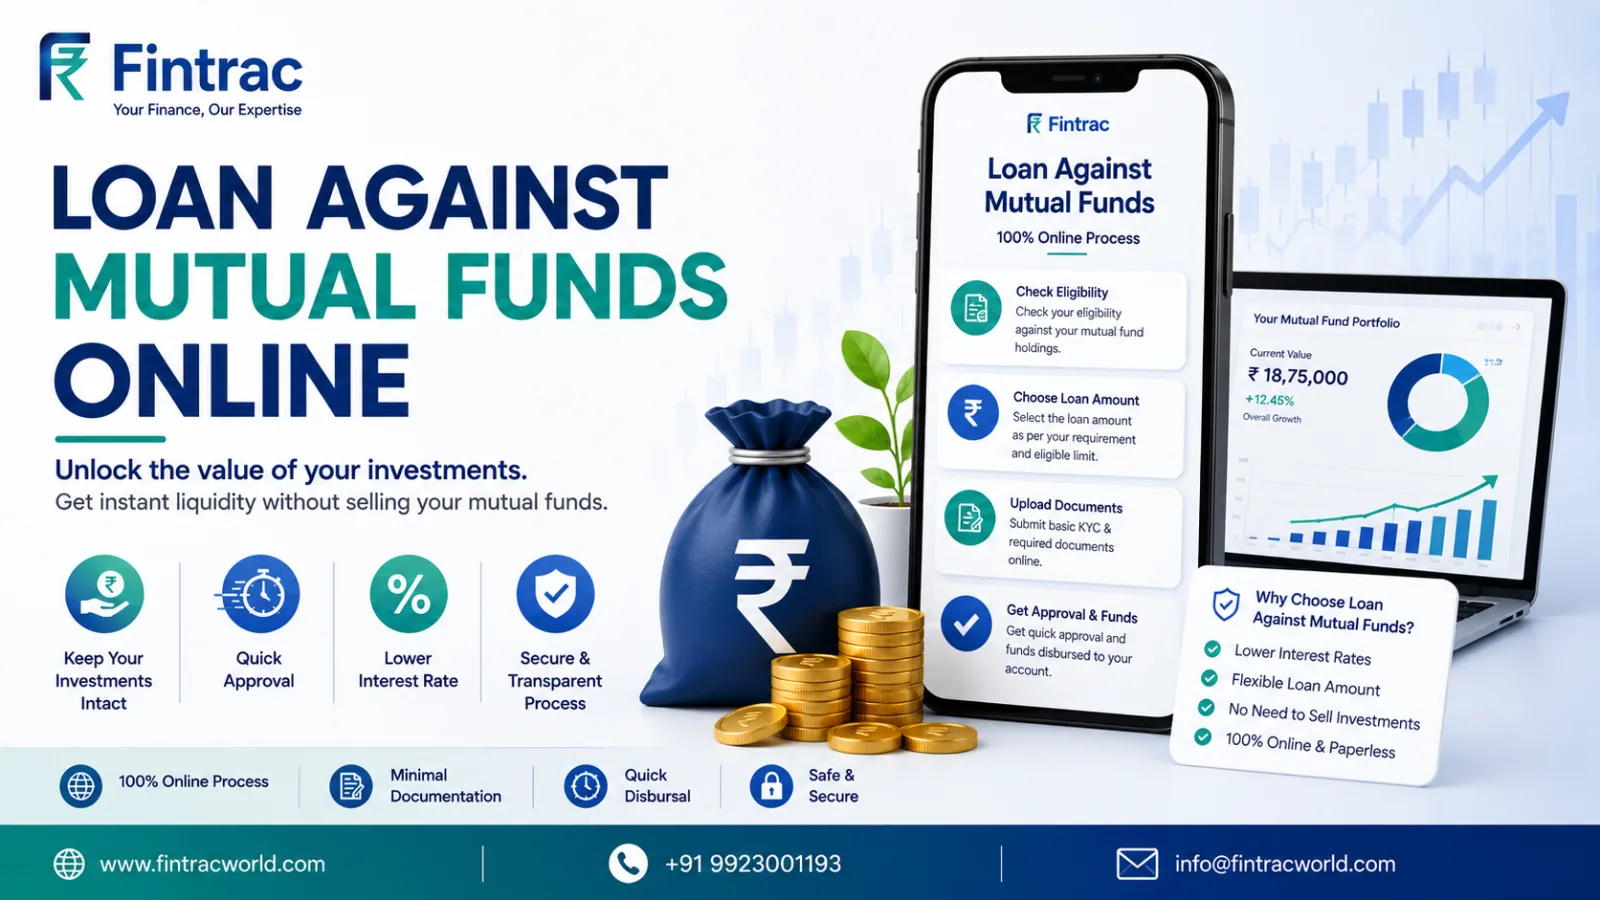
Managing a sudden financial requirement can be easier when you already have investments that may be used as security. Instead of immediately redeeming eligible mutual fund units, investors can explore a loan against mutual funds online through lenders that provide digital application facilities. Fintracworld helps readers understand how this type of borrowing works, what the online process may involve, and which details should be checked before submitting an application.
What Does Loan Against Mutual Funds Online Mean?
A loan against mutual funds is a secured borrowing facility in which eligible mutual fund units are pledged as security. The lender evaluates the eligible holdings and applicable loan-to-value criteria before determining the amount that may be offered.
The online part mainly refers to the application and documentation process. Depending on the lender, an applicant may be able to submit details, complete verification, provide required documents, and track the application digitally. SEBI documents describe the use of eligible mutual fund units as security for raising loans, subject to the conditions of the lending institution.
How Does the Online Process Usually Work?
The exact procedure can vary from one lender to another, but the journey generally involves several basic stages.
1. Check Your Eligibility
First, check whether your mutual fund units qualify for pledging and whether you meet the lender's requirements. Not every mutual fund or investment account will necessarily be accepted.
2. Provide Investment Details
The lender may require information about your mutual fund holdings, their current value, and the amount you want to borrow. This helps determine the available borrowing limit.
3. Complete Verification
Online applications may involve identity verification, financial information, investment verification, and other documentation required by the lender.
4. Pledge the Eligible Units
Once the loan is approved, the eligible units may be pledged or a lien may be marked according to the applicable process. SEBI-filed scheme documents explain that pledged units generally cannot be redeemed until the pledge or lien is released.
5. Receive the Loan
After completion of the required formalities and satisfaction of the lender's conditions, the approved amount can be disbursed according to the loan agreement.
Why Do Investors Explore an Online Option?
The digital route can make the initial application process more convenient. Instead of handling every step manually, some lenders allow borrowers to complete parts of the process through an online platform.
Convenient application from home
Digital submission of information and documents
Easier tracking of application status
Faster access to loan-related information
Ability to review terms before proceeding
However, convenience should not replace careful evaluation. The interest rate, processing charges, loan-to-value ratio, repayment schedule, and security conditions still matter.
What Should You Check Before Applying Online?
A quick online application should not mean a quick financial decision. Before accepting an offer, read the complete terms provided by the lender. Pay particular attention to:
Interest rate: Understand how much borrowing will cost.
Loan-to-value ratio: The loan amount may be only a percentage of the eligible investment value.
Processing charges: Check whether additional fees apply.
Repayment terms: Understand the instalment or repayment structure and due dates.
Pledge conditions: Know what happens to the mutual fund units while they remain pledged.
Default provisions: Review the lender's rights if repayment obligations are not met.
SEBI materials note that, depending on the applicable arrangement, a pledgee may have rights to invoke pledged securities if the loan is not repaid according to the agreement.
Does Online Mean Instant Approval?
Not necessarily. An online application can make the process more convenient, but approval still depends on eligibility, verification, eligible collateral, lender policies, and completion of the required formalities.
Therefore, borrowers should be careful with advertisements promising guaranteed approval or a specific loan amount without assessing the applicant's circumstances. Fintracworld offers educational information around mutual-fund-backed borrowing so readers can understand the important steps before exploring an online loan facility.
Online Loan or Mutual Fund Redemption?
If money is needed, an investor may consider either borrowing against eligible mutual funds or redeeming some units. These choices have different consequences. Redeeming units gives access to the investment proceeds but reduces the investment holding. Borrowing allows eligible units to remain pledged as security, but it creates an interest-bearing repayment obligation.
The suitable approach depends on the amount required, repayment capacity, investment objectives, and overall financial situation. Comparing the two options before acting can help avoid unnecessary costs.
Final Thoughts
A loan against mutual funds online can provide a digital route for investors who want to explore borrowing against eligible investments rather than immediately selling them. The convenience of an online application is useful, but understanding the interest rate, loan limit, fees, repayment obligations, and pledge conditions is equally important. Fintracworld can help readers learn about the process and key considerations so they can research their options more carefully before applying.
Frequently Asked Questions
Can I apply for a loan against mutual funds online?
Some lenders provide digital application facilities for loans secured against eligible mutual fund units. The exact online process depends on the lender.
Can every mutual fund be pledged online?
No. Eligibility depends on the lender's policies and the type of mutual fund units held.
Will I still own my mutual fund units after pledging them?
Generally, the investor remains the holder while the units are pledged, but the units are subject to the terms of the pledge. Redemption may be restricted until the pledge is released.
How much can I borrow against mutual funds?
The amount depends on factors such as the eligible investment value, type of mutual fund, applicable loan-to-value limit, and lender's terms.
What happens after I repay the loan?
Once the outstanding obligations are satisfied, the applicable pledge or lien release process can be completed according to the lender and depository/AMC procedures.
Is an online loan automatically cheaper?
No. Online processing may be convenient, but the interest rate and other charges depend on the lender and the specific loan terms. Compare the complete cost before proceeding.
0 comments
Log in to leave a comment.
Be the first to comment.