
Leather Chemicals Market Size, Trends, and Industry Analysis 2034
The leather chemicals market size was valued at USD 10.2 Billion in 2025, expected to reach USD 16.0 Billion at a CAGR of 4.98% during 2026-2034.
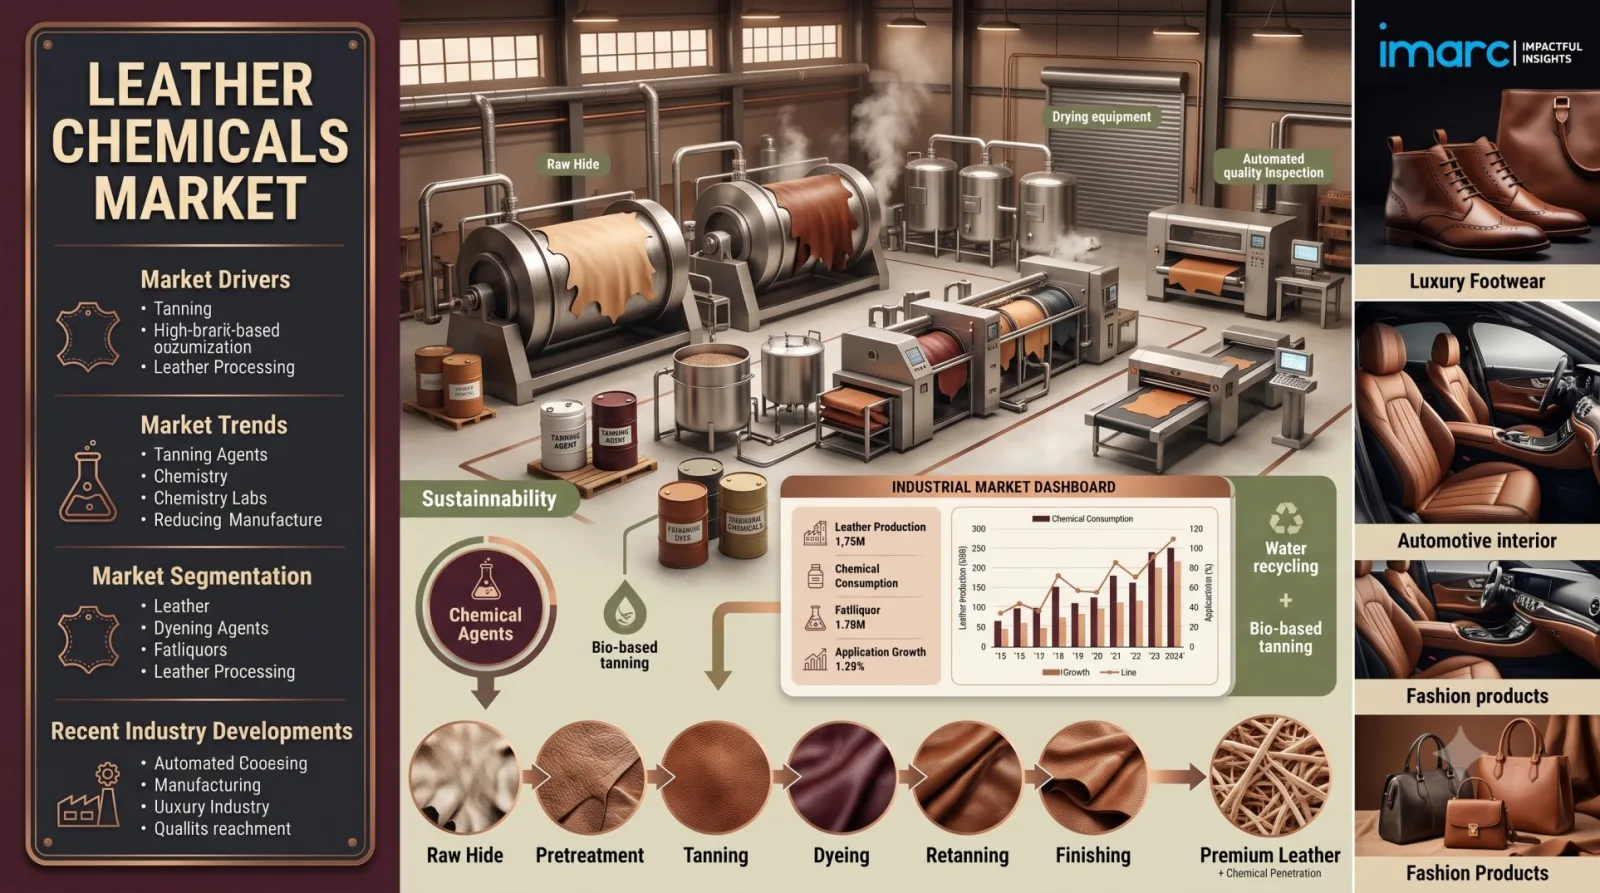
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the leather chemicals market. The global leather chemicals market size was valued at USD 10.2 Billion in 2025. Looking forward, IMARC Group estimates the market to reach USD 16.0 Billion by 2034, exhibiting a CAGR of 4.98% from 2026-2034, driven by rising demand for premium leather interiors in the automotive sector, sustained expansion of the footwear, fashion, and furniture industries, rapid advancements in leather processing technologies, and a growing preference for sustainable and eco-friendly leather production worldwide.
The market is experiencing steady growth momentum as tanneries and leather goods manufacturers increasingly depend on specialized chemistry to deliver durability, color consistency, softness, and surface performance across a widening range of end uses. Tanning, dyeing, and finishing chemicals transform raw hides into flexible, decomposition-resistant leather that meets the quality standards of automotive OEMs, footwear brands, luxury fashion houses, and furniture makers. At the same time, tightening environmental regulations on chromium, effluent discharge, and hazardous substances are pushing chemical suppliers to reformulate their portfolios toward chrome-free tanning agents, water-based finishing systems, and bio-based auxiliaries, positioning innovation and sustainability as the defining competitive levers in the industry.
How AI is Reshaping the Future of the Leather Chemicals Market
- AI-Driven Process Optimization and Chemical Dosing Control in Tanneries: Machine learning models connected to sensors in drums and processing vats are enabling tanneries to monitor pH, temperature, float ratio, and chemical uptake in real time, automatically adjusting the dosing of tanning, retanning, and dyeing agents to achieve consistent leather quality batch after batch, reducing chemical overuse, water consumption, and effluent load while helping tanners meet increasingly strict discharge norms in China, India, Vietnam, and Europe.
- Predictive Formulation Development and Faster Sustainable Product Innovation: Chemical manufacturers are applying AI-based formulation and simulation tools to screen thousands of candidate molecules and blend combinations for chrome-free tanning agents, water-based polyurethane finishes, and bio-based fatliquors, shortening laboratory development cycles and helping suppliers predict performance attributes such as abrasion resistance, color fastness, and low emissions before committing to pilot-scale trials, which accelerates the commercialization of greener alternatives demanded by automotive and fashion brands.
- Computer Vision for Leather Grading, Defect Detection, and Shade Matching: AI-powered vision systems are being deployed to grade hides, detect surface defects, and verify dye shade consistency at speeds and accuracy levels that manual inspection cannot match, enabling tanneries to optimize chemical selection for each hide quality tier, reduce rework and rejection rates, and deliver tightly matched color and finish specifications to automotive interior suppliers and premium footwear manufacturers operating under demanding quality thresholds.
Grab a sample PDF of this report: https://www.imarcgroup.com/leather-chemicals-market/requestsample
Leather Chemicals Market Trends and Drivers:
The global leather chemicals market is witnessing steady expansion, fueled by the convergence of rising automotive interior demand, a growing footwear and fashion industry, and an accelerating shift toward sustainable leather processing technologies. Leather remains a preferred material for vehicle interiors because of its durability, comfort, and aesthetic appeal, and leather chemicals play a decisive role in ensuring that automotive leather meets stringent standards for abrasion resistance, light fastness, low emissions, and tactile quality. The automotive industry continues to expand, particularly in emerging economies where a rising middle class and higher disposable incomes are lifting car ownership and the appetite for premium interior features. Approximately 85.4 million motor vehicles were produced worldwide in 2022, an increase of 5.7% over the previous year, and every additional premium vehicle programme translates into direct demand for tanning, dyeing, and finishing chemistry used in seats, steering wheels, and interior trim, with OEM specifications shaping the innovation pipelines of leading chemical suppliers.
The footwear industry represents the largest end-use pillar for leather chemicals and is reinforcing demand through a combination of fashion cycles, durability expectations, and the popularity of sports and outdoor activities. The global footwear market is anticipated to reach USD 332.3 Billion by 2032, and leather remains central to premium, formal, and performance footwear owing to its comfort, breathability, and long service life. A wide range of chemicals is used across tanning, dyeing, and finishing to deliver water resistance, flexibility, and a refined appearance that meets consumer expectations for style and quality. Participation in sports and outdoor activities is also rising, with the Sports and Fitness Industry Association reporting that 237 million people in the United States took part in at least one sport in 2022, a 9.2% increase from 2017, which is sustaining demand for specialty footwear that relies on leather and performance-enhancing chemical treatments.
The transition toward sustainable and compliant leather production is unlocking a new growth avenue for chemical suppliers, while the expansion of fashion and apparel adds a premium demand layer. Regulatory pressure on hexavalent chromium, with the European Union restricting chromium VI in leather articles to a maximum of 3 mg/kg under REACH, together with industry frameworks such as the Zero Discharge of Hazardous Chemicals programme, is encouraging tanneries to adopt chrome-free tanning, biodegradable retanning agents, and water-based coatings that lower environmental impact without sacrificing performance. Government support in leather-producing economies is amplifying this shift, with India's Union Budget 2025-26 announcing a Focus Product Scheme for the footwear and leather sectors expected to facilitate employment for 22 lakh people, generate a turnover of INR 4 lakh crore, and support exports of over INR 1.1 lakh crore, while India's per capita disposable income grew by 8% in FY24 and 13.3% in FY23, creating stronger demand for high-quality leather goods. High-end fashion brands continue to seek innovative leather treatments, finishes, and textures for exclusive collections, which drives the need for advanced chemical formulations offering diverse colors, feels, and finishes across handbags, garments, and accessories.
Leather Chemicals Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Chemical Type:
- Tanning and Dyeing Chemicals
- Beam House Chemicals
- Finishing Chemicals
Tanning and dyeing chemicals account for the largest chemical type segment, driven by their essential role in converting raw hides into durable, flexible leather, with chrome, vegetable, and synthetic tanning agents providing resistance to decomposition and improved physical properties, while dyeing chemicals impart the colors and aesthetic finishes required across automotive interiors, footwear, fashion, and furniture, supported by continuous advances in formulations that improve performance and environmental sustainability.
Breakup By Product:
- Biocides
- Surfactants
- Chromium Sulfate
- Polyurethane Resins
- Sodium Bicarbonate
- Others
Polyurethane resins hold the largest product share, supported by their high flexibility, abrasion resistance, and excellent adhesion, which make them indispensable in leather coatings, finishes, and adhesives as well as in the production of synthetic leather, with growing application across automotive, footwear, fashion, and furniture industries further strengthening their position as a versatile and durable material solution.
Breakup By End User:
- Footwear
- Furniture
- Automotive
- Textile
- Others
Footwear represents the leading end user segment, as shoe manufacturers extensively use leather chemicals across tanning, dyeing, and finishing to produce high-quality leather shoes, with rising disposable incomes, evolving fashion trends, and the popularity of sports and outdoor activities driving demand for products that enhance aesthetic appeal, improve resistance to wear and tear, and ensure a premium look and feel.
Breakup By Region:
- North America (United States, Canada)
- Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
- Europe (Germany, France, United Kingdom, Italy, Spain, Russia, Others)
- Latin America (Brazil, Mexico, Others)
- Middle East and Africa
Asia Pacific leads the global leather chemicals market with the largest regional share, owing to its robust leather manufacturing base and the presence of major producers and exporters of footwear, garments, and accessories, particularly in China, India, and Vietnam. The growth of the automotive and furniture industries across the region, combined with rising urbanization, increasing disposable incomes, and supportive government policies, is boosting consumption of high-quality leather and, in turn, the demand for tanning, dyeing, and finishing chemicals throughout the region.
Competitive Landscape:
The report provides a comprehensive analysis of the competitive landscape in the leather chemicals market with detailed profiles of all major companies, including:
- Abhilash Chemicals and Pharmaceuticals Pvt Ltd
- Balmer Lawrie & Co. Ltd.
- Buckman
- Chemtan Company, Inc.
- DyStar Singapore Pte Ltd
- Indofil Industries Limited
- Pidilite Industries Limited
- Schill + Seilacher GmbH
- Stahl Holdings B.V.
- Texapel
- TFL Group
- Zschimmer & Schwarz Chemie GmbH
Recent News and Developments in Leather Chemicals Market
- February 2026: LANXESS showcased its fungicides portfolio for the leather industry at the India International Leather Fair in Chennai, introducing the new Preventol CT 40 preservative for leather intermediates. Designed to protect against mold and fungi during storage and processing, the launch strengthens the company's position in the fast-growing Indian leather value chain.
- January 2026: Stahl completed the carve-out of its wet-end leather chemicals business, which now operates as an independent company named Muno under the majority ownership of Wendel. The move makes Stahl a pure-play specialty coatings formulator and reshapes the competitive structure of the global leather chemicals industry.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
About Us:
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: [email protected]
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104
0 comments
Log in to leave a comment.
Be the first to comment.