
How to Withdraw From Fidelity 401k Without a Penalty?
Withdraw From Fidelity 401k
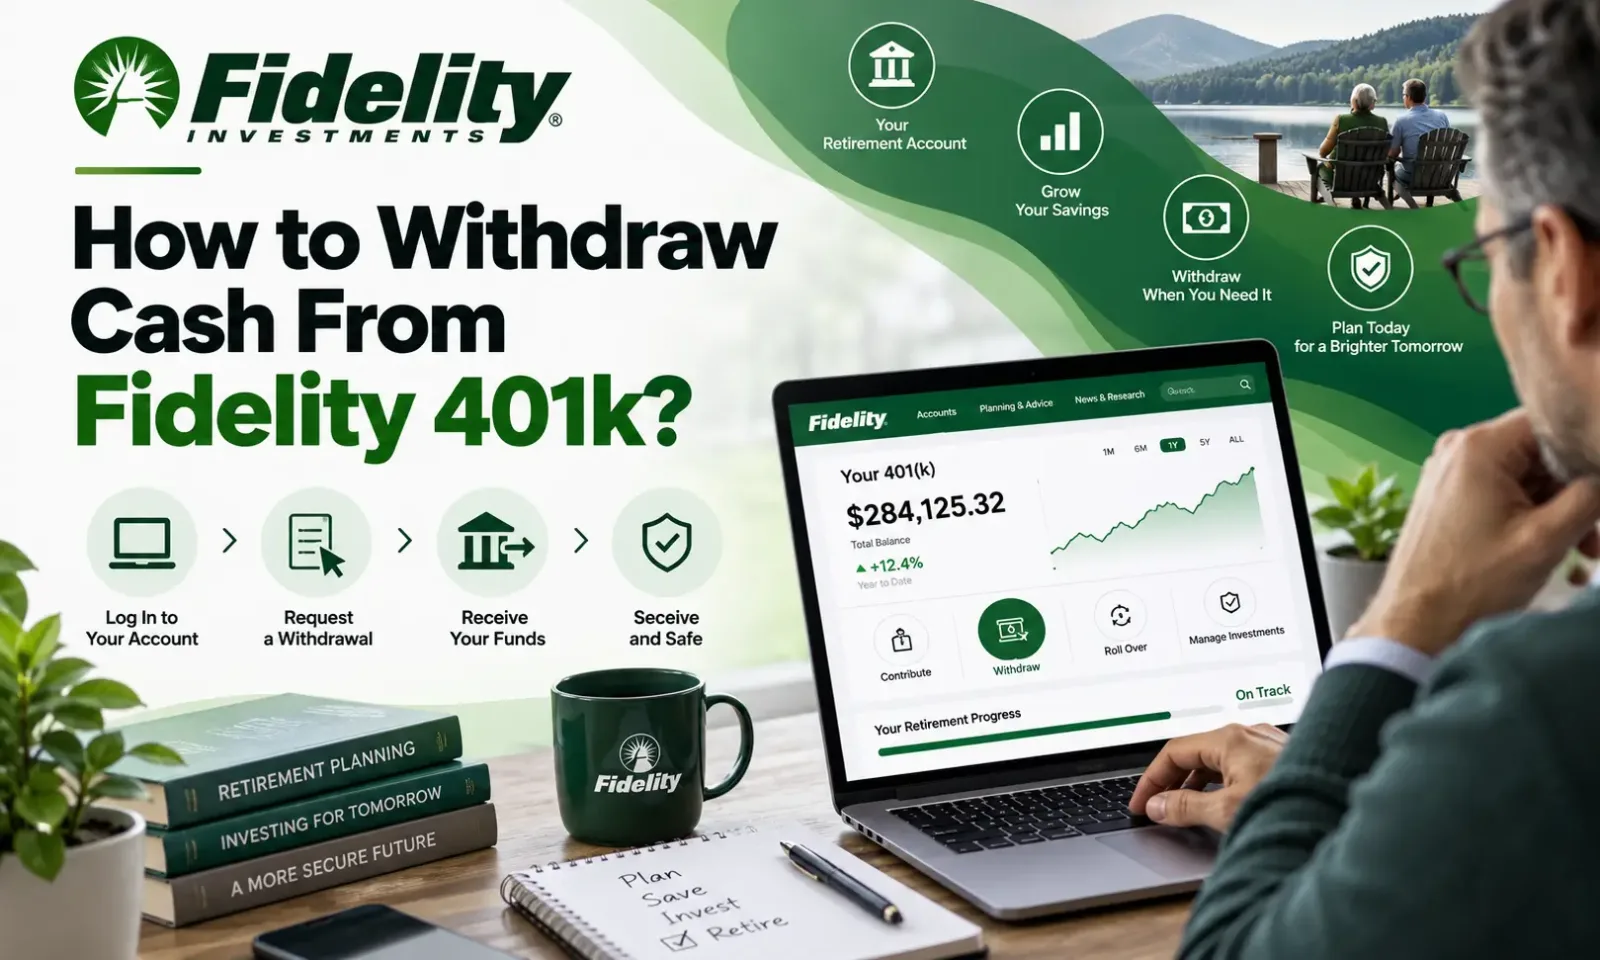
Withdrawing money from your retirement savings can be a difficult decision, especially when you are concerned about taxes and penalties. Whether you have recently left your job, are approaching retirement, or need money for an unexpected expense, understanding the Fidelity 401k withdrawal rules can help you make a more informed decision.
Many people ask, "How do I withdraw money from Fidelity without paying a penalty?" The answer depends on several factors, including your age, employment status, retirement plan rules, and reason for withdrawing.
Generally, taking money from a traditional 401(k) before age 59½ may result in a 10% early withdrawal tax in addition to ordinary income taxes. However, certain situations qualify for exceptions.
This guide explains how to withdraw from Fidelity 401k without a penalty, how online withdrawals work, what happens after leaving an employer, and which alternatives may protect your retirement savings.
Understanding these options before requesting a withdrawal can help you avoid unnecessary expenses and preserve more money for the future.
What Is a Fidelity 401k Withdrawal?
A Fidelity 401k withdrawal is the process of taking money out of a retirement account administered by Fidelity Investments. A 401(k) is an employer-sponsored retirement savings plan that allows eligible employees to contribute part of their earnings toward retirement.
Traditional 401(k) contributions are generally made before income taxes are paid. Investments may grow tax-deferred until the money is withdrawn.
A Fidelity Investments 401k withdrawal may be available under different circumstances, including retirement, separation from employment, financial hardship, or other events permitted by the plan.
The most common withdrawal options include:
Retirement withdrawals after reaching the eligible age.
Early withdrawals that meet IRS penalty exceptions.
Hardship withdrawals for qualifying financial needs.
Withdrawals after leaving an employer.
Required minimum distributions at the applicable age.
Distributions associated with eligible retirement account rollovers.
Not every option is available under every employer's plan. Fidelity may administer the account, but the employer's plan document determines which distributions and loans are permitted.
Before requesting money, review your plan's withdrawal eligibility, tax treatment, and distribution procedures.
Can You Withdraw From Fidelity 401k Without a Penalty?
Yes. You may be able to withdraw money from a Fidelity 401(k) without paying the additional 10% early withdrawal tax if you meet a qualifying IRS exception.
The most straightforward option is waiting until age 59½. However, younger account holders may also qualify in certain situations.
It is important to understand that avoiding an early withdrawal penalty does not automatically mean avoiding income taxes.
For example, someone who withdraws $20,000 from a traditional 401(k) after age 59½ generally avoids the additional 10% early withdrawal tax. However, the taxable amount is usually included in their ordinary income for that year.
The IRS recognizes several exceptions, including qualifying disabilities, certain medical expenses, some emergency distributions, and qualifying separation from employment.
Understanding the 10% Early Withdrawal Penalty
Generally, if you withdraw taxable money from your 401(k) before reaching age 59½ and no exception applies, the IRS imposes an additional 10% tax.
Consider this example:
You are 45 years old and withdraw $15,000 from a traditional Fidelity 401(k).
Your potential federal tax consequences may include:
Withdrawal amount: $15,000
Additional early withdrawal tax: $1,500
Federal ordinary income tax: Depends on your taxable income and tax bracket
State income tax: May apply depending on your state
The $1,500 additional tax is separate from ordinary income tax.
Planning carefully before requesting an early withdrawal can help you understand the total cost.
How to Withdraw From Fidelity 401k Without a Penalty: 7 Options
There are several circumstances in which you may be eligible to avoid the additional 10% early withdrawal tax.
1. Withdraw After Reaching Age 59½
One of the simplest ways to avoid the early withdrawal penalty is to wait until age 59½.
At this age, eligible distributions from a traditional 401(k) are no longer subject to the additional 10% early withdrawal tax.
However, if you are still working, your employer's plan may restrict access to certain funds until you retire or experience another qualifying event.
If your plan permits withdrawals, you can review your options through Fidelity NetBenefits.
You may be able to request a partial withdrawal, a lump-sum distribution, or another distribution arrangement supported by your plan.
The withdrawn money generally remains subject to ordinary income tax unless it qualifies for different tax treatment.
2. Use the Rule of 55 After Leaving Your Job
The Rule of 55 is an important exception for employees who separate from service during or after the calendar year in which they turn 55.
Under this IRS rule, qualifying distributions from the employer's retirement plan may avoid the additional 10% early withdrawal tax.
For example, imagine you leave your employer in the year you turn 56.
If you have money in that employer's 401(k), distributions from the qualifying plan may be penalty-free under the Rule of 55.
However, several conditions apply.
The exception generally applies to the eligible employer plan associated with your separation from service. It does not automatically apply to an IRA or an unrelated former employer's plan.
If you transfer your 401(k) into an IRA before using this exception, the Rule of 55 generally will not apply to distributions from that IRA.
For this reason, people considering a Fidelity 401k withdrawal after leaving an employer should carefully evaluate their options before initiating a rollover.
3. Qualify for a Disability Exception
The IRS provides a penalty exception for distributions made because of a qualifying total and permanent disability.
If you meet the applicable disability requirements, you may be able to access retirement funds before age 59½ without paying the additional 10% tax.
You may need appropriate documentation to support the exception.
The distribution may still be taxable as ordinary income.
4. Use the Exception for Certain Medical Expenses
Some early withdrawals may qualify for an exception when the money is used for eligible unreimbursed medical expenses.
The exception is limited to qualifying medical expenses exceeding 7.5% of your adjusted gross income.
For example, if your adjusted gross income is $60,000, the 7.5% threshold is $4,500.
Eligible unreimbursed expenses above that threshold may qualify for the penalty exception, subject to applicable requirements.
Importantly, this exception does not automatically make your entire withdrawal penalty-free.
Review the medical expense rules carefully before requesting a distribution.
5. Consider Substantially Equal Periodic Payments
Substantially Equal Periodic Payments, commonly called SEPP or 72(t) payments, may allow eligible individuals to access retirement money before age 59½ without the additional early withdrawal tax.
This strategy involves taking a series of withdrawals calculated using an IRS-approved method.
For qualified employer plans, payments generally must begin after separation from service.
Once started, the payment schedule must generally continue for at least five years or until reaching age 59½, whichever period is longer.
Changing or stopping the payments too early may result in retroactive additional taxes and interest.
Because the calculations and restrictions are complicated, professional tax guidance is especially useful before establishing this arrangement.
6. Check Eligibility for Emergency Expense Distributions
Federal law provides a limited penalty exception for certain emergency personal expense distributions.
Generally, an eligible person may take one qualifying distribution per calendar year, up to the lesser of $1,000 or the amount by which their vested account balance exceeds $1,000.
Specific repayment and subsequent distribution restrictions apply.
However, the employer's plan is not necessarily required to offer this type of distribution. Confirm availability and eligibility with the plan administrator before relying on the exception.
Other specialized exceptions may apply to certain qualifying disaster situations, birth or adoption expenses, terminal illness, or domestic abuse victim distributions.
7. Consider a Direct Rollover Instead of Cashing Out
A direct rollover is not a cash withdrawal for personal spending, but it can help you move eligible retirement savings without triggering immediate federal income taxes or the early withdrawal penalty.
If you have left your employer, you may be able to transfer eligible funds to a traditional IRA or another qualified retirement plan.
With a properly executed direct rollover, the money moves between eligible retirement accounts rather than being paid to you.
This allows you to preserve the tax-deferred status of eligible funds.
However, moving money into an IRA can affect certain withdrawal exceptions, especially the Rule of 55.
A rollover may be an attractive option when you do not need immediate access to the money and want to maintain your retirement savings.
How to Withdraw Money From Fidelity 401k Online
Many account holders prefer requesting a Fidelity 401k withdrawal online because it allows them to review account information and available distribution options.
Fidelity provides its NetBenefits platform for many workplace retirement plans.
Here is a general process.
Step 1: Sign in to Fidelity NetBenefits
Visit the official Fidelity NetBenefits website and securely sign in.
Use your authorized account credentials and any required verification method.
After signing in, locate your workplace retirement account.
Step 2: Select Your 401(k) Account
Choose the appropriate employer-sponsored retirement plan.
Review your account balance, vested balance, and employment information.
Your total account balance may differ from the amount currently available for withdrawal.
Step 3: Review Loans and Withdrawal Options
Look for a section labeled Loans, Rollovers, and Withdrawals or similar wording.
The exact options depend on your employer's retirement plan.
Fidelity directs eligible workplace plan participants to NetBenefits to review available loans, withdrawal amounts, and distribution options.
Step 4: Choose the Appropriate Distribution Type
Your available choices may include a retirement withdrawal, hardship distribution, post-employment distribution, or other permitted withdrawal.
Choose the type that accurately matches your circumstances.
Do not select a hardship or other exception merely because you want to avoid taxes. You must satisfy the applicable rules.
Step 5: Enter the Withdrawal Amount
Specify how much money you want to withdraw.
Review any limitations, required documentation, tax withholding, and potential charges.
If you only need part of your savings, consider whether a smaller withdrawal would better preserve your retirement funds.
Step 6: Review Payment and Tax Information
Depending on the plan, you may be able to choose an available payment method, such as an electronic transfer or mailed check.
Verify your payment information and review the federal and state tax withholding disclosures.
Tax withholding does not necessarily cover your full tax liability.
Step 7: Submit and Track Your Request
Review the details before submitting your withdrawal request.
Once submitted, monitor its progress through your Fidelity account.
Processing times vary depending on plan requirements, verification, payment method, and whether supporting documentation is needed.
If you cannot find an available withdrawal option, contact the official Fidelity workplace retirement support service through your signed-in account.
Fidelity 401k Withdrawal After Leaving Your Employer
Leaving a job is one of the most common reasons people investigate withdrawing money from a retirement account.
If you have recently changed jobs or become unemployed, you may be wondering how to withdraw money from Fidelity 401k after leaving your job.
In many situations, separating from an employer makes your vested retirement savings eligible for distribution.
However, eligibility to receive a distribution and eligibility to avoid an early withdrawal penalty are two different matters.
Option 1: Keep Money in Your Former Employer's Plan
Some employer-sponsored retirement plans allow former employees to keep their savings in the plan, subject to applicable plan rules and minimum balance requirements.
This option may allow investments to continue growing on a tax-deferred basis.
It may also preserve access to the Rule of 55 if you otherwise qualify.
Review investment options, account fees, and plan restrictions before deciding.
Option 2: Roll Over Your 401(k) to an IRA
An eligible direct rollover can transfer money from your former employer's 401(k) into a traditional IRA without immediate federal income tax.
This may provide additional investment choices and allow you to consolidate retirement accounts.
However, withdrawals from the IRA will be governed by IRA rules rather than the former employer plan's withdrawal rules.
Option 3: Transfer Your Savings to a New Employer's Plan
If your new employer's retirement plan accepts rollovers, you may be able to transfer eligible savings into that plan.
A direct rollover generally avoids immediate tax on the transferred pretax amount.
This approach may simplify retirement account management.
Option 4: Request a Cash Distribution
You may be able to request a cash distribution of eligible funds after leaving your job.
However, a cash withdrawal before age 59½ may trigger the additional 10% early withdrawal tax unless an exception applies.
Ordinary income taxes may also apply.
Before withdrawing, compare the potential immediate financial benefit with the long-term effect on your retirement savings.
How to Close a Fidelity 401k Account After Leaving a Job
Some people want to close their old 401(k) account after leaving an employer.
Closing an account generally requires moving or distributing the eligible remaining balance, subject to outstanding loans, plan requirements, and any other restrictions.
You can begin by reviewing the account in NetBenefits.
Determine whether your preferred option is a direct rollover, transfer to an eligible employer plan, or cash distribution.
If you request a full cash distribution, the account may be closed after all applicable transactions are completed.
Keep in mind that closing a retirement account does not eliminate any taxes or penalties owed on distributions.
A direct rollover may help you consolidate eligible savings without creating an immediate taxable cash-out.
Fidelity 401k Early Withdrawal: Rules and Consequences
A Fidelity 401k early withdrawal generally refers to taking retirement money before reaching age 59½.
Although early withdrawals can provide access to needed funds, they can also create significant long-term consequences.
Income Taxes and Additional Taxes
Taxable traditional 401(k) distributions are generally included in ordinary income.
If you do not qualify for an early withdrawal exception, an additional 10% federal tax may apply.
For instance, consider a $25,000 early withdrawal.
If the entire amount is taxable and no exception applies, the additional federal early withdrawal tax would be $2,500.
Ordinary income taxes and any applicable state taxes would be separate.
Lost Retirement Growth
Another consequence is the potential loss of future investment growth.
Money withdrawn today is no longer invested in your 401(k).
For example, if $20,000 remained invested for 20 years and earned a hypothetical annual return of 6%, it could grow to approximately $64,000.
Actual investment returns are not guaranteed, but the example illustrates why early withdrawals can affect long-term retirement goals.
Reduced Retirement Security
Taking money out early can reduce the savings available when you eventually stop working.
If you must withdraw funds, consider how you will rebuild your retirement savings afterward.
Fidelity 401k Hardship Withdrawal: Can You Avoid a Penalty?
A Fidelity 401 (k) hardship withdrawal may be available if you experience an immediate and heavy financial need recognized under your employer's plan.
Common qualifying circumstances may include:
Certain medical expenses.
Costs directly related to purchasing a primary residence.
Qualifying higher education expenses.
Expenses necessary to prevent eviction or foreclosure.
Certain funeral or burial expenses.
Eligible repairs to a primary residence.
Certain disaster-related financial needs.
The amount generally must be limited to what is necessary to address the qualifying financial need.
However, a hardship withdrawal does not automatically qualify for an exception to the 10% early withdrawal tax.
If you are younger than 59½, your hardship distribution may still be subject to the additional tax unless you independently qualify for an IRS exception.
Hardship withdrawals also cannot be rolled over and generally cannot be repaid to the plan.
How to Request a Fidelity Hardship Withdrawal
Sign in to your Fidelity workplace retirement account and review the available withdrawal options.
If hardship distributions are permitted, follow the instructions provided.
You may need to describe your financial circumstances and provide documentation or required certifications.
The employer's plan administrator determines whether the request satisfies the plan's hardship distribution rules.
Before submitting, evaluate the likely income tax consequences and whether another option would better suit your needs.
Fidelity First-Time Home Buyer 401k Withdrawal Rules
Buying your first home is an important financial milestone. Some people consider using retirement savings to cover a down payment or other housing expenses.
However, the rules for 401(k) withdrawals and IRA withdrawals are different.
Does a First-Time Home Purchase Avoid the 401(k) Penalty?
Not automatically.
A first-time home purchase does not qualify for the special $10,000 first-time homebuyer early withdrawal penalty exception when funds are distributed directly from a 401(k).
That specific exception applies to eligible IRA distributions.
Some 401(k) plans may allow hardship withdrawals for costs directly associated with purchasing a primary residence, but hardship approval alone does not remove the early withdrawal tax.
This distinction is especially important for anyone researching Fidelity 401k withdrawal first-time home buyer options.
Could an IRA Provide Another Option?
Eligible first-time homebuyers may qualify for an IRA early withdrawal penalty exception of up to $10,000 over their lifetime.
Specific requirements apply, and ordinary income taxes may still be owed on traditional IRA distributions.
Rolling a 401(k) into an IRA solely to access this exception requires careful consideration of rollover eligibility, timing, tax consequences, and the withdrawal rules.
Speak with a qualified tax professional before moving retirement funds for a home purchase.
Fidelity 401k Loan vs. Withdrawal: Which Is Better?
If you are still employed and need access to money, a 401(k) loan may be worth considering.
Unlike a permanent withdrawal, a properly structured retirement plan loan allows you to borrow from your vested account balance and repay the money over time.
Whether this option is available depends on your employer's plan.
A qualifying loan generally does not create immediate federal income tax or the additional 10% early withdrawal tax.
However, a loan carries responsibilities.
You must follow the repayment schedule, and a default can result in a taxable distribution.
Generally, the maximum permitted loan is based on your vested balance and applicable federal limits, commonly up to 50% of the vested balance or $50,000, whichever is less, with certain exceptions and adjustments.
Most plan loans must be repaid within five years, although qualifying loans used to purchase a principal residence may allow longer repayment periods.
When a 401(k) Loan May Be Worth Considering
A loan may be suitable for someone with a temporary financial need who has stable income and can comfortably meet the repayment obligations.
However, borrowing from retirement savings may reduce investment growth and create risks if you leave your employer.
Fidelity recommends reviewing other available funding options before borrowing or withdrawing retirement money.
Fidelity Individual 401k and Self-Employed 401k Withdrawal Rules
Fidelity also offers retirement account services for eligible self-employed individuals and small-business owners.
A Fidelity Individual 401k, sometimes called a solo 401(k) or self-employed 401(k), is designed for eligible business owners without employees other than a spouse.
These plans have retirement distribution rules that share many similarities with traditional employer-sponsored 401(k) plans.
However, the available features and distribution procedures may differ.
Can You Withdraw From a Fidelity Individual 401(k) Before Retirement?
Withdrawals generally depend on the plan's terms and qualifying distribution events.
A self-employed individual may be eligible for distributions after reaching the applicable age, experiencing certain qualifying events, or satisfying other distribution conditions.
The additional 10% early withdrawal tax may apply if the individual is younger than 59½ and no exception applies.
How Do Personal 401(k) Withdrawals Work?
If you have a personal 401(k) through Fidelity, review the specific plan documents and account procedures before requesting a distribution.
Some individual retirement arrangements require different forms or administrative steps than employer-sponsored plans accessed through NetBenefits.
Confirm eligibility, tax treatment, and the available payment methods before proceeding.
Fidelity IRA Withdrawal vs. Fidelity 401k Withdrawal
Although both IRAs and 401(k) plans are retirement savings accounts, their withdrawal rules differ in important ways.
A Fidelity IRA withdrawal may provide more flexibility in accessing funds, but early withdrawals can still trigger taxes and penalties.
Some exceptions apply specifically to IRAs, while others apply only to employer-sponsored retirement plans.
For example, the qualified first-time homebuyer exception generally applies to IRA distributions rather than 401(k) distributions.
Conversely, the Rule of 55 generally applies to eligible employer retirement plans rather than IRAs.
Traditional IRA withdrawals are usually taxable when they come from pretax funds, unless a special tax treatment applies.
Roth IRA withdrawals follow separate ordering rules. Regular Roth IRA contributions can generally be withdrawn tax-free and penalty-free, while earnings may be subject to additional conditions.
Understanding these differences can help you avoid costly mistakes when moving retirement savings between accounts.
Common Fidelity 401k Withdrawal Mistakes to Avoid
Even when you qualify to withdraw retirement savings, making the wrong decision can result in unnecessary expenses.
Withdrawing Without Checking Your Eligibility
Before requesting money, confirm whether you satisfy the relevant age, employment, or other withdrawal requirements.
Being able to access money does not necessarily mean the distribution will be penalty-free.
Confusing Penalty-Free With Tax-Free
A penalty exception usually removes the additional 10% early withdrawal tax.
It does not automatically eliminate ordinary income tax on traditional 401(k) distributions.
Rolling Over Money Before Reviewing the Rule of 55
If you qualify for the Rule of 55, rolling your entire former employer's 401(k) into an IRA could eliminate access to that specific exception for the transferred money.
Review your immediate and future withdrawal needs before making the transfer.
Assuming Hardship Withdrawals Have No Penalty
Hardship eligibility and early withdrawal tax exceptions are separate requirements.
Some hardship distributions remain subject to the additional 10% tax.
Withdrawing More Than Necessary
Taking a larger distribution than you need may increase taxable income and reduce your future retirement savings.
Estimate the actual amount required before requesting funds.
Ignoring Tax Documentation
Retirement distributions are generally reported on Form 1099-R.
Keep your records and review whether you must file Form 5329 to report an early distribution tax or claim an applicable exception.
The IRS explains that Form 5329 may be needed when your Form 1099-R does not properly reflect an exception.
How to Choose the Best Fidelity 401k Withdrawal Option
The right strategy depends on your circumstances.
If you are age 59½ or older, an eligible retirement distribution may allow you to access money without the additional early withdrawal tax.
If you left your employer at age 55 or later, the Rule of 55 may offer additional flexibility.
If you need money while still employed, a 401(k) loan may be worth evaluating if your plan permits it.
If you do not need immediate cash, a direct rollover may help you maintain the tax advantages of retirement savings.
Before making a decision, consider:
Your current age and employment status.
Whether you qualify for an IRS penalty exception.
Your total expected federal and state tax liability.
Your emergency savings and other financial resources.
Whether your employer's plan permits the requested transaction.
How the withdrawal may affect your retirement goals.
For assistance with your specific Fidelity account, use the official Fidelity Investments website or NetBenefits.
You may also consider working with a qualified financial advisor or tax professional to review your options.
Frequently Asked Questions About Fidelity 401k Withdrawal
1. How Do I Withdraw Money From Fidelity 401k Without a Penalty?
You may avoid the additional 10% early withdrawal tax if you are at least age 59½ or qualify for an applicable IRS exception. Examples include certain qualifying withdrawals after separation from service in or after the year you turn 55, qualifying disability, and certain medical expense distributions. Your employer's plan must also permit the distribution.
2. Can I Withdraw Money From Fidelity 401k Before Retirement?
Yes, in certain circumstances. Your employer's plan may allow eligible early distributions, hardship withdrawals, or loans. However, early cash withdrawals may trigger ordinary income taxes and an additional 10% tax unless an exception applies.
3. How Can I Withdraw Money From Fidelity 401k After Leaving My Job?
Sign in to NetBenefits, select your former employer's retirement plan, and review the available distribution and rollover options. Depending on the plan, you may be able to request a cash distribution or a direct rollover. Review your tax consequences before submitting the request.
4. Can I Take a Fidelity 401k Hardship Withdrawal Without Paying a Penalty?
Possibly, but hardship status alone does not remove the additional 10% early withdrawal tax. You must qualify for a separate IRS exception or be at least age 59½ to avoid that additional tax. Ordinary income tax may still apply.
5. How Long Does a Fidelity 401k Withdrawal Take?
Processing time varies based on the employer's retirement plan, type of distribution, verification requirements, and payment method. Check NetBenefits for the status and any estimated processing information provided for your request.
6. Can I Roll Over My Fidelity 401k Without Paying Taxes or Penalties?
An eligible direct rollover from a traditional Fidelity 401(k) into a traditional IRA or another eligible pretax retirement plan generally avoids immediate federal income tax and the additional early withdrawal tax. Roth conversions and other arrangements may have different tax consequences.
7. Can I Withdraw From Fidelity 401k to Buy My First Home Without a Penalty?
A first-time home purchase by itself does not qualify a direct 401(k) distribution for the special first-time homebuyer penalty exception. That exception generally applies to eligible IRA withdrawals, subject to a $10,000 lifetime limit. Your 401(k) may offer a home-purchase hardship distribution, but the additional tax could still apply.
Conclusion
Understanding how to withdraw from Fidelity 401k without a penalty can help you protect your retirement savings while managing important financial needs.
Although the IRS generally imposes an additional 10% tax on taxable retirement distributions taken before age 59½, several exceptions may provide relief. These include qualifying distributions after reaching the appropriate age, the Rule of 55, certain disability and medical expense situations, and other specific circumstances.
If you have left your employer, compare cash withdrawals with direct rollovers and the option to keep money in your existing retirement plan. If you are still employed, determine whether an eligible plan loan or another source of funding might be more appropriate.
Remember that avoiding the early withdrawal penalty does not necessarily mean avoiding income taxes.
Before submitting a Fidelity 401k withdrawal request, review your plan documents, confirm the applicable IRS requirements, and understand the long-term impact on your savings.
Your next step: Sign in to Fidelity NetBenefits, review your eligible withdrawal options, and confirm the tax implications before making a final decision.
0 comments
Log in to leave a comment.
Be the first to comment.