
How to Choose the Right Bill Discounting Platform for Your Business
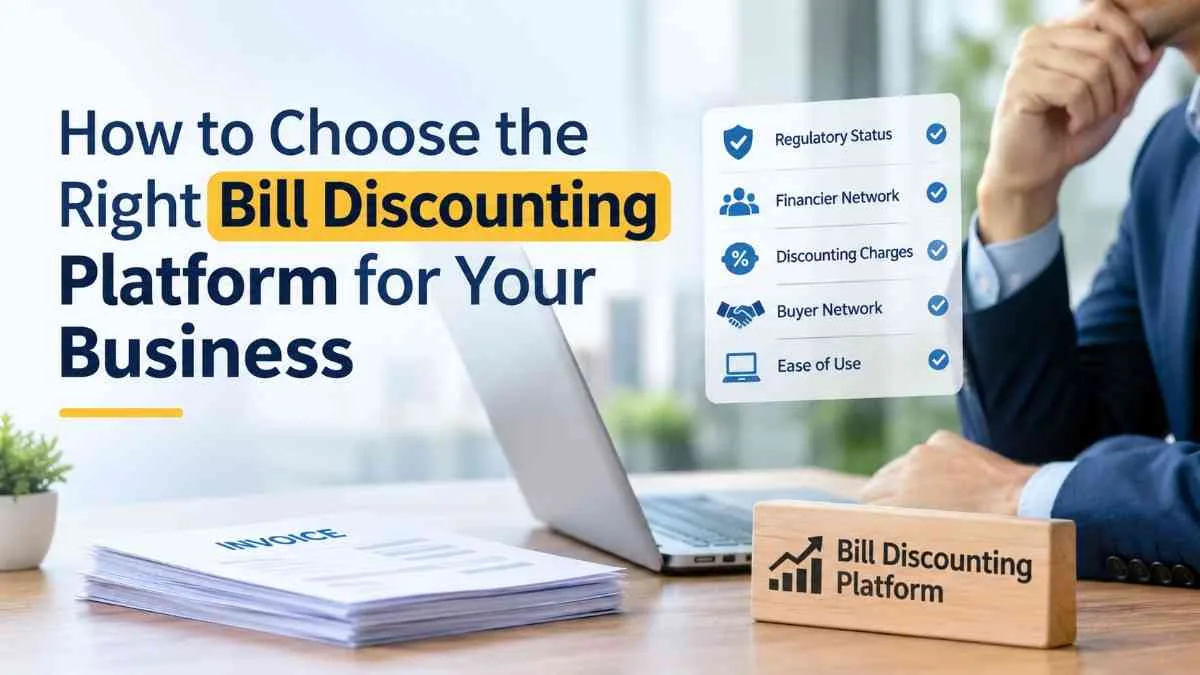
Managing cash flow is one of the biggest challenges for businesses that sell goods or services on credit. Companies often have to wait 30, 60 or even 90 days for customers to clear their invoices. During this period, they still need funds to pay suppliers, manage daily operations, purchase raw materials and meet other business expenses.
Bill discounting offers a way to access funds against unpaid invoices without waiting for the payment due date. By using a bill discounting platform, businesses can get their invoices financed by banks, financial institutions or other eligible financiers.
However, choosing the right platform requires more than comparing discounting rates. Businesses need to consider the platform's credibility, financing options, transaction process, transparency and suitability for their working capital requirements.
This blog explains the key factors businesses should evaluate before selecting a bill discounting platform.
What Is a Bill Discounting Platform?
A bill discounting platform is a digital marketplace or financial service that helps businesses convert their unpaid invoices into immediate working capital. Instead of waiting for customers to make payments, a business can submit eligible invoices to a financier and receive funds after deducting the applicable discounting charges.
For example, suppose a business raises an invoice worth ₹10 lakh with a payment term of 60 days. Rather than waiting two months for the buyer to release the payment, the seller can approach a bill discounting platform to get the invoice financed.
The financier evaluates the invoice and the parties involved before offering funding. Once approved, the seller receives the financed amount after applicable charges. The outstanding invoice is then settled according to the agreed payment terms.
Bill discounting platforms simplify this process by bringing businesses and financiers together through a digital interface.
8 Factors to Consider When Choosing a Bill Discounting Platform
Not every bill discounting platform offers the same features, financing options or transaction experience. Before registering, businesses should assess the following factors.
1. Check the Platform's Credibility and Regulatory Framework
The first step is to understand who operates the platform and what regulatory framework it follows. Businesses should prioritise platforms backed by established financial institutions and operating under the applicable regulatory guidelines.
In India, Trade Receivables Discounting System (TReDS) platforms provide a regulated framework for financing trade receivables of eligible MSMEs. These platforms connect MSME sellers, corporate buyers and financiers to facilitate invoice discounting.
Before choosing a platform, check:
Whether the platform operates under the applicable regulatory framework.
The credibility of its promoters and operating institution.
The banks and financial institutions participating on the platform.
Its transaction security and data protection practices.
Its track record in facilitating invoice financing.
A credible platform reduces uncertainty and gives businesses greater confidence when handling financial transactions.
2. Evaluate the Network of Banks and Financiers
The availability of financiers directly influences the financing opportunities businesses can access.
A platform connected with multiple banks and financial institutions gives sellers more opportunities to receive competitive bids for their invoices. When several financiers participate in the discounting process, businesses may have greater flexibility in selecting suitable financing offers.
Before making a decision, find out:
How many banks and financial institutions participate?
Are established public and private sector banks available?
Can multiple financiers bid on the same invoice?
Does the platform provide access to different financing options?
A wider financier network can improve competition and provide businesses with more choices when arranging working capital.
3. Compare Discounting Rates and Other Charges
The cost of financing is an important consideration when selecting a bill discounting platform. However, businesses should not evaluate platforms based on the interest or discounting rate alone.
The total cost may include discounting charges, transaction fees and other applicable expenses. These costs can vary depending on the financier, invoice maturity period, buyer's creditworthiness and transaction structure.
For instance, an invoice with a 30-day payment period may attract a different discounting cost from an invoice with a 90-day payment period.
Businesses should compare:
Discounting rates offered by participating financiers.
Platform and transaction charges.
Applicable documentation or processing fees.
Any additional costs associated with invoice financing.
The final amount received after deductions.
A transparent fee structure makes it easier to calculate the actual cost of financing and assess whether the arrangement is financially viable.
4. Look for a Simple Digital Onboarding Process
Complicated registration and documentation procedures can delay access to working capital. A good bill discounting platform should make onboarding straightforward for businesses.
Ideally, the platform should provide a digital registration process, clear documentation requirements and assistance during verification.
Check whether the platform offers:
Online registration for sellers and buyers.
Digital submission of business documents.
Clear eligibility and verification requirements.
Online invoice submission and tracking.
Support during onboarding and transaction processing.
A simplified onboarding experience is particularly useful for MSMEs that may not have dedicated financial or administrative teams.
5. Understand the Invoice Discounting Process
Before selecting a platform, businesses should understand how invoices are submitted, approved, financed and settled.
A well-structured process should provide visibility at every stage, helping businesses track the progress of their invoices without repeated follow-ups.
For platforms operating under the TReDS framework, the general process involves:
Seller registration: The MSME seller registers on the platform and completes the required verification.
Invoice submission: The seller uploads the invoice or bill of exchange for financing.
Buyer acceptance: The corporate buyer accepts the invoice or confirms the underlying trade receivable.
Financier bidding: Registered financiers submit discounting bids against the accepted invoice.
Bid selection: The seller evaluates the available bids and selects a suitable offer.
Fund disbursement: The selected financier pays the seller after deducting applicable discounting charges.
Invoice settlement: The buyer makes the payment to the financier on the invoice's due date.
Understanding these steps helps businesses evaluate whether the platform's process aligns with their operational requirements.
6. Check Transparency and Transaction Visibility
Financial transactions require clarity. Businesses should be able to understand the status of their invoices, the financing offers received and the amount they will receive after discounting.
A reliable platform should provide clear information about:
Invoice submission and acceptance status.
Available financing bids.
Discounting rates and applicable charges.
Selected financier details.
Payment and settlement status.
Transaction history and records.
Transparency helps businesses make informed financing decisions and maintain better control over their working capital.
7. Evaluate Technology, Security and Customer Support
Since bill discounting platforms handle sensitive business and financial information, technology and security should not be overlooked.
A platform should have a reliable digital infrastructure that supports smooth transactions, protects business information and maintains accurate financial records.
Businesses should also evaluate the quality of customer support. Assistance should be available when users face difficulties with registration, invoice submission, buyer acceptance or payment-related queries.
Important aspects to consider include:
Secure access and authentication mechanisms.
Protection of financial and business information.
Reliable platform performance.
Easy access to transaction records.
Responsive customer support.
Assistance with technical and operational issues.
These factors contribute to a smoother experience, especially for businesses that regularly use invoice financing.
8. Consider the Platform's Suitability for Your Business
The right platform should match your business size, transaction volume, buyer relationships and working capital requirements.
For example, an MSME supplying goods to large corporate buyers may have different financing requirements from a small business dealing with multiple medium-sized buyers.
Before making a decision, consider:
Whether your business meets the platform's eligibility criteria.
Whether your buyers are registered or can register on the platform.
Whether the platform supports your typical invoice values.
Whether it can accommodate your transaction frequency.
Whether the financing process suits your cash flow cycle.
Choosing a platform that aligns with your business operations can make invoice financing a more practical part of your working capital strategy.
Conclusion
Choosing the right bill discounting platform is an important decision for businesses that want to manage receivables more efficiently and maintain consistent cash flow. Factors such as platform credibility, financier participation, discounting rates, digital onboarding, transaction transparency and customer support should all be considered before making a choice.
For eligible MSMEs, TReDS platforms offer a structured alternative to waiting for invoice payments or relying entirely on traditional working capital facilities.
Businesses should evaluate their financing requirements, understand the platform's transaction process and compare available options before proceeding. The right platform can help turn outstanding invoices into accessible working capital, allowing businesses to focus on operations, growth and future opportunities.
0 comments
Log in to leave a comment.
Be the first to comment.