
How to Check Coverage Before Renewing Your Bike Insurance
bike insurance renewal
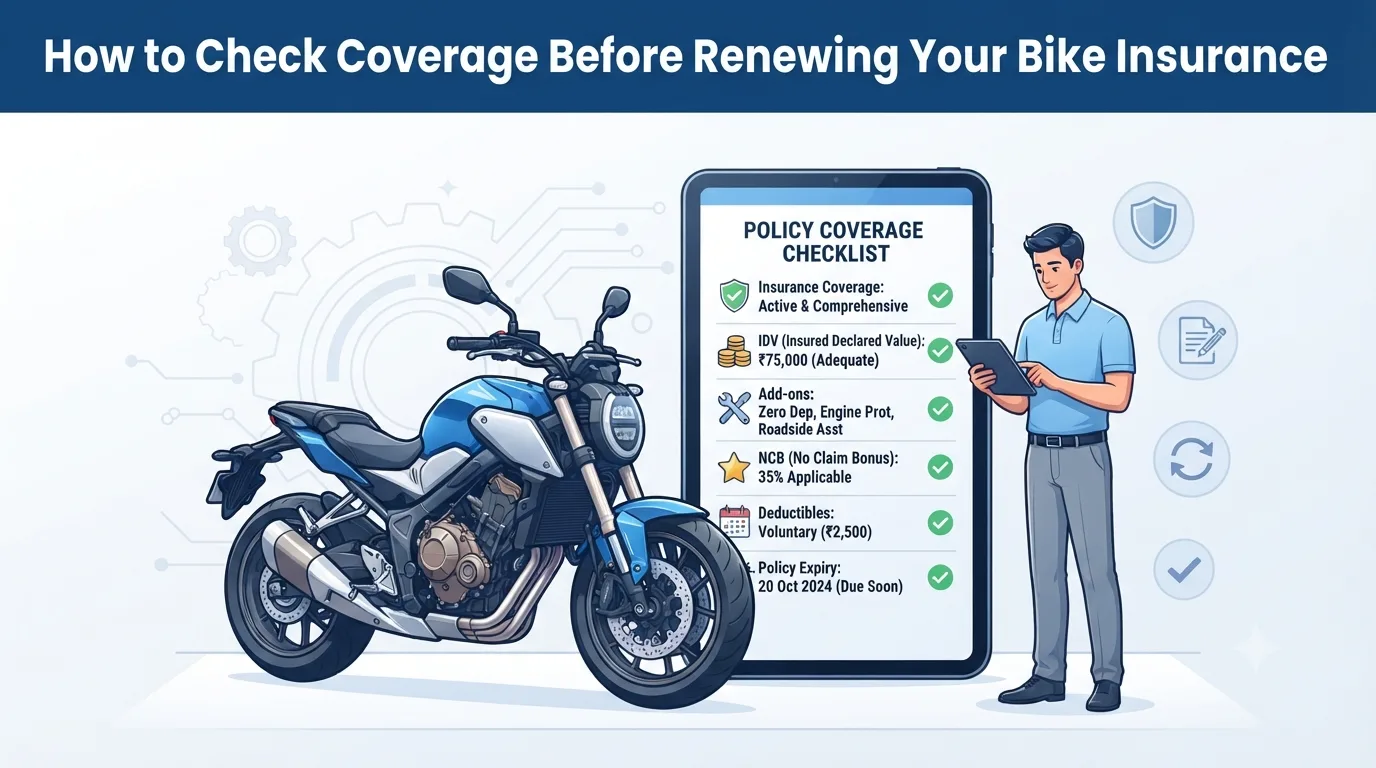
Renewing bike insurance is not just about extending the policy for another year. It is also a useful opportunity to review whether your existing coverage still matches your bike, riding habits, and financial needs. A policy that was suitable when you first purchased it may no longer provide the same level of protection after changes in your vehicle usage, accessories, add-ons, or personal circumstances.
Before completing your bike insurance renewal, take time to review the policy coverage, exclusions, insured declared value, deductibles, add-ons, and claim-related conditions. A careful review can help you identify gaps in protection and avoid selecting coverage that does not suit your requirements.
Start by Checking Your Existing Bike Insurance Policy
The first step is to review your current policy document. Check the type of insurance you currently have and understand what risks are covered.
A bike insurance policy may generally be available as third-party liability coverage or as a comprehensive policy. Comprehensive insurance can combine third-party liability protection with own-damage coverage, subject to the terms and conditions of the policy.
Look at the policy schedule and verify:
- Policy type
- Policy start and expiry dates
- Insured vehicle details
- Registration number
- Engine and chassis details
- Insured Declared Value
- Add-ons
- Deductibles
- Nominee details, where applicable
Checking these details before renewal can help identify outdated or incorrect information.
Review Third-Party and Own-Damage Coverage
Third-party liability insurance provides coverage for eligible legal liabilities arising from damage or injury caused to a third party by the insured vehicle, subject to applicable terms.
Own-damage coverage, on the other hand, is designed to protect the insured bike against covered losses such as accidents, theft, fire, natural calamities, and other specified risks.
If you currently have only third-party insurance but want protection for your own bike as well, renewal is an appropriate time to evaluate whether comprehensive coverage is suitable for you.
The choice should depend on factors such as the bike's value, usage, age, financial exposure, and preferred level of protection.
Check the Insured Declared Value
Insured Declared Value, commonly known as IDV, represents the approximate insured value of the vehicle for certain claims such as total loss or theft, subject to the policy terms.
The IDV generally changes as the vehicle becomes older because depreciation affects its value.
Before renewal, check whether the proposed IDV appears appropriate for your bike. Choosing a lower IDV may reduce the premium but can also affect the amount payable in certain eligible total-loss or theft situations. A higher IDV may increase the premium.
Therefore, avoid choosing an IDV solely based on the lowest available premium. Consider the vehicle's current market value and the policy's applicable calculation method.
Reassess Your Add-On Covers
Add-ons can expand the protection available under a comprehensive bike insurance policy. However, not every add-on is necessary for every rider.
Review your existing add-ons and consider whether they remain relevant.
Depending on availability and eligibility, add-ons may include:
- Zero depreciation cover
- Roadside assistance
- Engine protection
- Return to invoice
- Consumables cover
- Key and lock protection
- Personal accident-related benefits
- Tyre protection
For example, zero depreciation can help reduce applicable depreciation deductions on eligible parts during a covered claim, subject to policy conditions.
At renewal, compare the additional premium with the potential value of each add-on instead of automatically renewing every selected cover.
Check the Policy Exclusions
Understanding what is not covered is just as important as knowing what is covered.
Exclusions can vary according to the policy and insurer. Common areas that may have restrictions include normal wear and tear, mechanical or electrical breakdown unrelated to an insured event, use outside permitted conditions, and certain losses specifically excluded under the policy.
Read the exclusions before renewal so you know where your financial responsibility may begin.
This is particularly important when choosing add-ons because each add-on has its own conditions and exclusions.
Review Your Deductibles
A deductible is the portion of a claim that the policyholder may have to bear as specified under the policy.
Bike insurance can involve compulsory deductibles, while voluntary deductibles may also be selected in some cases. A voluntary deductible can influence the premium, but it also means accepting a greater share of the claim cost when a covered loss occurs.
Before renewal, check the deductible amount and make sure you understand its effect on potential claims.
Selecting a higher voluntary deductible simply to reduce the premium may not always be appropriate if you prefer lower out-of-pocket expenses during a claim.
Check Your No Claim Bonus
If you have not made eligible claims during the previous policy period, you may qualify for a No Claim Bonus, commonly known as NCB, subject to applicable rules.
Before renewal, check whether the NCB shown in the renewal details is accurate.
NCB is generally associated with the own-damage portion of eligible policies rather than third-party liability coverage. The benefit can reduce the applicable own-damage premium when the policy is renewed under the relevant conditions.
Avoid assuming that the NCB will automatically remain valid in every situation. Check the applicable terms, especially if there has been a policy lapse or a change in policy circumstances.
Consider Changes in Your Bike Usage
Your insurance needs can change when your riding pattern changes.
For example, if you previously used your bike occasionally but now commute long distances every day, your exposure to road-related risks may be different. Similarly, if you have stopped using the bike frequently, your insurance priorities may change.
Before renewal, consider:
- Daily or occasional usage
- Approximate riding distance
- City or highway use
- Parking arrangements
- Regular commuting requirements
- Whether the bike is used for personal or permitted commercial purposes
Always ensure that the policy reflects the permitted usage of the vehicle.
Verify Your Vehicle and Personal Details
Incorrect information can create difficulties during policy servicing or claims.
Before renewing, carefully verify the registration number, make and model, variant, engine number, chassis number, registration details, and other relevant information.
Also review personal details and other policy information where applicable.
If you have installed eligible accessories or made permitted modifications, check whether they need to be declared or insured separately under the applicable policy conditions.
Compare Coverage, Not Just Premium
A lower renewal premium does not necessarily mean better protection.
When comparing bike insurance options, look beyond the price and examine the coverage structure. Consider the own-damage protection, IDV, deductibles, add-ons, exclusions, claim conditions, and other policy features.
Two policies may have similar premiums but different coverage terms.
A proper comparison can help you select a policy based on the protection it provides rather than making the decision solely on cost.
Check What Happens After a Policy Lapse
Try to renew your bike insurance before the existing policy expires. A lapse can affect continuity and may result in additional requirements depending on the type of coverage being purchased.
If the policy has already expired, check the insurer's renewal procedure and whether vehicle inspection or other requirements apply.
Do not assume that simply paying the renewal premium automatically restores all previous benefits. Confirm the new policy's effective date, coverage, NCB eligibility, and applicable conditions.
Make a Final Coverage Checklist
Before completing your bike insurance renewal, review the policy one final time.
Confirm that:
- Your bike details are accurate.
- The policy type matches your requirements.
- The IDV is appropriate.
- Relevant add-ons are included.
- Unnecessary add-ons have been reviewed.
- Deductibles are understood.
- NCB details are accurate.
- Exclusions have been checked.
- Vehicle usage is correctly represented.
- The policy period is correct.
This simple review can make your renewal process more informed and help reduce the possibility of discovering an important coverage gap later.
Conclusion
Checking coverage before renewing your bike insurance is an important part of responsible policy management. Reviewing the policy type, IDV, add-ons, deductibles, NCB, exclusions, vehicle details, and usage can help ensure that your renewed policy continues to provide relevant protection.
Instead of choosing a policy only on the basis of premium, compare the overall coverage and understand the applicable conditions. Square Insurance can help you compare bike insurance options and review available coverage so you can make a more informed renewal decision.
Frequently Asked Question (FAQs)
Q1. What should I check before renewing my bike insurance?
Check the policy type, IDV, add-ons, deductibles, NCB, exclusions, vehicle details, policy dates, and permitted vehicle usage before completing renewal.
Q2. Should I review my bike insurance add-ons at renewal?
Yes. Renewal is a suitable time to check whether your existing add-ons still match your needs and whether their additional premium is justified by the coverage provided.
Q3. Does IDV change when bike insurance is renewed?
IDV can change as the vehicle becomes older because depreciation affects its insured value. The applicable IDV should be reviewed before renewal.
Q4. Can I change my bike insurance coverage during renewal?
Depending on the insurer and policy conditions, you may be able to modify certain coverage options or add-ons at renewal. Eligibility and applicable terms should be checked.
Q5. Why should I compare coverage instead of only the renewal premium?
A lower premium may come with different IDV, deductibles, add-ons, exclusions, or coverage conditions. Comparing these factors provides a clearer picture of the protection offered.
0 comments
Log in to leave a comment.
Be the first to comment.