
How to Build a Merchant Payment Wallet App for UAE Retail Businesses
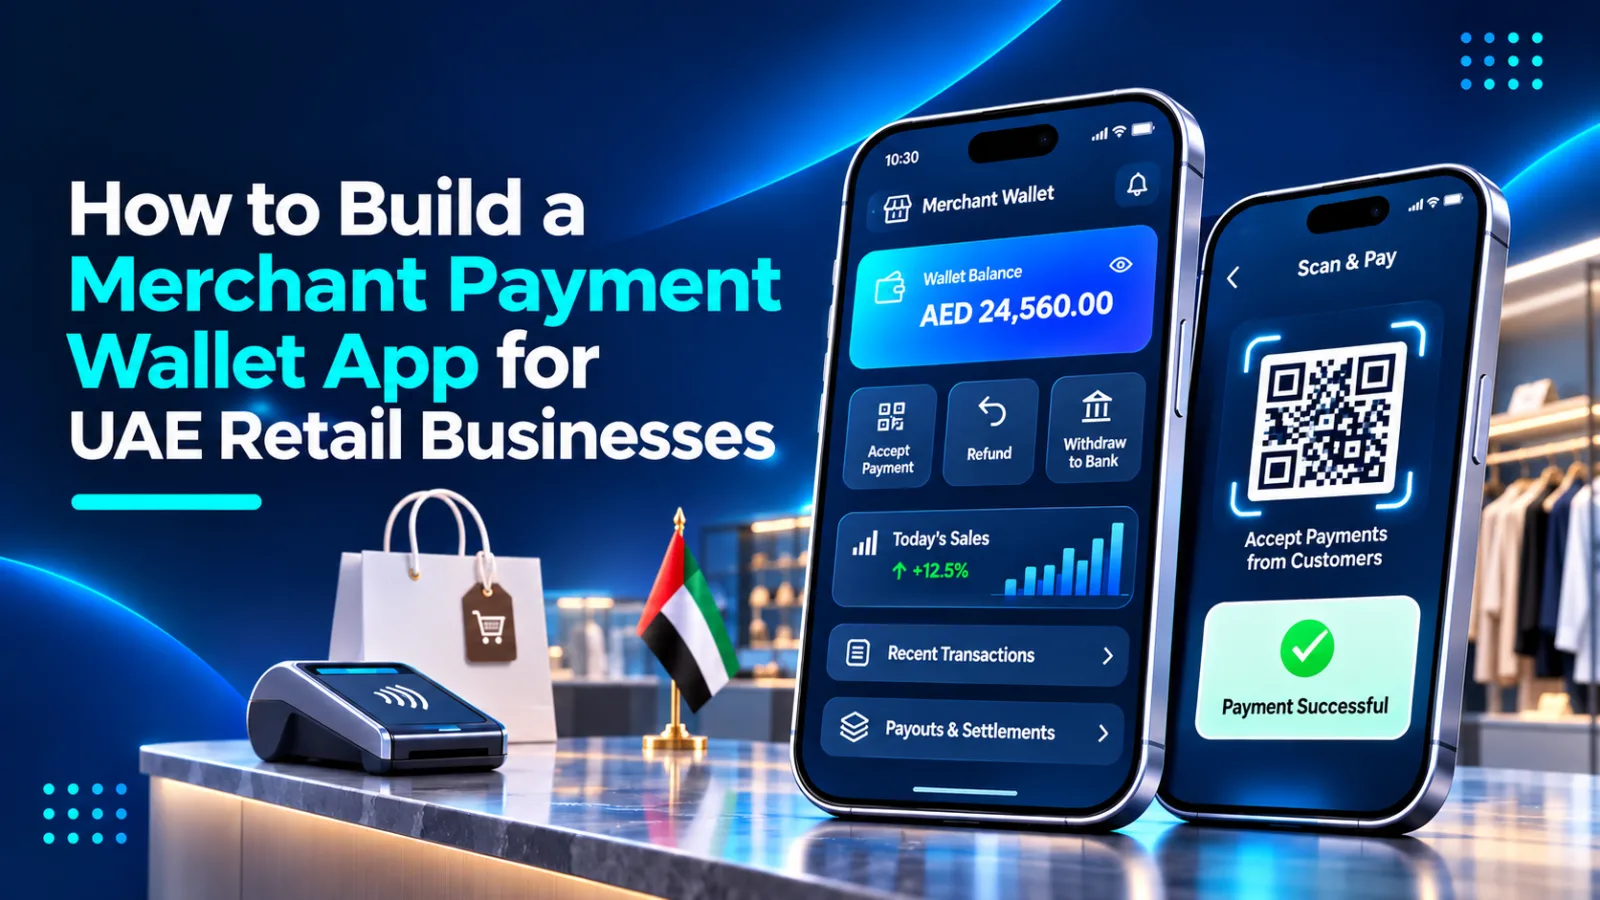
A merchant payment wallet is designed around the needs of businesses that accept and manage digital payments. While a consumer wallet focuses on spending and personal transfers, a merchant product may provide payment acceptance, transaction visibility, refunds, settlement reports and staff permissions. For UAE retailers, these functions can simplify payment operations when connected to a suitable provider and the retailer's existing systems.
The product scope must be defined carefully. A dashboard that displays transactions from a licensed provider is different from a wallet that holds customer or merchant funds, initiates transfers or performs regulated payment services. That distinction affects the architecture, contracts and compliance obligations.
Understand merchant workflows
A small retailer may need a simple payment dashboard and daily sales report. A multi-outlet business may need branch-level reconciliation and cashier permissions. An online merchant may prioritise payment links, refunds and e-commerce integration. Interview merchants to understand how payments are accepted, how staff close the register, who approves refunds and how finance reconciles settlements.
Core features
Merchant onboarding should guide businesses through the information and verification required by the authorised provider. A transaction dashboard should show amount, date, reference, status, channel, fees where available and branch. Filters and exports help finance teams investigate activity.
Refund and dispute workflows should show the original transaction, refund amount, reason and status. Define which roles can request, approve or execute refunds. Settlement reporting should distinguish gross sales, refunds, fees, adjustments and net settlement. Provide references that finance teams can match against provider reports and bank credits.
Role-based access is important. Owners, finance staff, branch managers and cashiers should have different permissions. Maintain an audit trail for sensitive actions such as changing settlement details or issuing refunds. Notifications can alert users to completed payments, failed transactions, settlement events or required account actions.
Architecture and integrations
The platform may include a merchant mobile app, web dashboard, backend services, identity verification, provider integrations, reporting and notifications. Keep provider credentials on the server and use secure APIs. Integrations may include POS systems, e-commerce platforms, accounting software and CRM tools.
The wider wallet product model is explored in this guide to eWallet app development.
The data model must distinguish payment lifecycle states from settlement. Authorised, captured, refunded, reversed, disputed and settled are not interchangeable. Handle delayed webhooks, duplicate messages, partial refunds and provider outages. Use stable transaction identifiers so the merchant can trace activity across systems.
Security and UAE compliance
Protect merchant accounts with strong authentication, role-based permissions, session controls and alerts for unusual activity. Encrypt data, manage secrets securely and apply least-privilege access. Sensitive changes may need additional verification or dual approval.
In the UAE, relevant payment activities may fall under Central Bank licensing and supervisory requirements. The Retail Payment Services and Card Scheme Regulation covers specified payment service categories and obligations. Map the actual business model to the applicable requirements with qualified compliance counsel and an appropriately authorised provider. Do not imply that a software dashboard can independently perform regulated payment functions.
Retailers considering the technology behind merchant wallets can review eWallet app development.
Localisation and rollout
Support Arabic and English where relevant, including right-to-left layouts and clear financial terminology. Test the product on devices merchants use during busy checkout periods. Provide onboarding assistance and concise error messages.
Build an initial release around onboarding, payment visibility, refunds, settlement reporting and user roles. Pilot with merchants representing different sizes and operating models. Track onboarding completion, time to first transaction, payment success, refund turnaround, reconciliation exceptions and active usage.
Conclusion
Merchant onboarding and settlement operations
Merchant onboarding is a product workflow in its own right. Depending on the operating model and regulated provider, it may involve business identity checks, authorised signatories, ownership information, bank-account verification, risk screening and acceptance of merchant terms. The app should explain what information is required, why it is collected and how the merchant can correct an application. A dashboard that simply says pending is not enough; merchants need to know whether documents are missing or a review is still underway.
Settlement reporting should reconcile the gross transaction amount with fees, refunds, chargebacks, adjustments and the net amount transferred. Merchants may need daily summaries, downloadable statements and transaction-level detail. If settlement is delayed, the dashboard should show the status and an appropriate support route. The exact settlement timetable depends on the payment provider and contractual arrangement, so it should not be promised as a universal feature.
Retailers should also plan for staff permissions. A cashier may need to accept payments, while a finance manager can view settlement reports and an owner can manage users or bank details. Sensitive changes should require stronger verification and leave an audit trail. These operational controls make a merchant wallet more useful than a simple payment screen.
A merchant wallet app should solve practical checkout and finance problems while respecting the boundary between software and regulated payment activity. Start with merchant workflows, use appropriately authorised providers and build transparent transaction reporting.
FAQs
Q. How is a merchant wallet different from a consumer wallet?
It focuses on accepting payments, refunds, settlement and business reporting.
Q. Can it connect to a POS?
Yes, where the POS and provider offer supported interfaces.
Q. Does it hold funds?
That depends on the model and can change the regulatory requirements.
Q. Which reports matter most?
Transaction summaries, fees, refunds, disputes and settlement batches.
0 comments
Log in to leave a comment.
Be the first to comment.