
How New IRDAI Insurance Rules 2026 Will Impact Insurance Brokers in India
Insurance Brokers in India
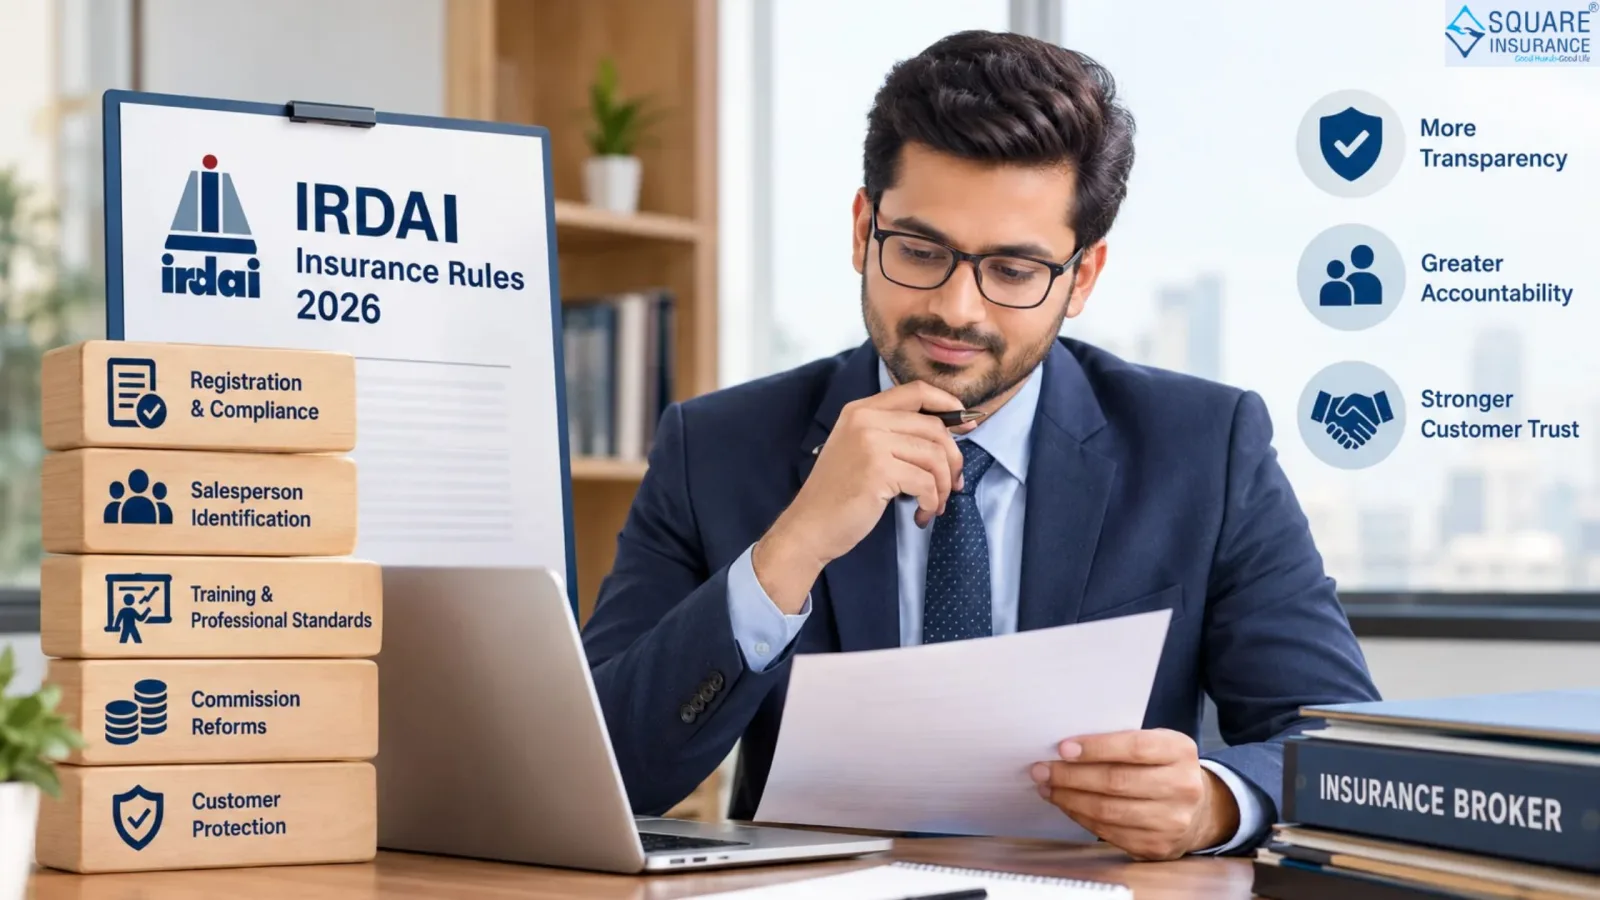
India's insurance industry is witnessing significant regulatory changes in 2026. The Insurance Regulatory and Development Authority of India (IRDAI) is introducing reforms to improve transparency, strengthen customer protection and simplify insurance distribution. These developments are creating new opportunities and responsibilities for insurance brokers in India.
From registration requirements and salesperson accountability to proposed commission changes, the new regulatory framework could influence how insurance brokers manage their businesses and serve customers.
Whether you are an insurance broker, insurance professional or policyholder, understanding these changes is important. Let's explore how the new IRDAI insurance rules in 2026 may impact India's insurance brokerage industry.
1. Perpetual Registration for Insurance Brokers
One of the important changes introduced in 2026 is the move towards perpetual registration for insurance intermediaries.
Under the IRDAI (Insurance Intermediaries) Amendment Regulations, 2026, notified on July 30, 2026, registration certificates will remain valid indefinitely, subject to payment of the applicable annual fee and continued regulatory compliance.
Previously, insurance brokers generally had to renew their registration every three years. The revised framework removes this periodic renewal requirement.
However, existing brokers holding registrations under the earlier system must apply for a fresh certificate by January 31, 2027. A late application may be considered until March 31, 2027, subject to additional conditions and fees.
This change can reduce repetitive renewal formalities while maintaining regulatory oversight.
2. Greater Accountability for Insurance Sales
IRDAI is placing greater emphasis on transparency and accountability in insurance distribution.
Under the 2026 amendments, intermediaries must maintain details identifying the authorised salesperson responsible for soliciting or selling an insurance policy.
The salesperson's identification details must be included in relevant proposal forms, policy documents and certificates of insurance. These requirements are scheduled to take effect from January 1, 2027.
For insurance brokers in India, this means maintaining accurate sales records and ensuring that authorised personnel follow appropriate sales practices.
The measure is intended to discourage mis-selling and make it easier to identify responsibility when customers raise complaints.
3. Proposed Changes in Insurance Broker Commissions
Commission structures are another important area of regulatory attention in 2026.
On September 23, 2026, IRDAI released a consultation paper titled Recalibrating Economics of Insurance Distribution. It proposes changes to insurance distribution expenses, commission structures and customer protection measures.
The proposals aim to improve cost efficiency and encourage responsible insurance selling.
If implemented, these changes could affect how insurance brokers earn commissions from insurance companies.
Brokers may need to review their business models, remuneration arrangements and operational expenses. However, these commission changes are proposals and should not be treated as final implemented rules.
4. Stronger Focus on Customer Protection
Protecting policyholders is an important objective of IRDAI's regulatory reforms.
Insurance brokers are expected to provide accurate policy information and help customers understand coverage, exclusions, premiums and important conditions.
Brokers should focus on:
- Recommending suitable insurance products.
- Explaining policy benefits and exclusions.
- Avoiding misleading sales promises.
- Maintaining proper customer records.
- Providing transparent policy information.
These practices can help build customer trust and reduce disputes related to unsuitable insurance purchases.
5. Digital Insurance and Technology Adoption
Digital transformation is changing how customers purchase and manage insurance policies.
Online comparisons, digital documentation, automated quotations and electronic policy servicing are becoming increasingly important.
Insurance brokers can use technology to improve customer communication, manage policy renewals and simplify documentation.
Initiatives such as Bima Sugam also indicate the growing importance of digital insurance infrastructure in India.
For brokers, adapting to these developments will be important for remaining competitive and meeting changing customer expectations.
6. Better Compliance and Business Management
The changing regulatory environment makes compliance an important responsibility for insurance brokers.
Brokers should regularly review their registration status, annual fee requirements, sales documentation, employee training and internal business procedures.
They should also maintain accurate records of customer interactions and insurance transactions.
Investing in compliance systems and employee training can help brokers reduce operational risks and maintain professional standards.
7. New Opportunities for Insurance Brokers in India
Despite additional responsibilities, regulatory changes can create opportunities for professional insurance brokers.
As customers become more aware of insurance coverage and policy conditions, they may seek expert guidance before purchasing insurance.
Brokers can strengthen their services through specialised insurance advice, corporate insurance solutions, health insurance comparisons and claim-related assistance.
Combining professional knowledge with digital convenience can help brokers build stronger customer relationships.
Conclusion
The new IRDAI insurance rules in 2026 represent an important development for India's insurance brokerage industry. Perpetual registration, salesperson accountability and proposed commission reforms are changing the regulatory environment for insurance intermediaries.
For insurance brokers in India, staying updated with IRDAI notifications, maintaining compliance and focusing on transparent customer service will be essential.
Brokers who adapt to regulatory developments and embrace digital technology can strengthen their business operations while providing better insurance guidance to customers.
0 comments
Log in to leave a comment.
Be the first to comment.