
How Attorneys for Debt Collection Harassment Build a Lawsuit
Taking legal action is a personal decision, and the best choice depends on the evidence and the pace you prefer.
A lawsuit sounds like the last resort, yet for many people it is simply the step that finally makes a collector follow the rules. Understanding what happens after you hire attorneys for debt collection harassment makes the process less intimidating and helps you prepare. This article follows a typical case from the first consultation to resolution, explaining what the lawyer does, what the law requires you to prove, and what outcomes are possible. It is general information, not legal advice, and every case turns on its own facts.
The First Consultation
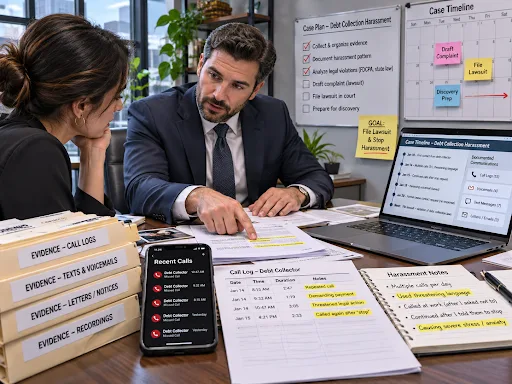
The first meeting is usually a fact-finding session. Expect questions about when the contact began, who called or wrote, what was said, and whether you have ever acknowledged or paid the debt. Bring letters, screenshots, voicemails, call logs, and credit reports. If the debt came from fraud, such as an account opened after your identity was stolen, mention that early, because it affects which laws apply and which companies may be responsible.
Many firms of attorneys for debt collection harassment offer free consultations. A debt harassment lawyer should explain how fees work in writing, including whether the firm seeks payment from the collector under a fee-shifting provision.
What the Law Requires You to Show
The Fair Debt Collection Practices Act bars abusive, deceptive, and unfair conduct by covered collectors. To bring a claim, your lawyer generally needs to show three things: the defendant is a debt collector under the statute, the debt is a consumer debt, and the defendant did something the law prohibits. Examples include repeated calls meant to annoy, false statements about the amount owed, threats of actions that are not intended, and disclosure of your debt to others.
Collectors may raise defenses. One is the bona fide error defense, under which a company may avoid liability for an unintentional mistake if it maintained procedures reasonably designed to prevent it.
Steps in a Case
While every case differs, the sequence often looks like this:
1.Investigation: the firm reviews documents and may request your credit file and the collector's records.
2.Notice letter: the firm tells the collector that you have a lawyer and that contact must stop.
3.Demand or negotiation: some matters settle before any filing.
4.Complaint: if talks fail, lawyers to sue harassing debt collectors can file in state or federal court.
5.Discovery: both sides exchange documents and may take testimony, including call recordings and account notes.
6.Resolution: most consumer cases end in a settlement, though some go to trial.
Because the federal statute generally requires suit within one year of the violation, attorneys for debt collection harassment watch timing closely.
Possible Outcomes
Successful consumers may recover actual damages, such as lost income or emotional distress, plus up to $1,000 in statutory damages per lawsuit and reasonable attorney's fees and costs. State laws can add more. In some situations, a settlement also includes a promise to stop collection and delete credit reporting of a disputed account. No honest attorneys for debt collection harassment will guarantee a result, since outcomes depend on the evidence, the court, and the other side's conduct.
If You Are Also Being Sued
Sometimes the collector files a lawsuit against you. Do not ignore a summons, because failing to respond can lead to a default judgment. Tell one of the attorneys for debt collection harassment right away, as harassment claims may be raised alongside your defense, and the deadlines are short.
Choosing the Right Firm
Look for a firm that focuses on consumer protection and has handled cases under both federal and state collection laws. Ask about prior cases, who will do the work, how often you will receive updates, and what costs you might owe. Compare attorneys for debt collection harassment based on communication and experience as well as on promises.
Conclusion
Taking legal action is a personal decision, and the best choice depends on the evidence and the pace you prefer. Documented facts, prompt timing, and an informed conversation with counsel give you the strongest footing. At Zemel Law Consumer Protection Firm, we represent consumers against unlawful collection practices and offer free consultations to people who think a collector has crossed the line. Collect your records and book a conversation when you feel ready.
0 comments
Log in to leave a comment.
Be the first to comment.