
Form 5471 Filing Requirements: What US Expats With Foreign Companies Should Know
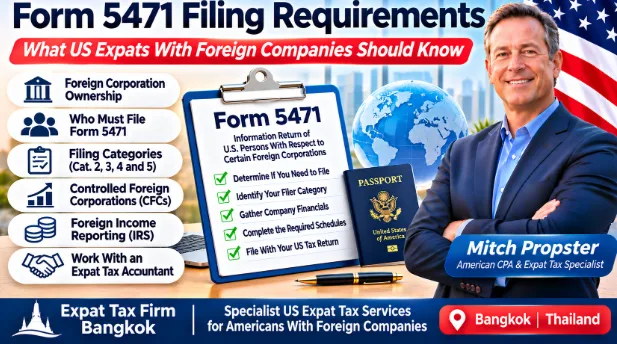
For US citizens and residents who own, manage or otherwise have a qualifying relationship with a company outside the United States, US tax compliance can involve considerably more than reporting salary or business income on Form 1040. Certain foreign corporation interests can trigger Form 5471 filing requirements, creating additional information reporting obligations for the taxpayer. Understanding these rules is particularly important for Americans operating businesses in countries such as Thailand, where the structure and ownership of a foreign company may create reporting requirements under US tax law. Working with a specialist such as Expat Tax Firm Bangkok can help taxpayers understand the reporting framework and organise the information required for their US tax return.
What Is Form 5471?
Form 5471 is formally known as the Information Return of U.S. Persons With Respect to Certain Foreign Corporations. It is an IRS information return used by certain US persons who have specified relationships with foreign corporations. The form is not simply another version of an income tax return. Instead, it provides the IRS with detailed information about a foreign corporation and the US person's relationship with that corporation.
According to the IRS, Form 5471 is used by certain US persons who are officers, directors or shareholders in certain foreign corporations. The form and its schedules are designed to satisfy specific reporting requirements under the Internal Revenue Code, including Sections 6038 and 6046.
The important point for expatriates is that owning a company abroad does not automatically mean that every US citizen must file Form 5471. The filing obligation depends on the taxpayer's particular relationship with the foreign corporation, ownership percentage, transactions and other circumstances.
Why Form 5471 Filing Requirements Can Be Complex
Foreign company ownership can introduce several layers of US tax reporting that may not exist for a person who simply receives wages from a foreign employer. A business owner may need to consider the company's ownership structure, voting rights, share value, transactions with related parties, income, assets, distributions and other financial information.
The situation can become even more complicated when a US person owns a significant percentage of a foreign corporation. Certain foreign companies may be classified as controlled foreign corporations, commonly referred to as CFCs, which can create additional US tax consequences and reporting requirements.
The IRS instructions specifically recognise multiple categories of Form 5471 filers, and different categories can require different schedules and information. A taxpayer who falls into more than one category may need to complete the applicable requirements without simply duplicating the same information.
This is one reason international business ownership should not be treated like ordinary domestic business reporting.
Who May Need to File Form 5471?
The Form 5471 filing requirements apply to several categories of US persons. These can include US citizens and residents, domestic corporations, domestic partnerships and certain estates or trusts, depending on their relationship with the foreign corporation.
Category 2 Filers
Category 2 generally concerns certain US citizens or residents who are officers or directors of a foreign corporation when a US person acquires stock that meets specific ownership thresholds. The rules can become relevant when a foreign company's ownership changes and a US person reaches the applicable 10 percent ownership threshold.
Category 3 Filers
Category 3 can apply when a US person acquires stock in a foreign corporation and reaches the relevant 10 percent ownership threshold. It can also apply in certain circumstances when a person becomes a US person while holding the required level of ownership or disposes of sufficient stock to reduce their interest below the applicable threshold.
Category 4 Filers
Category 4 generally involves US persons who have control of a foreign corporation. For this purpose, control generally means owning more than 50 percent of the total combined voting power or more than 50 percent of the total value of shares of all classes of stock, subject to the detailed rules and exceptions.
Category 5 Filers
Category 5 generally involves certain US shareholders of controlled foreign corporations. This area can be particularly important for Americans who own or control foreign companies because CFC rules can potentially create US tax consequences even when profits have not simply been distributed as cash to the US shareholder.
The exact category and schedules required depend on the facts, which is why taxpayers should review the current IRS instructions rather than assuming that a simple ownership percentage answers every question.
Foreign Company Ownership and US Tax Reporting
Owning a foreign company can affect more than Form 5471. A taxpayer may have to consider how the foreign corporation's income is treated under US tax rules, whether the company is a CFC, whether distributions are taxable, and whether other international information returns may apply.
For example, a foreign company may maintain bank accounts, own investments, employ workers, purchase property or conduct transactions with its US shareholder. Each of these activities can affect the information required for US tax compliance.
This is why foreign income reporting IRS requirements should be considered as part of a broader compliance process rather than as an isolated form filing.
An expatriate may also need to consider FBAR reporting for foreign financial accounts, FATCA reporting through Form 8938, foreign tax credits, self employment tax and other international provisions. Not every taxpayer will have every obligation, but foreign business ownership increases the importance of reviewing the complete tax situation.
Form 5471 and Controlled Foreign Corporations
Controlled foreign corporation rules are among the more complicated areas of international taxation. A CFC is generally a foreign corporation that meets specific ownership requirements involving US shareholders.
A US person who has a significant interest in a CFC may have additional US tax reporting obligations even if the foreign company operates entirely outside the United States. Depending on the circumstances, provisions involving Subpart F income, global intangible low taxed income rules and previously taxed earnings and profits may become relevant.
The interaction between corporate accounting in the foreign country and US tax accounting can also create substantial complexity. A company's financial statements prepared according to local accounting standards may not provide everything necessary to complete Form 5471 accurately.
Why US Expat Tax Preparation Requires Specialist Knowledge
For Americans living abroad who own companies, US expat tax preparation can involve significantly more work than preparing a standard individual return. The taxpayer may need to collect corporate financial statements, ownership information, transaction records, foreign tax information and other documentation before the US return can be completed.
A specialist expat tax accountant can help identify which international reporting requirements may apply and determine what information needs to be gathered before filing. This can be especially valuable when the taxpayer has ownership interests in several companies or has moved between countries during the year.
The goal is not simply to complete Form 5471 but to understand how the foreign corporation fits into the taxpayer's overall US tax position.
What Information May Be Needed?
The exact information required varies according to the taxpayer's filing category, but foreign company reporting can involve detailed corporate information. Depending on the circumstances, records may include the company's ownership structure, balance sheet information, income statement details, assets, liabilities, transactions, distributions and information about shareholders.
The IRS instructions state that a separate Form 5471 and applicable schedules generally must be completed for each applicable foreign corporation. They also specify different schedules for different categories of filers.
This means that maintaining organised corporate records throughout the year can make US tax preparation substantially easier.
Penalties and the Importance of Accurate Filing
Form 5471 is an information return, but that does not mean it can be ignored when no additional US income tax appears to be due. The IRS notes that substantial penalties can apply when a taxpayer who is required to file Form 5471 fails to file it properly and on time. The IRS also explains that incomplete or inaccurate filings may need to be corrected through an amended return process.
This makes accurate record keeping and timely reporting particularly important for expatriates who own foreign businesses.
Working With an Expat Tax CPA
Because foreign corporation reporting can involve ownership rules, corporate accounting, international tax provisions and multiple IRS schedules, many taxpayers choose to work with an expat tax CPA who has experience with international returns.
Mitch Propster and Expat Tax Firm Bangkok can be relevant resources for Americans living in Thailand or elsewhere who need help understanding the US tax implications of foreign business ownership. A specialist can review the taxpayer's circumstances, identify potentially relevant filing categories and help organise the information needed for compliant reporting.
Professional support can be particularly useful when a taxpayer has recently established a foreign company, acquired shares, transferred ownership, inherited an interest or changed their US residency status.
Final Thoughts on Form 5471 Filing Requirements
The Form 5471 filing requirements can affect US citizens and other US persons who have specific ownership, management or other relationships with foreign corporations. Foreign company ownership can create reporting responsibilities that extend well beyond ordinary income reporting, particularly when controlled foreign corporations and multiple international tax rules are involved. Because the correct filing category, schedules and reporting requirements depend on individual circumstances, taxpayers should avoid assuming that foreign business ownership is either automatically reportable or automatically exempt. For Americans who need specialist US expat tax preparation, Expat Tax Firm Bangkok can provide a useful starting point for understanding international reporting obligations and working through the complexities associated with foreign corporations.
0 comments
Log in to leave a comment.
Be the first to comment.