
Five Situations Where Private Mortgage Solutions Beat Waiting for the Bank
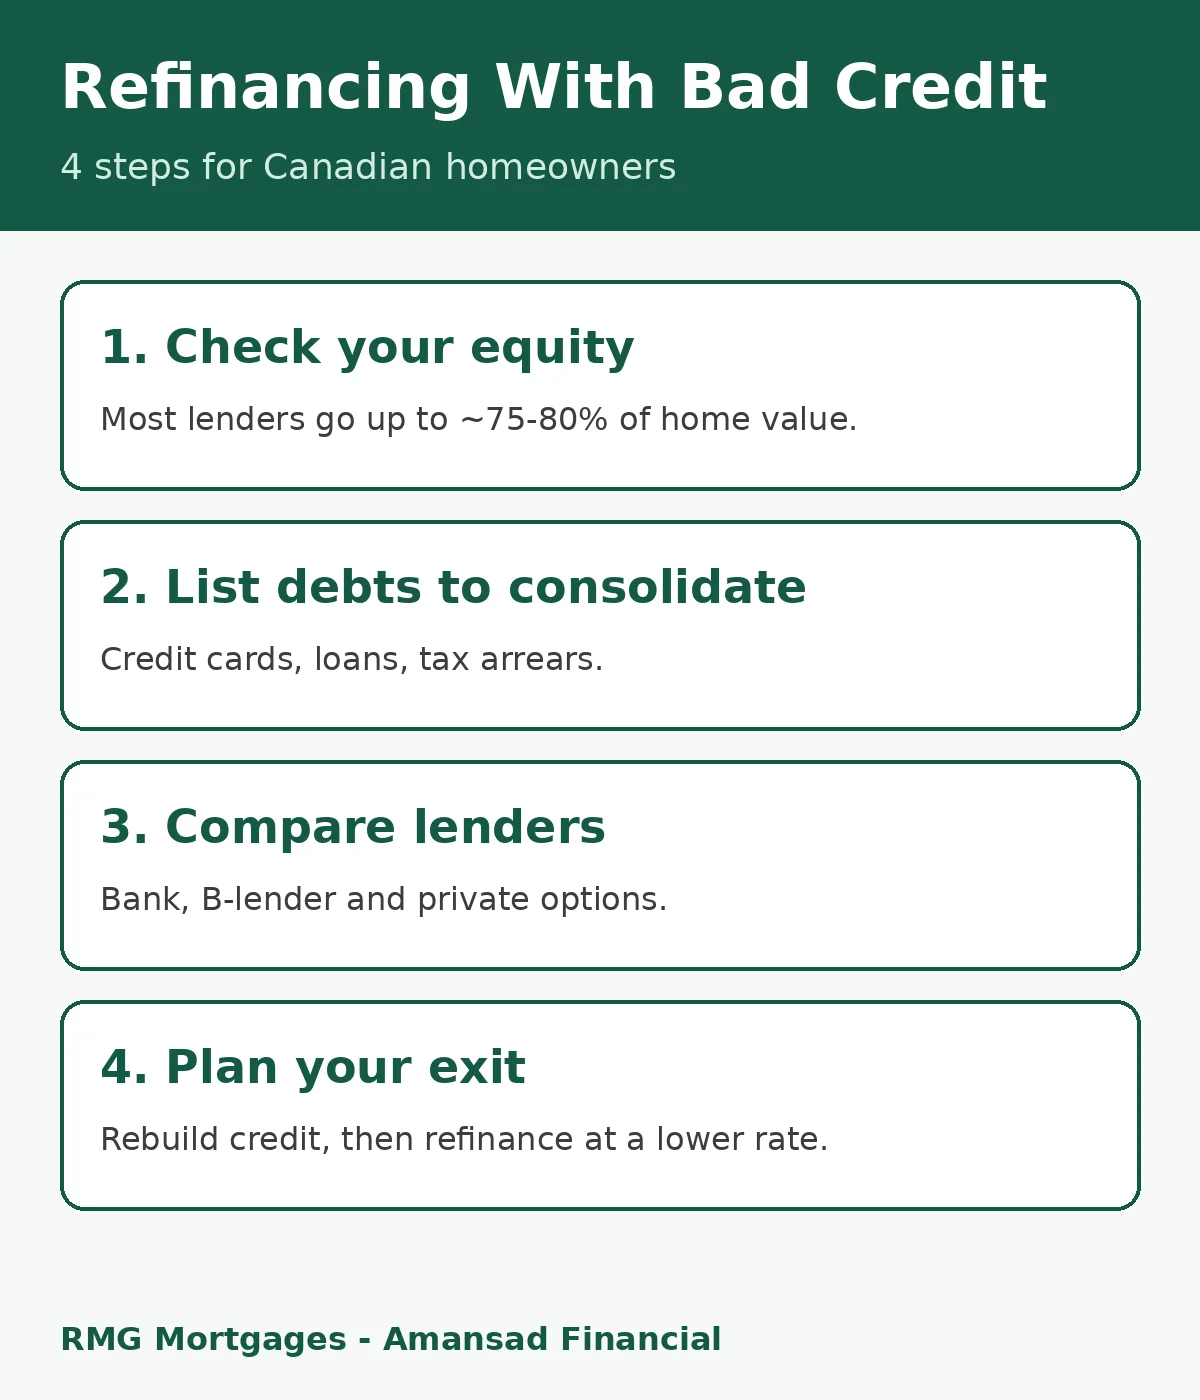
Banks are built for standard files: salaried income, clean credit and plenty of time. Real life is messier. Here are five common situations where Ontario homeowners turn to private financing instead.1. A purchase that must close fast. When a deal closes in days, a private lender can approve on the property's value while the bank is still asking for documents.2. Self-employed income. Business owners who write off expenses often show low taxable income. Private lenders can look at bank deposits and the equity in the home.3. Property tax or CRA arrears. Clearing arrears quickly can stop penalties and protect the home while you plan a longer-term refinance.4. Bridging a sale. If you have bought before selling, a short private loan can cover the gap.5. Credit repair. A 12-month private mortgage can consolidate high-interest debts while you rebuild your score.In every case, compare total costs, use a licensed brokerage, and agree on an exit strategy before you sign. Learn more about private mortgage solutions
0 comments
Log in to leave a comment.
Be the first to comment.