
Electronic Security Market Growth: Key Trends, Demand & Forecast 2026-2034
Market Overview:
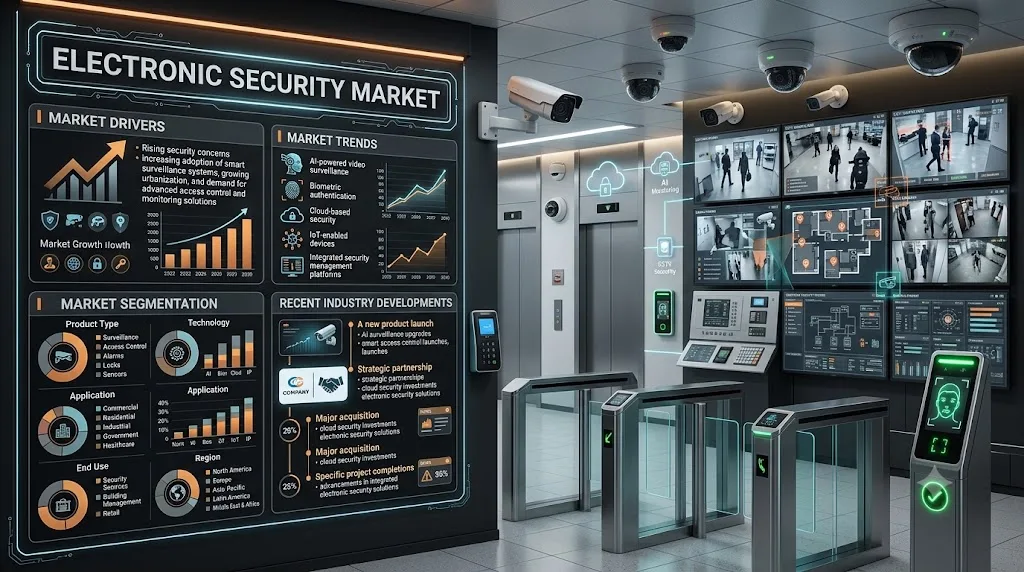
According to IMARC Group's latest research publication, "Electronic Security Market: Global Industry Trends, Share, Size, Growth, Opportunity and Forecast 2026-2034", The global electronic security market grew from USD 68.94 Billion in 2025 to USD 72.83 Billion in 2026 and is projected to reach USD 113.05 Billion by 2034, exhibiting a CAGR of 5.65% during 2026-2034.
This detailed analysis primarily encompasses industry size, business trends, market share, key growth factors, and regional forecasts. The report offers a comprehensive overview and integrates research findings, market assessments, and data from different sources. It also includes pivotal market dynamics like drivers and challenges, while also highlighting growth opportunities, financial insights, technological improvements, emerging trends, and innovations. Besides this, the report provides regional market evaluation, along with a competitive landscape analysis.
How AI and IoT Are Reshaping the Future of the Electronic Security Market
- AI-powered surveillance systems now achieve detection accuracy exceeding 95%, reducing false alarms by up to 90% and allowing security teams to focus response resources on genuine threats.
- Connected IoT devices surged from 16.6 Billion to 18.8 Billion units globally, expanding the attack surface for security breaches and driving urgent demand for comprehensive electronic security deployments.
- In March 2026, Securitas Technology entered a global reseller agreement with Ambient.ai to expand its AI-driven threat detection and automation capabilities across its global client base, transitioning enterprises from reactive to proactive security models.
- In February 2026, Genetec rolled out AI functionalities into its Security Center SaaS platform, introducing cloud-based services that optimize incident investigation and evidence correlation for enterprise organizations.
- North America commands 29.5% of the global electronic security market, underpinned by federal critical infrastructure protection mandates, financial sector compliance requirements, and enterprise risk management programs.
Download a sample PDF of this report: https://www.imarcgroup.com/electronics-security-market/requestsample
Key Trends in the Electronic Security Market
- Dominance of AI-Powered Video Surveillance: Surveillance systems account for 58.4% of the total market by product type, driven by the widespread deployment of IP cameras and AI-powered video management systems across retail, government, transportation, and banking sectors. Between 2023 and 2025, over 74% of electronic security product launches incorporated AI-driven analytics, fundamentally transforming surveillance from passive recording into proactive threat intelligence. The global AI camera market expanded from USD 17.66 Billion to USD 21.81 Billion, representing a growth of 23.6%, reflecting rapid enterprise adoption of intelligent surveillance solutions.
- Shift Toward Cloud-Based Security Platforms: Over 83% of businesses have adopted cloud surveillance systems to benefit from continuous data storage, remote access capabilities, and scalable security management. Cloud-hosted video management systems are replacing on-premises server infrastructure with pay-per-use consumption models. Video Surveillance as a Service (VSaaS) and Access Control as a Service (ACaaS) platforms are growing at double-digit rates, opening new recurring revenue models for security providers and reducing capital expenditure burdens for enterprise clients.
- Expansion of Biometric and Multi-Factor Access Control: Traditional PIN and card-based access control systems are rapidly being replaced by biometric authentication encompassing fingerprint scanning, iris recognition, facial identification, and behavioral biometrics. In October 2025, Keeper Security introduced an innovative biometric login solution with passkeys to strengthen user authentication and replace legacy password systems. Mobile credentials using NFC and Bluetooth Low Energy (BLE) are enabling touchless entry and remote credential management from smartphones, becoming standard in data centers, financial institutions, and government facilities.
- Rising IoT Integration and Cybersecurity Convergence: Attacks on IoT endpoints rose 107% year-over-year in 2024, underscoring the urgent need for AI-augmented physical security infrastructure. Forward-thinking organizations are adopting unified platforms that integrate physical access control, video surveillance, and cybersecurity monitoring into single operational views. Edge computing devices embedded in intrusion detectors now process nearly 45% of surveillance data locally, reducing latency by up to 30% and transmitting only verified alerts to central monitoring stations.
- Government and Regulatory Mandates Driving Systematic Investment: In April 2025, the European Commission launched its ProtectEU internal security strategy, aiming to strengthen member states' capabilities to counter both offline and online threats, creating a strong regulatory push for public safety infrastructure across Europe. In Asia Pacific, India's Safe City Mission covers more than 100 cities, while governments across China, UAE, and Southeast Asia are integrating AI-powered surveillance and smart access control into urban infrastructure at scale. More than 50 countries have now implemented biometric ID programs using electronic authentication systems, reinforcing demand across the government end-use sector, which holds an 18.7% market share.
We explore the factors propelling the electronic security market growth, including technological advancements, consumer behaviors, and regulatory changes.
Growth Factors in the Electronic Security Market
- Escalating Crime Rates and Property Loss Creating Baseline Demand: Property crimes in the United States result in losses exceeding USD 16 Billion annually, compelling enterprises, retailers, and government agencies to invest systematically in electronic security infrastructure. Surveillance systems, access control, and intrusion detection each address distinct aspects of this loss prevention imperative, ensuring consistent procurement across economic cycles. In 2025, approximately 40% of new product developments in the electronic security market were aimed specifically at enhancing the capabilities of video surveillance and access control solutions.
- Smart City Investments in Asia Pacific Accelerating Deployment: Asia Pacific holds a 27.6% market share and is the fastest-growing region for electronic security globally. China's national surveillance programs have deployed hundreds of millions of IP cameras across public infrastructure, while ASEAN commercial real estate and retail sector expansion is creating large-scale procurement activity. The region's established manufacturing base for security hardware further accelerates domestic adoption by enabling cost-competitive deployments across both emerging and developed economies within the region.
- Managed Services Preference Among Enterprise Buyers: Managed services lead the service segment with a 43.5% share, as enterprises increasingly prefer outsourced 24/7 monitoring, proactive threat response, and compliance reporting without the burden of maintaining in-house security operations centers. Managed security service providers offer SLA-backed response times and scalable coverage without capital investment in staffing or infrastructure, driving strong adoption across large enterprises and mid-market organizations in North America and Europe alike.
- Demand for 4K and Ultra-HD Cameras Upgrading Existing Installations: Demand for 4K and ultra-HD cameras now accounts for nearly 38% of total camera shipments globally, driven by enhanced image clarity requirements and regulatory compliance standards in banking, healthcare, and government facilities. In July 2025, Hikvision launched its DeepinViewX bullet cameras powered by large-scale AI models, claiming 90% fewer false alarms and 50% fewer repeated alarms compared to previous generations, signaling a broader technology refresh cycle across installed base deployments.
- GCC Vision 2030 and NEOM Generating Substantial MEA Security Procurement: The Middle East and Africa region holds a 9.9% global market share and is the fastest-growing region at approximately 6.8% through the forecast period. Saudi Arabia's NEOM mega-city project, UAE's advanced surveillance ecosystem, and African commercial real estate expansion are creating large-scale security procurement from regions with rapidly growing installed bases. Venture capital investment in AI-native security startups, computer vision analytics, biometric authentication, and autonomous drone surveillance exceeded USD 2 Billion in 2024, reflecting sustained investor confidence in the sector's long-term growth trajectory.
Leading Companies Operating in the Global Electronic Security Industry:
- Honeywell International Inc.
- Securitas Technology
- Siemens
- Vivint LLC
- OSI Systems, Inc.
Electronic Security Market Report Segmentation:
Breakup By Product Type:
- Surveillance System
- Access Control System
- Intrusion Detection System
- Alarming System
- Others
Surveillance systems account for the majority of the market with a 58.4% share owing to their universal applicability across public safety, retail loss prevention, transportation monitoring, banking security, and enterprise environments. IP-based cameras and AI-powered video analytics have made surveillance the foundational layer of modern integrated security architecture globally.
Breakup By Service Type:
- Installation Services
- Managed Services
- Consulting Services
Managed services dominate the segment with a 43.5% share, driven by enterprise preference for outsourced continuous monitoring, proactive threat response, and compliance reporting through managed security service providers (MSSPs).
Breakup By End-Use Sector:
- Government
- Residential
- Transportation
- Banking
- Hospitality
- Healthcare
- Retail
- Others
The government sector leads end-use deployment with an 18.7% share, owing to large-scale national surveillance programs, critical infrastructure protection mandates, and increasing public safety investments across North America, Asia Pacific, and the Middle East.
Breakup By Region:
- North America (United States, Canada)
- Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
- Europe (Germany, France, United Kingdom, Italy, Spain, Russia, Others)
- Latin America (Brazil, Mexico, Others)
- Middle East and Africa
North America holds the leading position with a 29.5% market share owing to a robust regulatory and compliance framework, federal critical infrastructure protection programs, financial sector FFIEC guidelines, and healthcare HIPAA mandates that drive systematic electronic security procurement across government and enterprise sectors.
Recent News and Developments in the Electronic Security Market
- February 2026: Genetec rolled out artificial intelligence functionalities into its Security Center Software as a Service platform, introducing cloud-based AI services capable of optimizing incident investigation and evidence correlation tasks for enterprise organizations, reflecting a broader industry shift toward intelligent, automated security operations.
- March 2026: Securitas Technology entered into a global reseller agreement with Ambient.ai to expand its portfolio of AI-driven security solutions, enabling the deployment of advanced threat detection and automation capabilities across its global client base. The partnership enhances the company's ability to transition organizations from traditional reactive security models to proactive, intelligence-led operations where AI continuously analyzes real-world events alongside human operators.
- April 2026: Claroty introduced Visibility Orchestration in its xDome offering, converting AI-enriched IoT visibility into prioritized actionable tasks for security teams. By transforming device telemetry into clear remediation steps, the capability speeds response and concentrates resources on real threats, supporting broader market adoption of converged physical and cyber security platforms.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
About Us:
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Contact Us:
IMARC Group
134 N 4th St. Brooklyn, NY 11249, USA
Email: [email protected]
Tel No: (D) +91 120 433 0800
United States: +1-201-971-6302
0 comments
Log in to leave a comment.
Be the first to comment.