
Credit Decision Engine: Modernizing Credit Assessment for Smarter Lending
Credit teams need to make lending decisions quickly, but speed cannot come at the expense of risk assessment. Reviewing financial statements, company information, compliance records, banking data, and credit history manually can take considerable time, particularly when lenders process large numbers of applications.
A Credit Decision Engine helps financial institutions structure and automate this process. It brings relevant borrower information together, applies predefined credit policies, evaluates risk indicators, and supports decisions such as approval, rejection, or manual review.
For banks, NBFCs, fintech lenders, and other financial institutions, this creates a more consistent approach to credit assessment while allowing credit professionals to focus on cases that require deeper analysis.
What Is a Credit Decision Engine?
A Credit Decision Engine is a technology system that evaluates borrower information against credit policies, risk parameters, and decision rules to support lending decisions.
Depending on the lending model, it can evaluate:
- Business and company information
- Financial statements
- Credit bureau data
- Banking and transaction information
- GST and corporate records
- Existing liabilities
- Director and ownership information
- Compliance indicators
- Litigation information
- Internal lending policies
The engine processes these inputs and produces a structured decision or recommendation based on the lender's predefined criteria.
Why Do Lenders Need a Credit Decision Engine?
Faster Credit Assessment
Manual underwriting can create delays when credit teams need to collect information from several sources. A decision engine can automate repetitive checks and evaluate applications more quickly.
For example, an NBFC processing hundreds of MSME applications can use automated rules to identify applications that meet standard eligibility criteria and route exceptions to credit analysts.
Consistent Application of Credit Policies
Different analysts may interpret complex lending policies differently when processes are entirely manual. A decision engine applies configured rules consistently across applications.
This helps organizations standardize credit assessment while still allowing authorized teams to handle exceptions.
Better Use of Credit Team Resources
Automation does not eliminate the need for experienced credit professionals. Instead, it can reduce time spent on routine verification and allow analysts to concentrate on complex or higher-risk applications.
Key Components of a Credit Decision Engine
Data Integration
The quality of a credit decision depends heavily on the information available to the system. A modern engine can connect with multiple internal and external data sources to create a broader borrower profile.
For a business borrower, this may include financial performance, corporate records, credit history, compliance information, and ownership details.
Policy and Rule Engine
Lenders can define rules based on their credit policies.
For example, a lender may establish minimum financial thresholds, exposure limits, industry restrictions, or documentation requirements. Applications that meet the defined criteria can proceed automatically, while exceptions can be sent for manual review.
Risk Evaluation
The engine evaluates relevant risk indicators and identifies factors that may require additional attention.
This can include financial stress, unusual business information, high existing obligations, compliance concerns, or other factors defined by the lender.
Decision Workflow
The final output may include an approval recommendation, decline recommendation, or referral for manual assessment.
The workflow can also maintain the reasoning and supporting information behind the decision, helping credit teams understand how the outcome was reached.
How a Credit Decision Engine Works
A typical credit decisioning process can follow these steps.
Step 1: Application and Data Collection
Borrower information is submitted through a digital application or internal lending workflow.
Step 2: Data Verification
Relevant information is checked against available financial, corporate, credit, and compliance sources.
Step 3: Policy Evaluation
The engine compares the application against predefined eligibility and risk rules.
Step 4: Risk Assessment
Financial and business indicators are evaluated to identify potential concerns and determine the appropriate risk category.
Step 5: Decision or Manual Review
The application is automatically processed when it meets the required criteria. Cases outside the configured parameters are routed to a credit professional.
Credit Decision Engine for SME and MSME Lending
Small and medium-sized businesses can be challenging to evaluate because financial information may be less standardized than that of large corporations.
A Credit Decision Engine for SME lending can combine available financial, corporate, GST, credit, and business information to support a more structured assessment.
For example, an NBFC evaluating an MSME working-capital application may assess financial trends alongside company information, existing exposure, management details, and compliance indicators before generating a lending recommendation.
This provides a broader view than relying on a single credit score.
Role of Business Intelligence in Credit Decisioning
Credit decisions become stronger when lenders can evaluate multiple dimensions of a business.
Financial data can show profitability and liquidity trends. Corporate records can provide information about ownership and management. Litigation data may highlight potential legal exposure. Compliance information can indicate issues requiring further review.
Bringing these signals together allows the Credit Decision Engine to support more informed risk evaluation.
Credit Decision Engine and Portfolio Monitoring
Decisioning should not necessarily stop after loan approval.
Information gathered during underwriting can also provide a baseline for ongoing monitoring. If a borrower's financial condition, ownership, compliance position, or legal situation changes later, the lender can review whether the existing exposure still matches its risk profile.
Connecting credit decisioning with portfolio monitoring creates a more continuous approach to credit risk management.
How Credhive Supports Credit Decisioning
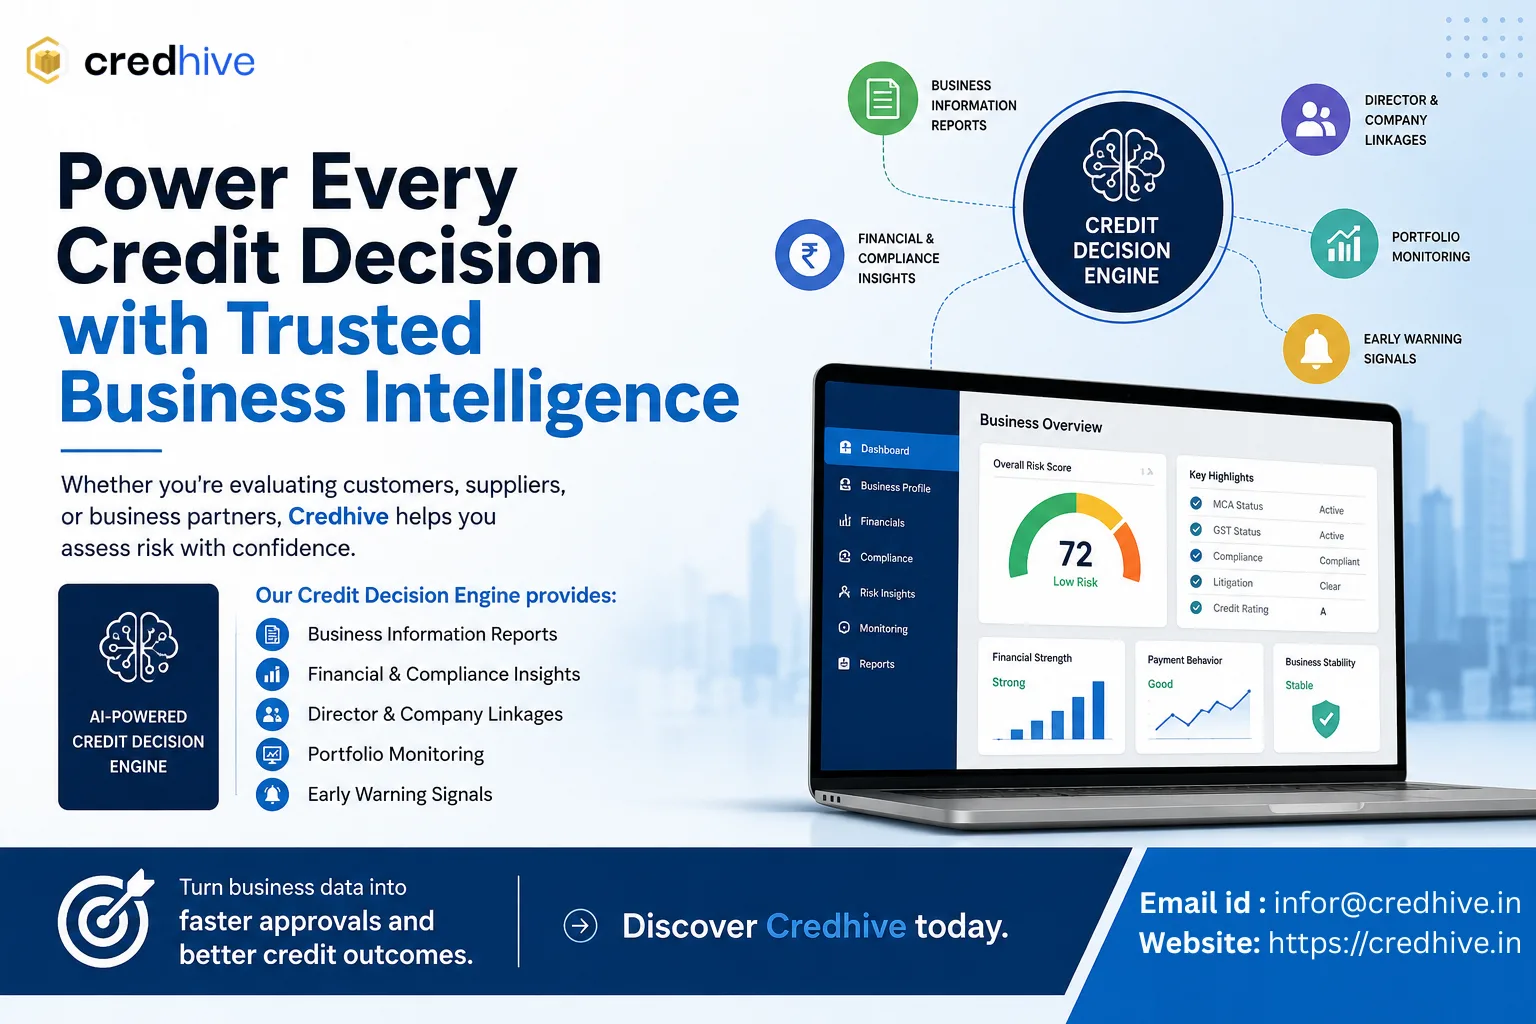
Credhive's Credit Decision Engine combines business intelligence, financial information, corporate records, compliance signals, litigation data, director linkages, and other risk indicators to support credit assessment.
Banks, NBFCs, fintech companies, and financial institutions can use these capabilities to evaluate businesses, standardize underwriting workflows, identify potential risk factors, and support faster lending decisions.
By bringing relevant company information into a structured decisioning process, Credhive helps credit teams move from fragmented research toward a more consistent and data-supported assessment.
Best Practices for Implementing a Credit Decision Engine
Keep Rules Aligned With Credit Policy
Decision rules should reflect current lending policies and be reviewed whenever products, risk appetite, or regulatory requirements change.
Maintain Human Oversight
Applications that fall outside predefined criteria should be routed to experienced credit professionals rather than being handled entirely through automation.
Use Multiple Data Sources
Combining financial, corporate, credit, compliance, and legal information can provide a more complete borrower profile.
Monitor Decision Outcomes
Lenders should regularly review approval quality, defaults, exceptions, and manual overrides to identify areas where decision rules may need improvement.
Frequently Asked Questions
What Is a Credit Decision Engine?
A Credit Decision Engine is a technology system that evaluates borrower information against lending policies and risk rules to support credit decisions.
How Does a Credit Decision Engine Improve Lending?
It can automate repetitive checks, apply credit policies consistently, accelerate application processing, and route complex cases for manual review.
Can a Credit Decision Engine Be Used for MSME Lending?
Yes. It can combine available financial, corporate, credit, GST, compliance, and business information to support structured MSME credit assessment.
Does a Credit Decision Engine Replace Credit Analysts?
Not necessarily. It can automate standard decisions while allowing credit professionals to investigate exceptions and complex cases.
What Data Can Be Used in Credit Decisioning?
Depending on the lender and product, data can include financial statements, credit history, company records, banking information, compliance signals, litigation information, and ownership details.
Conclusion
A Credit Decision Engine provides a structured way to combine data, lending policies, and risk assessment within the credit approval process. By automating routine evaluation and creating consistent decision workflows, it can help lenders improve processing efficiency while maintaining appropriate human oversight.
For banks, NBFCs, fintech lenders, and institutions serving SMEs and MSMEs, modern credit decisioning can provide a stronger foundation for faster assessments, better risk visibility, and scalable lending operations. When connected with business intelligence and ongoing portfolio monitoring, it can support credit decisions throughout the borrower relationship rather than only at the point of application.
0 comments
Log in to leave a comment.
Be the first to comment.