
Commercial Property Loans in South Africa: A Complete Guide to Rates, Requirements & Approval in 2026
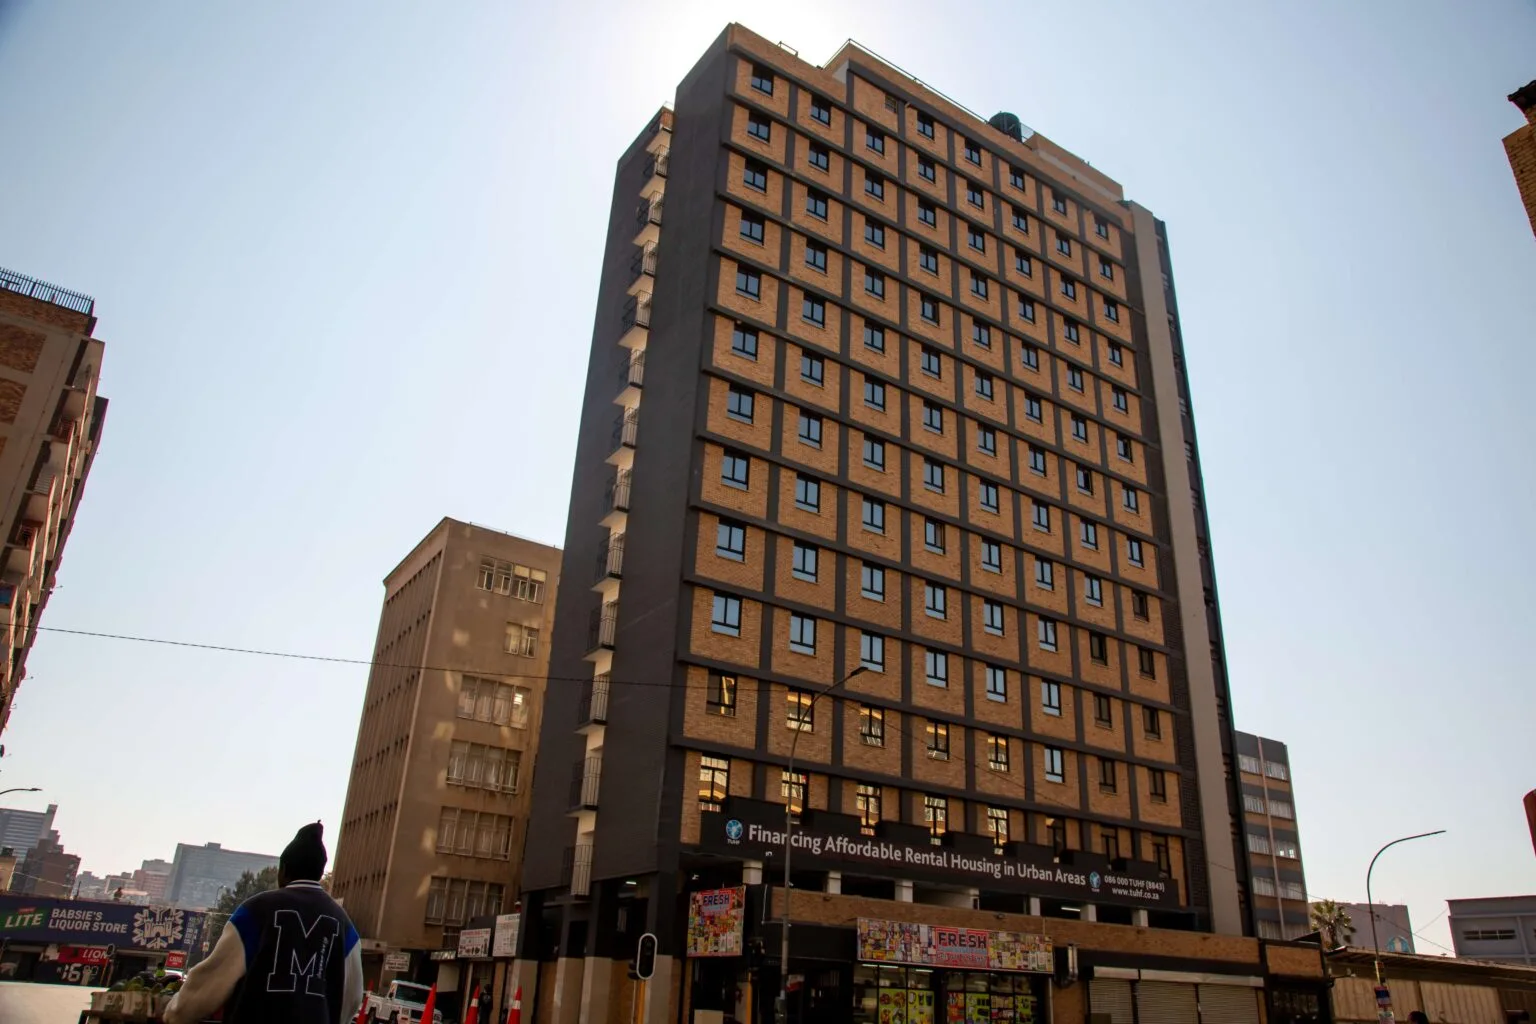
Purchasing a commercial property requires proper attention and vigilance. Many people focus on building residential properties in lesser-known cities in South Africa. It does not matter whether you are running a business, building your investment portfolio, or just developing a property; you should focus on all vital factors. Commercial spaces are not cheap. Most people need solid financing to get in the game. If you are hoping to snag a property in 2026, it pays to know how commercial property loans work and what financial institutions want to see from you.
What are commercial property loans?
Commercial property loans South Africa help builders and investors raise funds to renovate or refinance properties. The property you plan to purchase should generate an income. Think office parks, shops, apartments, warehouses, factories, or buildings that have a mix of uses. What is the big difference from residential loans? Lenders care less about you and more about the property itself. They assess the value, your purpose, and the money it brings in. Of course, they will also look at your ability to keep up with payments.
Getting a handle on loan rates
Interest rates of property funding in South Africa matter. They are not carved in stone. Lenders set different rates depending on the loan size, the property type, how much of the price you are covering with your own money, your business’s finances, and how risky they think you are. Sometimes, you will get a fixed rate. Sometimes, it is variable. It really depends on the bank or financial institution and the deal you strike. Don’t just grab the first low rate you see. Fees add up. Consider valuation costs, legal fees, initiation fees, and administrative expenses. Make sure you are comparing the real, total cost of each loan.
What do lenders want to see?
You can’t walk in empty-handed. When applying for commercial property loans South Africa. Be ready to show off your business registration details, up-to-date financial statements, bank records, tax numbers, and everything about the property you want to buy. Lenders will assess your credit history, check debts, and ask about how your business is doing and where it is heading. If you are buying a place to rent out, expect them to ask for lease information and proof of income from tenants. They will want to send someone out to value the property. It is all about location, condition, potential rental earnings, and market demand.
How to boost your chances?
Start by getting your paperwork straight. Having a decent deposit makes your application look stronger. It lowers the lender’s risk. Don’t just wing it. Put together a sensible business or investment plan, especially if your goal is to earn rental income. Finally, be honest with yourself about what you can afford.
0 comments
Log in to leave a comment.
Be the first to comment.