
Chapter 13 Bankruptcy in Georgia: How the Repayment Process Works
Understand how Chapter 13 bankruptcy in Georgia can help you manage debt, catch up on missed mortgage payments, and protect eligible assets through a structured repayment plan.
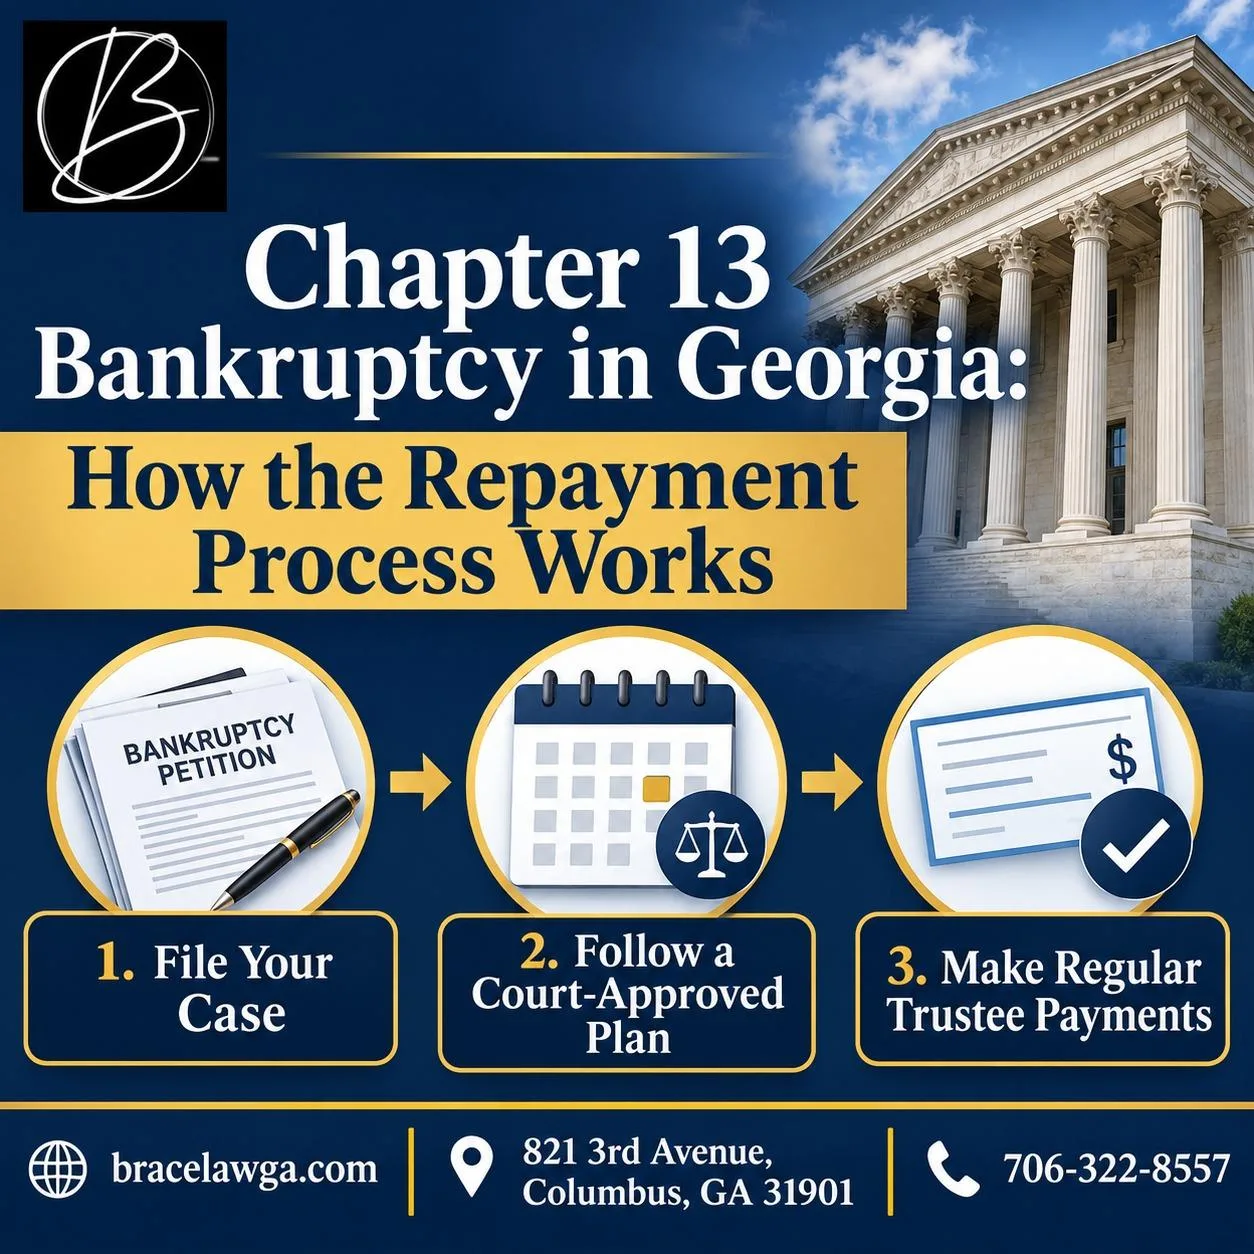
Falling behind on mortgage payments dealing with credit card debt are struggling to catch up on your payments can put a lot of pressure on your finances. Sometimes the problem is not that you have no income. It's that your monthly debt payments have become too difficult to manage alongside everyday expenses. If you are facing this situation chapter 13 bankruptcy in Georgia might offer a way to recognise your debts while keeping certain assets including your home or vehicle depending on your circumstances. Unlike Chapter 7 bankruptcy which involves liquidation of nonexempt assets Chapter 13 allows you to propose a repayment plan lasting 3 to 5 years. You can make payments through a bankruptcy trustee who distributes the money to creditors according to the approved plan.
What Is Chapter 13 Bankruptcy and How Does It Work?
According to chapter 13 bankruptcy attorney, it is a federal debt repayment process designed for individuals who have a regular income but need more time to manage the financial recognition. Instead of immediately selling non exempt property to repay creditors you propose a repayment plan based on your income expenses and financial circumstances. For example if you have fallen behind on your mortgage payments but can afford your regular monthly installments chapter 13 might allow you to catch up on missed payments over the repayment time while continuing to make current payments.
Who Can File Bankruptcy in Georgia Chapter 13?
Not everyone qualifies for chapter 13. You must meet specific requirements unreal bankruptcy law.
Generally, you may qualify if:
You are an individual with regular income, including qualifying self-employment income.
Your secured and unsecured debts fall within the applicable legal limits.
You have completed the required credit counseling.
You have not been disqualified by certain previous bankruptcy dismissals.
How to file chapter 13 bankruptcy in georgia?
Review your income debts and expenses
Firstly you need to start by understanding exactly where your money goes each month. Make a list of outstanding debts and monthly income expenses and other financial responsibilities
You will generally need:
Recent pay stubs or income records
Federal tax returns
Bank statements
Mortgage and vehicle loan statements
Credit card and personal loan balances
Monthly household expenses
Details of your property and other assets
Complete credit counseling
Most individuals need to complete a credit counselling course when approved agency within 180 days before filing bankruptcy.
File your bankruptcy petition and repayment plan
You must submit the required bankruptcy forms including details about your income expenses and liabilities. Your proposed chapter 13 prepayment plan must explain how you intend to repay your debt.
Attend the meeting of creditors
After filing you will generally attend a meeting under section 341 of the Bankruptcy Code. The trustee reviews your financial information and also asks questions about your debts and income.
Get your repayment plan approved
The bankruptcy court holds a confirmation process to decide whether your proposed payment plan meets the legal requirements.
What Debts Can Be Included in a Chapter 13 Repayment Plan?
Debt category | How it may be treated |
Credit card debt | May receive partial repayment |
Medical bills | May receive partial repayment |
Mortgage arrears | Can generally be repaid over the plan period |
Car loans | May be treated under applicable secured debt rules |
Certain tax debts | Priority tax claims generally require full payment |
Child support and alimony | Domestic support obligations must generally remain current and are not discharged |
Chapter 13 bankruptcy in Georgia can give eligible individuals time to manage debts without immediately losing property through liquidation. But it requires a realistic repayment plan and a commitment took making payments for 3 to 5 years. Before filing review of financial situation understand which depths can be addressed.
0 comments
Log in to leave a comment.
Be the first to comment.