
Cashback vs. Discount: Which Saves You More?
Is 5% back better than 5% off? The numbers often look the same, but the two deals do not work the same way. Before you compare them, it helps to know how much you spend in a normal month. If you spent $240, $310 and $275 over three months, an average finder shows $275 a month, and that gives you a real number to test each offer with.
What a Discount Does
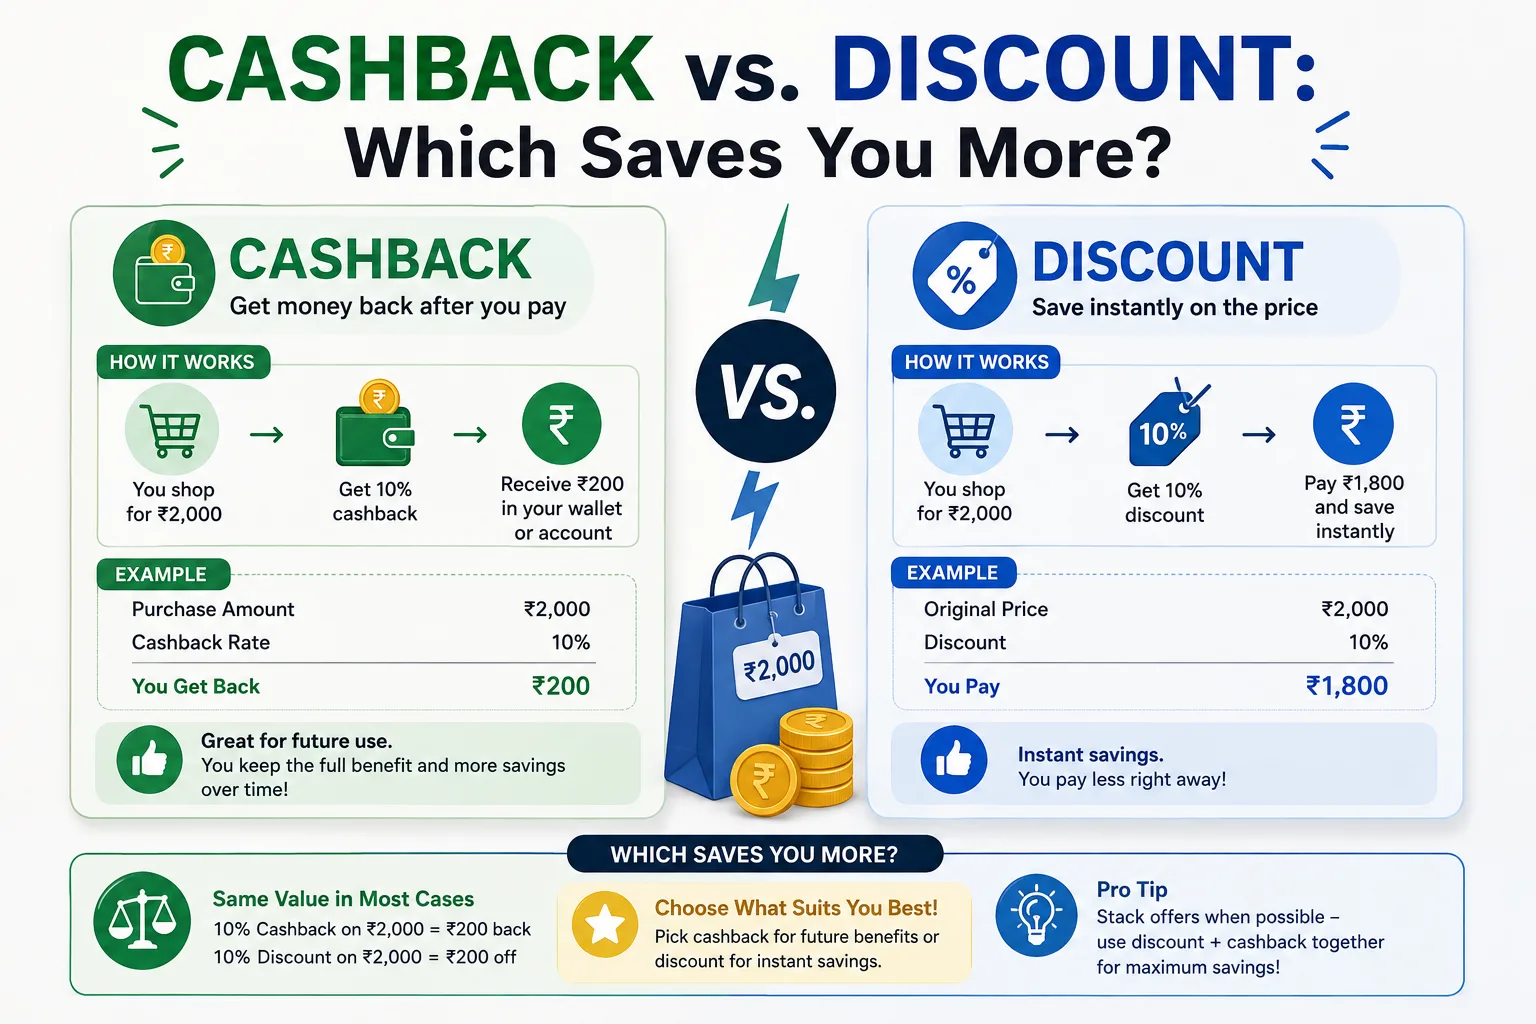
A discount makes the price lower right away. You see the smaller price at the checkout and you pay that smaller price. Nothing else needs to happen.
Say a $200 jacket has 5% off. Five percent of $200 is $10, so you pay $190. That is the end of the story. The money never leaves your pocket in the first place.
What Cashback Does
Cashback works the other way round. You pay the full price first. A part of it comes back to you later.
Take the same $200 jacket with 5% cashback. You pay $200 today. After a while, you get $10 back. In the end the jacket costs you $190.
So Are They the Same?
If the percentage is the same, the final cost is the same, as long as the cashback really arrives. Both ways end at $190. That is why the real differences are not about the amount. They are about three other things:
Time. A discount helps now. Cashback helps later.
Certainty. A discount is sure once you see it. Cashback needs the rules to be met.
Rules. Cashback may have limits, a waiting time, or a minimum amount before it is paid.
When One Clearly Wins
Always compare the percentages first. Here are three quick examples.
Bigger discount. A 10% discount on $200 means you pay $180. A 5% cashback means you pay $190 in the end. The discount wins by $10.
Bigger cashback. An 8% cashback on $150 gives you $12 back. A $10 discount is smaller, so the cashback wins by $2.
Fixed amount. A $15 discount on a $120 item is the same as 12.5%, because 15 ÷ 120 = 0.125. Turn money amounts into percentages so you can compare them fairly.
How to Compare Two Offers
You can do this in three simple steps.
Find the final cost with the discount: price minus the discount.
Find the final cost with the cashback: price minus the cashback you expect.
Pick the lower number, then think about time and rules.
For step 2, a cash back calculator can work out the amount you get back, so you can check your own sum. The rate on the offer is not always the rate you really get, because some items may not count.
What Makes Cashback Weaker
Cashback can be worth less than it looks. Check for these things:
A waiting time before the money is paid
A limit on how much you can earn
Items that do not count
Cashback taken back if you return the item
What Makes a Discount Weaker
Discounts have their own problems. You may need a code, a minimum spend, or a membership. Many only last a short time, and some do not mix with other deals.
A Real Example With Two Shops
Shop A gives 4% off a $250 pair of shoes, so you save $10 and pay $240. Shop B gives 6% cashback, so you get $15 back and the shoes cost $235 in the end. Shop B looks better by $5.
But what if Shop B only pays up to $10 in cashback? Then the shoes cost $240 in the end, the same as Shop A. Always read the limit before you decide.
Why Your Monthly Spend Matters
A small difference becomes bigger if you shop often. Using the $275 monthly average from earlier, a gap of 2% is worth 275 × 0.02 = $5.50 a month. Over 12 months that is $66. So for regular shopping, a slightly better rate is worth choosing, but for a one-off purchase the difference may be only a few dollars.
Do Not Forget the Timing
Time can change which deal is better. Imagine a sale ends on 30 November, and you are deciding on 20 October. That gives you 41 days. If the cashback only arrives after 45 days, you will wait even longer than the sale lasts. A day counter shows how many days are left on a sale and how long you would wait for the money.
Waiting is not always bad. But if you need the money soon, a discount you get today is worth more to you than cashback that comes in two months.
Quick Checklist
Compare percentages, not words like "back" or "off".
Change money amounts into percentages.
Read the rules for limits and waiting times.
Choose the deal that fits your needs, not just the biggest number.
Final Thoughts
A discount and cashback can end at the same price, but they feel different. One is certain and quick. The other can be slower and has rules. Do the sum, read the terms, and pick the one that works best for you.
0 comments
Log in to leave a comment.
Be the first to comment.