
Before You Sell: 7 New York Commercial Property Valuation Factors
What Property Owners in Yonkers, Westchester and Beyond Should Know to Price Their Building Right
A commercial property can generate steady rental income and still attract offers below the owner's expectations. The difference often comes down to how buyers evaluate income, operating expenses, lease quality, property condition, and market risk. Before setting an asking price, owners need to understand what supports the property's value—and which assumptions could weaken it.
Working with a Commercial Real Estate Broker In New York can help property owners assess these factors, interpret comparable transactions, and develop a pricing strategy grounded in market evidence rather than expectations alone.
How Is a Commercial Property Valued in New York?
Commercial property valuation generally considers the property's income-producing capacity, comparable sales, physical condition, and investment risk. For income-producing multifamily and mixed-use assets, net operating income (NOI) and the capitalization rate are especially important because they connect property performance with estimated market value.
Three valuation approaches are commonly considered:
- Income capitalization approach: Estimates value from the property's operating income and an appropriate capitalization rate.
- Sales comparison approach: Evaluates the property against comparable assets that have sold, adjusting for relevant differences.
- Cost approach: Considers the cost of replacing the improvements, less depreciation, plus the value of the land.
For stabilized apartment buildings and mixed-use properties, the income approach is often central to investor analysis. However, the appropriate methodology depends on the asset, available evidence, and intended valuation purpose.
An asking price should reflect more than the owner's original purchase price, renovation budget, or preferred return. Buyers generally evaluate what the property can produce, what risks accompany that income, and how the acquisition compares with alternative investments.
What Are the Seven Factors That Can Change Your Asking Price?
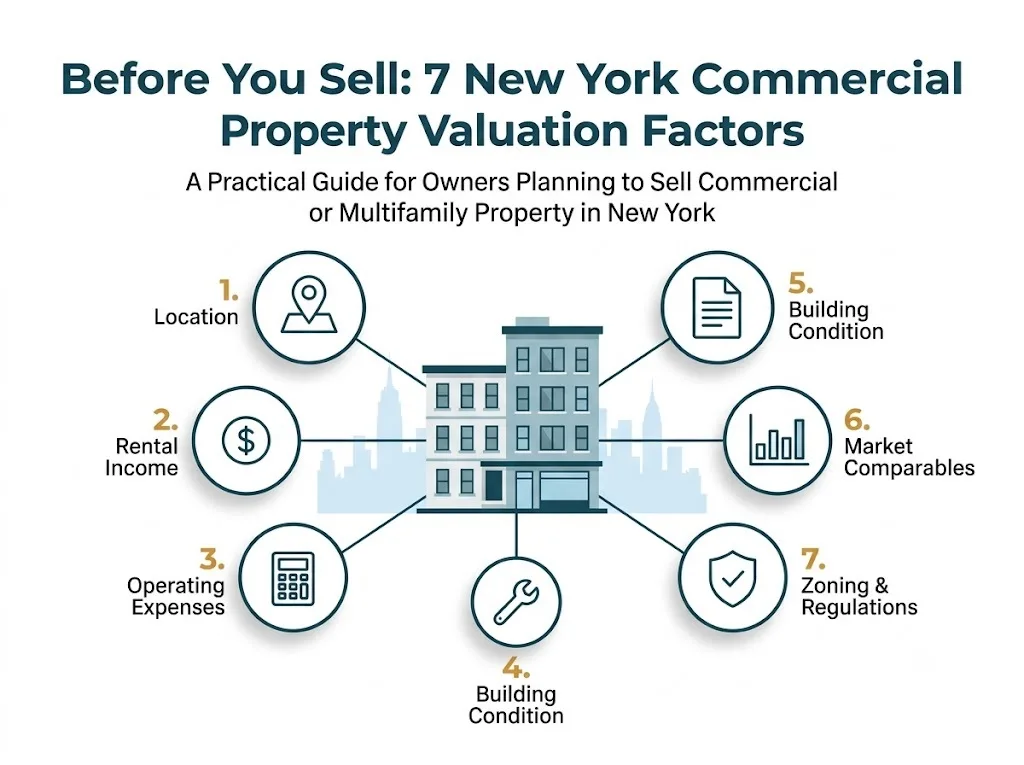
Seven major factors influence commercial property pricing: net operating income, capitalization rates, comparable sales, lease quality, operating expenses, physical condition, and financing and market conditions. Together, these factors help determine whether an asking price is supported by the property's financial performance and the expectations of prospective buyers.

1. Net Operating Income: What Does the Property Actually Earn?
Net operating income is one of the most important inputs in income-producing property valuation. It represents property revenue after operating expenses but before debt service, income taxes, depreciation, and amortization.
A simplified calculation is:
NOI = Effective Gross Income − Operating Expenses
Effective gross income accounts for rental income after applicable vacancy and collection losses, along with other property income. Operating expenses may include repairs, maintenance, insurance, property taxes, utilities paid by the owner, and management expenses.
Consider an apartment building with annual effective gross income of $800,000 and operating expenses of $300,000. Its NOI is $500,000.
If the owner's financial statements omit recurring maintenance or underestimate management costs, the reported NOI may overstate the property's sustainable earnings. Buyers may adjust those figures during due diligence, potentially reducing their offers.
Sellers should therefore reconcile rent rolls, leases, bank records, and trailing-12-month financial statements before marketing the property.
2. Capitalization Rate: How Does the Market Price Investment Risk?
The capitalization rate, or cap rate, expresses a property's annual NOI as a percentage of its value. A higher cap rate generally corresponds to a lower valuation for the same NOI, while a lower cap rate produces a higher valuation. The appropriate rate depends on factors such as location, asset quality, income stability, and perceived risk.
The basic formula is:
Property Value = NOI ÷ Capitalization Rate
Suppose a property generates $500,000 in annual NOI.
Assumed
cap rate
Implied
property value
5.0%
$10,000,000
5.5%
$9,090,909
6.0%
$8,333,333
6.5%
$7,692,308
This illustrates how relatively small changes in the assumed cap rate can produce substantial differences in estimated value.
Sellers should avoid selecting a cap rate solely because another property reportedly sold at that level. Differences in building condition, tenant stability, lease structure, location, and capital requirements may justify different pricing.
3. Comparable Property Sales: Are You Comparing Similar Assets?
Comparable sales help establish whether an asking price is consistent with observed market transactions. However, the usefulness of a comparable depends on how closely it matches the subject property in location, property type, size, operating performance, condition, and transaction circumstances.
For multifamily and mixed-use properties, useful comparison points may include:
- Sale price per unit
- Sale price per square foot
- Capitalization rate, where reliable NOI data is available
- Occupancy and rent levels
- Building age and physical condition
- Recent capital improvements
- Tenant mix and lease structure
A recently sold building nearby may appear comparable but have lower maintenance requirements, stronger rents, or a more favorable financing profile.
A sound valuation analysis explains these differences rather than relying on a simple average of asking prices or reported sales. It should also distinguish asking prices from completed transactions, since listed properties have not necessarily achieved their advertised values.
4. Rent Rolls and Lease Terms: How Reliable Is the Income?
A rent roll shows the property's tenants, occupied units or spaces, contractual rents, and other relevant leasing information. Lease terms determine how secure that income may be and how easily it can change over time. Buyers examine both to understand current cash flow and future income risk.
Important considerations include:
- Contractual rent compared with market rent
- Lease expiration dates and renewal options
- Vacancy and collection history
- Tenant concentration
- Arrears and concessions
- Retail tenant improvement obligations
- Renewal rights and expense-recovery provisions
For a mixed-use property, the stability of retail income may differ significantly from that of residential income. An approaching commercial lease expiration can create uncertainty around renewal, tenant improvements, downtime, and future rent.
Sellers should ensure that the rent roll matches the executed leases and that material concessions, arrears, and vacancies are disclosed accurately. Unsupported assumptions about future rent increases should not be presented as existing income.
5. Operating Expenses: Are the Numbers Sustainable?
Operating expenses directly affect NOI and therefore influence income-based valuation. Buyers often review historical expenses to determine whether costs are recurring, understated, unusually high, or likely to change after closing.
Property taxes deserve particular attention in New York. Buyers should examine the current tax burden, relevant assessment information, and any applicable exemptions or pending matters. They should not assume that the seller's existing tax bill will remain unchanged indefinitely.
Other important expense categories include insurance, utilities, repairs, maintenance, management, landscaping, snow removal, and contracted services.
Expense normalization requires judgment. Removing a one-time expense may be reasonable if it is genuinely nonrecurring, but excluding routine maintenance or management costs can create an unrealistic NOI figure.
A defensible asking price starts with a credible operating statement—not an artificially improved version of the property's financial performance.
6. Physical Condition and Capital Expenditures: What Will Buyers Need to Spend?
Property condition affects both immediate ownership costs and long-term investment returns. Buyers consider deferred maintenance, major building systems, environmental concerns, and expected capital expenditures when determining how much they can justify paying.
For an apartment building, due diligence may include reviewing the roof, façade, plumbing, electrical systems, heating equipment, elevators, and life-safety systems. Mixed-use properties may also require closer examination of retail-specific improvements and tenant obligations.
A seller does not necessarily need to complete every proposed improvement before listing. The more important task is to understand the condition of the asset, document completed work, and evaluate which repairs could materially affect buyer confidence or transaction terms.
For example, a documented roof replacement may reduce uncertainty about near-term capital spending. Conversely, evidence of significant deferred maintenance may lead buyers to request credits, negotiate a lower price, or seek additional inspections.
7. Financing and Market Conditions: What Can Buyers Realistically Pay?
Financing conditions influence acquisition feasibility and the pool of buyers able to pursue a property. Borrowing costs, lender underwriting requirements, available leverage, and debt-service coverage can affect investor returns and purchasing power.
Buyers may evaluate debt service coverage ratio (DSCR), loan-to-value ratio (LTV), debt yield, amortization, and refinancing risk. A property with reliable income and manageable capital needs may appeal to a broader range of investors than an asset requiring substantial improvements or complex financing.
Market conditions matter as well. Changes in buyer demand, comparable transactions, credit availability, and perceived risk can influence the cap rate buyers require.
Sellers should therefore base pricing on current evidence and the likely buyer pool rather than assume that past market conditions will continue. A property can have strong fundamentals while still requiring a pricing adjustment to reflect the capital markets at the time of sale.
Asking Price vs. Achievable Sale Price: What Is the Difference?
An asking price is the seller's initial offer to the market. An achievable sale price is the amount a qualified buyer may realistically agree to pay after evaluating the property, negotiating terms, securing financing, and completing due diligence. The two can differ because of valuation assumptions, competition, property condition, and transaction-specific risks.
Consideration
Asking
price
Achievable
sale price
Basis
Seller's pricing strategy
Negotiated market evidence
Income assumptions
May include projected improvements
Subject to buyer verification
Property condition
Based on available information
Influenced by inspection findings
Financing
May reflect seller expectations
Constrained by buyer underwriting
Due diligence
Often incomplete at listing
Refined as risks are investigated
Net proceeds
Not yet established
Calculated after selling expenses
A realistic pricing strategy can support meaningful buyer interest without requiring the seller to accept the first offer. The goal is to position the property competitively while preserving negotiating leverage.

What Should You Prepare Before Requesting a Broker Opinion of Value?
A broker opinion of value (BOV) is a market-based estimate prepared by a real estate broker using available property information and relevant market evidence. It can help owners evaluate pricing and disposition options, but it is not automatically equivalent to a formal appraisal or a guaranteed sale price.
Before requesting a BOV, organize the following:
- Current rent roll and executed leases.
- Trailing-12-month income and expense statements.
- Recent operating budgets and property tax information.
- Records of major capital improvements and outstanding repairs.
- Occupancy history, arrears, and tenant concessions.
- Available building, zoning, permit, and environmental records.
- Existing mortgage details and relevant sale or refinancing objectives.
Clear documentation helps the broker assess the property's income, identify potential buyer concerns, and select relevant comparable transactions.
Owners evaluating commercial real estate investment sales should also clarify their priorities. Maximizing gross sale price, reducing execution risk, achieving a timely closing, and optimizing net proceeds are related but distinct objectives.
How Can a Commercial Real Estate Broker Help Set a Defensible Asking Price?
A broker can help sellers interpret market evidence, evaluate income and expenses, compare relevant transactions, and develop a pricing and disposition strategy. The value of that work lies in explaining how buyers are likely to underwrite the asset—not simply recommending a number that matches the owner's expectations.
When evaluating Experienced Commercial Real Estate Brokers In New York, owners should look for familiarity with the relevant asset class, a clear valuation methodology, transparent assumptions, and the ability to discuss downside risks alongside potential value.
A useful pricing discussion should address:
- The assumptions behind the estimated value
- The reliability and limitations of comparable sales
- The difference between current and stabilized NOI
- Likely buyer objections and due diligence risks
- Expected marketing and negotiation considerations
- Estimated transaction expenses and net proceeds
For owners of multifamily and mixed-use assets, New York Commercial Real Estate Brokers should also be able to explain how local property characteristics influence investor demand and transaction pricing.
NuRealty Advisors Inc. provides commercial real estate brokerage and advisory services for investors and property owners evaluating investment sales, acquisitions, and disposition strategies. A property-specific discussion can help clarify which valuation factors deserve closer examination before an asset is brought to market.

Frequently Asked Questions
1. How is a commercial property valued in New York?
Commercial property valuation commonly uses the income capitalization, sales comparison, and cost approaches. For income-producing assets, buyers often focus on NOI and the capitalization rate, alongside comparable sales, lease terms, physical condition, and market risk. The appropriate method and assumptions depend on the property type and intended use of the valuation.
2. What is the most important factor in commercial property valuation?
There is no single factor that determines every property's value. For stabilized income-producing assets, NOI and the capitalization rate are often central. However, lease quality, location, vacancy, capital expenditure requirements, comparable transactions, and financing conditions can materially affect the final valuation and the price a buyer is willing to pay.
3. How does NOI affect a commercial property's asking price?
NOI measures property income after operating expenses and before debt service and income taxes. Under the income capitalization approach, estimated value is calculated by dividing NOI by the applicable cap rate. If sustainable NOI decreases while the cap rate remains constant, the implied value generally decreases as well.
4. What is a good cap rate for commercial property in New York?
There is no universally appropriate cap rate for all commercial properties in New York. The rate depends on asset class, location, income stability, condition, lease structure, capital requirements, and investor risk expectations. Sellers should evaluate relevant completed transactions and explain differences between their property and the selected comparables.
5. How do I determine the asking price for a multifamily building?
Start by verifying the rent roll, historical income, operating expenses, and sustainable NOI. Then examine comparable sales, relevant cap rates, building condition, capital requirements, and buyer financing considerations. A valuation range supported by multiple scenarios is generally more useful than relying on one comparable sale or a desired selling price.
6. Should I renovate my property before selling it?
Not always. Improvements may increase buyer appeal or reduce concerns about deferred maintenance, but their cost may exceed the value they add. Owners should compare the cost of proposed work with its likely effect on pricing, marketability, and execution risk before committing capital.
7. What is a broker opinion of value?
A broker opinion of value is a broker's estimate of a property's likely market value based on available financial information, comparable transactions, and market analysis. It can support pricing and sale planning, but its scope differs from a formal appraisal. Owners should understand the assumptions, intended use, and limitations of the analysis.
8. How long does it take to sell a commercial property in New York?
The timeline varies with property type, pricing, buyer demand, financing, due diligence, and transaction complexity. Marketing and negotiation are only part of the process; inspections, document review, lender approval, title work, and closing requirements can extend the schedule. Sellers should discuss likely timelines and potential obstacles before listing.
9. What documents should I prepare before selling commercial real estate?
Prepare the rent roll, executed leases, historical financial statements, operating budgets, property tax information, capital improvement records, and available building and zoning documents. Mortgage information, environmental reports, permits, and maintenance records may also be relevant. Organized documentation helps buyers verify assumptions and can reduce avoidable delays during due diligence.
10. How do I choose a real estate brokerage company in New York?
Evaluate relevant transaction experience, local market knowledge, valuation methodology, communication practices, marketing capabilities, and familiarity with your property's asset class. A Real Estate Brokerage Company In New York should be able to explain its pricing assumptions, identify transaction risks, and distinguish an estimated market value from a guaranteed sale outcome.
Final Takeaway
A defensible commercial property asking price begins with verified financial performance and a clear understanding of how buyers evaluate risk. NOI, capitalization rates, comparable sales, lease terms, expenses, physical condition, and financing conditions all influence the valuation process.
Before listing, owners should reconcile their operating records, document the property's condition, examine comparable transactions, and understand the difference between headline price and net proceeds.
For investors and owners considering a sale, Commercial Real Estate Broker In New York is more than a search for transaction representation. It is a starting point for evaluating the expertise, market evidence, and analytical discipline needed to make a well-informed disposition decision.
NuRealty Advisors Inc.
571 S Broadway, Yonkers, NY 10705, United States
+1 914-670-7065
0 comments
Log in to leave a comment.
Be the first to comment.