
Adipic Acid Market: Automotive Demand & Engineering Plastics Trends 2026-2034
Market Overview:
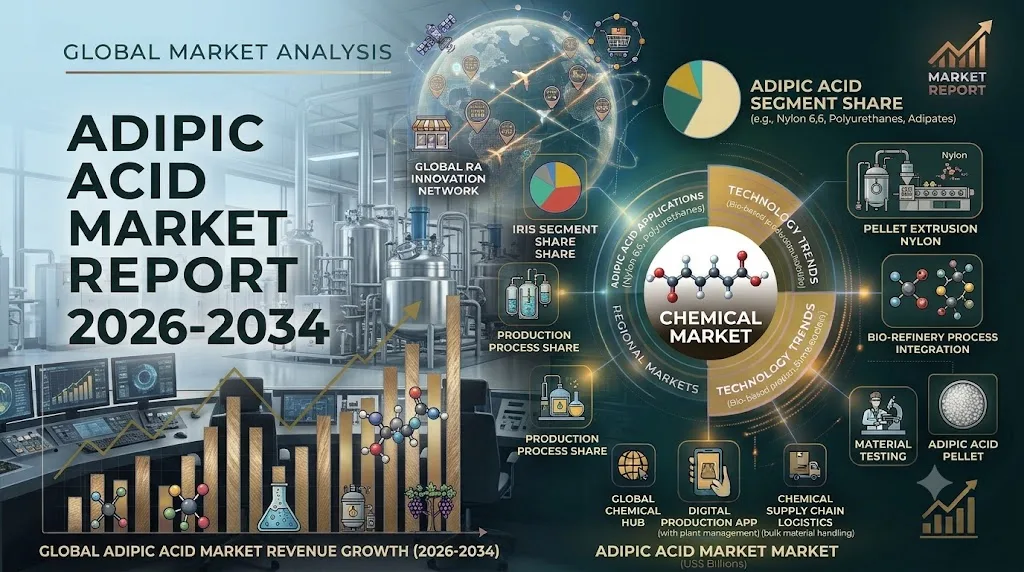
According to IMARC Group’s latest research publication, “Adipic Acid Market: Global Industry Trends, Share, Size, Growth, Opportunity and Forecast 2026-2034”, The global adipic acid market grew from USD 6.9 Billion in 2025 to USD 7.3 Billion in 2026. Looking forward, IMARC Group estimates the market to reach USD 10.7 Billion by 2034, exhibiting a CAGR of 5.03% from 2026-2034.
This detailed analysis primarily encompasses industry size, business trends, market share, key growth factors, and regional forecasts. The report offers a comprehensive overview and integrates research findings, market assessments, and data from different sources. It also includes pivotal market dynamics like drivers and challenges, while also highlighting growth opportunities, financial insights, technological improvements, emerging trends, and innovations. Besides this, the report provides regional market evaluation, along with a competitive landscape analysis.
How AI is Reshaping the Future of the Adipic Acid Market
- AI-driven catalyst screening and bioprocess optimization are accelerating the scale-up of bio-based adipic acid, enabling manufacturers to shorten experimental cycles and reduce dependence on cyclohexane oxidation routes that generate significant nitrous oxide emissions.
- Machine learning tools are being applied to supply chain optimization across the nylon 66 value chain, helping producers manage raw material volatility in cyclohexanol and cyclohexanone procurement, which is critical given that tariffs have significantly increased production costs for imported inputs.
- AI-enabled predictive maintenance and process control at large-scale adipic acid facilities in Asia-Pacific, which accounts for 40% of global market share, are improving output reliability and reducing downtime across integrated polyamide manufacturing operations.
- In China, where domestic adipic acid capacity is projected to reach 4.455 million tons and total output to stabilize around 2.77 million tons, AI-powered demand forecasting tools are being deployed to navigate supply surplus conditions and optimize export pricing strategies.
- Bio-based adipic acid production capacity in China is projected to reach between 30,000 and 50,000 tons, with AI-accelerated fermentation route development using renewable feedstocks playing a critical role in achieving cost parity with conventional fossil-based production.
Download a sample PDF of this report: https://www.imarcgroup.com/adipic-acid-market/requestsample
Key Trends in the Adipic Acid Market
- Growing Demand for Lightweight Automotive Materials: The escalating demand for lightweight materials in the automotive sector is significantly driving adipic acid consumption globally. Nylon 66, produced using adipic acid, is increasingly replacing traditional metals in engine covers, air intake manifolds, radiator end tanks, and structural under-hood parts due to its superior strength-to-weight ratio and thermal resistance. Global car production exceeded 92.5 million units in 2024, sustaining robust demand for nylon 66-based engineering plastics. Electric vehicle adoption is further amplifying this trend, with global electric car sales exceeding 17 million units in 2024, driving demand for lightweight nylon 66 components that extend battery range and improve energy efficiency.
- Rising Focus on Sustainable Bio-Based Production: Increasing emphasis on environmental sustainability is transforming the competitive dynamics of the adipic acid market. Conventional manufacturing through cyclohexane oxidation generates significant nitrous oxide emissions. Through the European Green Deal, the European Union has established a target to reduce greenhouse gas emissions by at least 55% by 2030, encouraging manufacturers to transition toward bio-based and recycled chemical production methods. The adoption of mass-balance approaches for producing bio-circular nylon 66 from sustainable feedstocks is gaining traction among leading manufacturers, positioning sustainability as a core driver of long-term market evolution.
- Expanding Polyurethane and Plasticizer Applications: Growing utilization of adipic acid in polyurethane and plasticizer manufacturing is creating significant demand expansion beyond traditional nylon applications. Adipic acid-based polyester polyols are essential components in flexible and semi-rigid polyurethane foams widely used in furniture, insulation, and footwear. Additionally, adipate esters are gaining prominence as non-phthalate plasticizers in flexible PVC products, benefiting from regulatory shifts in Europe and North America that favor safer plasticizer formulations. Plasticizers currently lead the application segment with a 26% market share, reflecting broad adoption across medical tubing, food packaging films, construction floors, and automotive cable insulation.
- Asia-Pacific’s Manufacturing Dominance Reinforcing Supply Chains: Asia-Pacific commands 40% of the global adipic acid market, underpinned by large-scale chemical manufacturing facilities, strong automotive and textile sector demand, and favorable government support. China’s production of new energy vehicles exceeded 10 million units for the first time in 2024, driving substantial demand for lightweight nylon 66 automotive components derived from adipic acid. India is also emerging as a high-growth market, with its textile industry valued at USD 152.40 Billion in 2025, creating sustained demand for synthetic polyamide fibers manufactured with adipic acid.
- Construction and Infrastructure Spending Boosting Polyurethane Demand in MEA: The total value of construction contracts awarded in the UAE increased by 14% year-on-year in 2024, totaling USD 121 Billion, driving demand for polyurethane-based insulation materials and polymer-based construction products derived from adipic acid. As governments across the Middle East accelerate infrastructure development, the demand for flexible PVC and polyurethane applications that rely on adipic acid as a key feedstock is growing steadily, positioning the region as an emerging growth market.
We explore the factors propelling the adipic acid market growth, including technological advancements, consumer behaviors, and regulatory changes.
Growth Factors in the Adipic Acid Market
- Robust Automotive Production Sustaining Nylon 66 Demand: The automotive industry represents the largest end-user segment with a 32% market share, driven by the widespread adoption of nylon 66 engineering plastics in lightweight structural components, electrical connectors, and under-hood applications. The United States recorded production of 10,562,188 motor vehicles in December 2024, sustaining strong demand for nylon 66 components across the automotive supply chain. The rapid growth of the EV segment further reinforces this trend, with the United States electric car market valued at USD 102.6 Billion in 2025.
- Regulatory Push Toward Non-Phthalate Plasticizers: Stringent environmental regulations in Europe and North America are accelerating the substitution of traditional phthalate-based plasticizers with adipate ester alternatives. These non-phthalate formulations offer superior low-temperature performance and lower volatility, making them the preferred choice across consumer products, healthcare applications, and flexible packaging. The regulatory tailwind is contributing to consistent growth across the plasticizer application segment globally.
- Nylon 66 Fiber Demand Across Industrial and Consumer Applications: Nylon 66 fibers hold 33% of the end product market share, serving as the foundational material for seat belt webbing, tire reinforcement cords, airbag fabrics, industrial filtration materials, carpeting, ropes, and conveyor belts. The steady demand from both consumer and industrial sectors guarantees continuous consumption of adipic acid through nylon 66 fiber production channels worldwide, making this the largest single contributor to overall adipic acid utilization.
- US Electric Car Market Driving Incremental Polymer Demand: As per IMARC Group, the United States electric car market was valued at USD 102.6 Billion in 2025. EVs require lightweight polymer materials to maximize energy efficiency and driving range, with nylon 66 derived from adipic acid playing a critical role in battery housings, electrical connectors, and structural under-hood components. The growing EV fleet is therefore creating a sustained and expanding demand channel for adipic acid across the North American manufacturing base.
- Green Transition in China Creating New High-Value-Added Tracks: China’s adipic acid industry is accelerating its shift toward green and high-end development amid the “dual carbon” policy framework targeting carbon neutrality by 2060. Domestic bio-based adipic acid production is projected to reach between 30,000 and 50,000 tons, opening a new high-value-added production track. This transformation, driven by EU anti-dumping tariffs and strong policy guidance, is encouraging Chinese producers to invest in fermentation-based and catalytic biomass conversion technologies as a competitive differentiator in export markets.
Leading Companies Operating in the Global Adipic Acid Industry:
- Asahi Kasei Corporation
- Ascend Performance Materials
- BASF SE
- Domo Chemicals
- Invista (Koch Industries)
- Lanxess AG
- Radici Partecipazioni SpA
- Solvay S.A.
- Sumitomo Chemical Co. Ltd.
- Tangshan Zhonghao Chemical Co. Ltd.
- TCI Chemicals (India) Pvt. Ltd.
- Tian Li High & New Tech Co. Ltd.
Adipic Acid Market Report Segmentation:
Breakup By End Product:
- Nylon 66 Fibers
- Nylon 66 Engineering Resins
- Polyurethanes
- Adipate Esters
- Others
Nylon 66 fibers account for the largest share at 33%, driven by consistent demand from the automotive sector for seat belt webbing, tire reinforcement cords, and airbag materials, alongside industrial applications in filtration, carpeting, and ropes.
Breakup By Application:
- Plasticizers
- Unsaturated Polyester Resins
- Wet Paper Resins
- Coatings
- Synthetic Lubricants
- Food Additives
- Others
Plasticizers lead the application segment with a 26% share, supported by the growing adoption of non-phthalate adipate esters across flexible PVC products in construction, healthcare, food packaging, and automotive cable insulation.
Breakup By End User:
- Automotive
- Electrical and Electronics
- Textiles
- Food and Beverage
- Personal Care
- Pharmaceuticals
- Others
Automotive dominates with a 32% market share, spurred by the widespread use of nylon 66 engineered plastics in lightweight vehicle components and the rapid adoption of EVs requiring polymer-based materials.
Breakup By Region:
- North America (United States, Canada)
- Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
- Europe (Germany, France, United Kingdom, Italy, Spain, Russia, Others)
- Latin America (Brazil, Mexico, Others)
- Middle East and Africa
Asia-Pacific holds the leading position with 40% market share, driven by China’s comprehensive nylon 66 manufacturing infrastructure, India’s expanding textile industry valued at USD 152.40 Billion, and strong government support for industrial expansion across the region.
Recent News and Developments in the Adipic Acid Market
- July 2025: BASF completed the acquisition of DOMO Chemicals’ 49% stake in the Alsachimie joint venture, resulting in BASF becoming the exclusive owner of the production facility for key polyamide 6.6 precursors, including KA-oil, adipic acid, and hexamethylenediamine adipate in Chalampe, France. The purchase bolstered BASF’s operational presence at its European center for PA 6.6 manufacturing, improving backward integration and supply dependability throughout the value chain.
- February 2026: China’s adipic acid industry entered a critical green transformation phase driven by the “dual carbon” policy framework, with domestic bio-based adipic acid production capacity projected to reach between 30,000 and 50,000 tons. The shift was further accelerated by EU anti-dumping tariffs and sustained supply-demand imbalances, prompting Chinese producers to pivot toward fermentation-based and high-value-added production pathways to strengthen their competitive positioning in export markets.
- 2026: Toray Industries and PTT Global Chemical announced the development of manufacturing technology for bio-based adipic acid through fermentation-derived bio-muconic acid using cassava starch residues, alongside 100% bio-based nylon 6,6 technology. This development illustrated the industry’s shift toward residue-based feedstocks capable of reducing dependence on fossil carbon inputs and competing food-crop biomass, marking a significant step in the commercialization of sustainable adipic acid alternatives.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
About Us:
IMARC Group is a global management consulting firm that helps the world’s most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Contact Us:
IMARC Group
134 N 4th St. Brooklyn, NY 11249, USA
Email: [email protected]
Tel No: (D) +91 120 433 0800
United States: +1-201-971-6302
0 comments
Log in to leave a comment.
Be the first to comment.